Can I get a mortgage if my parents co-sign because of my poor credit?
Question of the week: Can I get a mortgage if my parents co-sign because of my poor credit?
Answer: Over the past year, years really, we have had several Questions of the Week that deal with credit reports; What can I do about my credit, Should we consolidate our credit, Why did my credit score drop, and How do inquiries impact my credit, are just a few of them.
What we have not addressed in several years is what if you have poor credit and want to buy a home. The question of if your parents, or another connected party, can help you purchase your new home if you have poor credit.
The quick answer is, No. Of the three factors that are considered for a borrower in loan qualifying, income, credit and cash to close, credit is the one area that outside assistance is not able to enable qualifying.
Mortgage underwriting guidelines state that the lowest middle credit score of all borrowers on an application is the score that will be used for qualifying and pricing the loan. For instance, Angela and Adam are recently married and wish to purchase a home. Angela’s credit scores from the three major credit agencies (Experian, TransUnion and Equifax) are 763, 744 and 768; her middle score is 763. Adam had a few issues in his past and his middle scores are 689, 703 and 679; his middle score is 689. Since Adam’s middle score is the lowest of the two, the score for the file is 689.
Some programs require a minimum score of 700 to be eligible. If one of these programs were the one Angela and Adam wanted for their home purchase or refinance they would not be eligible for the program. “Dennis, what can we do? Can my parents co-sign for us?”
If you are unable to qualify because your income is low, we can add a “non-occupant co-borrower” to your mortgage application to enable you to qualify. If you are short funds to close you can get a documented gift from your parents or other connected party to qualify. If you have a credit score that is too low for the loan program for which you are applying the only way you can qualify for that program is to increase your credit score.
All is not lost. There are different options that may be available to Angela and Adam to achieve their home purchase or refinance goal.
One option is to look at Adam’s credit report and see if there is something that can be done to increase his score. Perhaps paying an account down, or off, may raise the score the eleven or more points needed; or sometimes opening an account will get the extra points needed. Not all credit reports are the same and the composite data that creates the credit score is influenced by many, many factors. Depending on what is on the report it may be fairly easy to increase the score.
A second option is to see if there is another program that may enable Angela and Adam to achieve their goal. While more expensive because of mortgage insurance, FHA mortgages are often used for clients with lower credit scores because their minimum scores for different programs are a lot lower than those for conventional and most jumbo programs. The decision factor in this case is the trade-off between the current higher mortgage cost due to the mortgage insurance versus the potential higher cost if waiting to purchase or refinance due to higher home values and/or rates. It is not an unusual reaction to want to have the mortgage product with the lower costs, however that product is not available to you, a change in mindset may be the most beneficial to you in the long term as you are able to purchase your home today.
A third option is that perhaps mom and dad can co-sign—with Angela. Depending on the ability of everyone involved and the mortgage program, by dropping Adam from the mortgage and adding mom and dad as co-signers the transaction may be able to continue.
One other option we have employed is for mom and dad to purchase the property as an investment property. Angela and Adam move in and make all the payments for the mortgage, property taxes and insurance. In the future, when Adam’s credit scores are better, depending on the rates and the market Angela and Adam may want to refinance to put the home and mortgage in their own name.
Since a low credit score cannot be cured with adding co-borrowers, it is advisable for you to know what is on your report and address any issues that are negatively impacting your credit as soon as you can. We have plenty of experience analyzing credit reports and assisting borrowers increase their scores. Sometimes this can happen in a short period of time, sometimes not. For the latter, I always bring up a client from more than twenty years ago, Yvonne.
Yvonne and her husband wanted to purchase their home but had undergone some economic traumas that resulted in low credit scores. Yvonne was determined to own her own home and for almost two years she worked to improve their credit. She would constantly check in with me and we would review her accounts and her plan, checking her credit report every 5-6 months to see where they stood. Finally, the day came when their credit was rehabilitated and they purchased their home. When I called to tell Yvonne her loan had funded and she was going to be a homeowner she was not the only one on the call with a catch in her throat and blurry eyes.
Poor credit and low scores can delay your home ownership, but do not let it prevent it. Be like Yvonne and tackle the problem as soon as you can.
In regard to parents co-signing, in March we answered, “Should we co-sign for our son or daughter’s home purchase.”
Have a question? Ask me!
This was a very busy week for market impacting news and data. In order of the announcements this week and positive or negative impact on rates:
One year after hitting a peak, consumer confidence in October was down slightly from September, but by less than prior months. Over the past year the consumer confidence chart looks like a ride at Knott’s Berry Farm. The valleys have been getting higher since January and the trend line looks like the next trend is back up. The over-riding news from the report is that consumers are reasonably confident and holiday spending should not be curtailed. Over all the news is somewhat negative for rates as high consumer confidence can lead to high consumer spending, which is about 65-70% of our economy, which leads to economic growth.
Consumer confidence and spending resulted in another positive quarter of growth for the Gross Domestic Product. The 3rd quarter increase of 1.9% was down a peg from the 2nd quarter growth, but higher than the 1.6% that was expected from most of the experts. Inside the report, the spending by consumers in the quarter more than counter-balanced a large drop in business investment caused by a drop in oil prices and the trade conflict with China. Showing stronger than expected growth, despite consumer spending dropping from the extremely strong 4.6% growth in the 2nd quarter to 2.9% in the 3rd quarter, plus residential housing investments increasing for the first time in five years, the GDP data is negative for mortgage rates.
Following the GDP data release was the announcement from the Fed that it cut its benchmark interest rate by 0.25%. This move was expected and on its own had not impact on mortgage rates. In making the rate announcement the Fed used its normal Fed-Speak to announce that it would likely take a pause before enacting any more rate cuts. Some investors have expected more rate cuts in the near future and a pause puts them on the wrong side of the market. From their announcement, it appears the Fed is content with the current path on rates as they forecast continued moderate growth in the economy, a continuing strong labor market and inflation very near its 2% target. Overall the news is a bit rate negative due to the Fed taking off the table the certainty of another rate increase and the more positive message than it has supplied in prior announcements.
Thursday, it was back to consumers as the Commerce Department released data for September on consumer spending, personal income and inflation. Consumer spending increased for the month at a mundane 0.2% rate, down from August’s dull 0.3% growth. While dull and mundane, September was the seventh month in a row of increased spending. The increase in spending was supported by higher earnings as incomes rose 0.3% in September, reflecting the strongest labor market in fifty years. With spending increasing at a slower pace than incomes it is not surprise that the savings rate increased to 8.3%, near post-recession highs and showing that while consumers are spending steadily they are doing so within budgets that enable saving as well—something that was absent prior to the Great Recession. Because the growth in spending and incomes have been moderate the pressure on prices has been the same, prices have increased only 1.3% from September 2018, the matching February as the lowest since 2016. This news is neutral for mortgage rates as it reflects an economy that is not booming nor busting but chugging along.
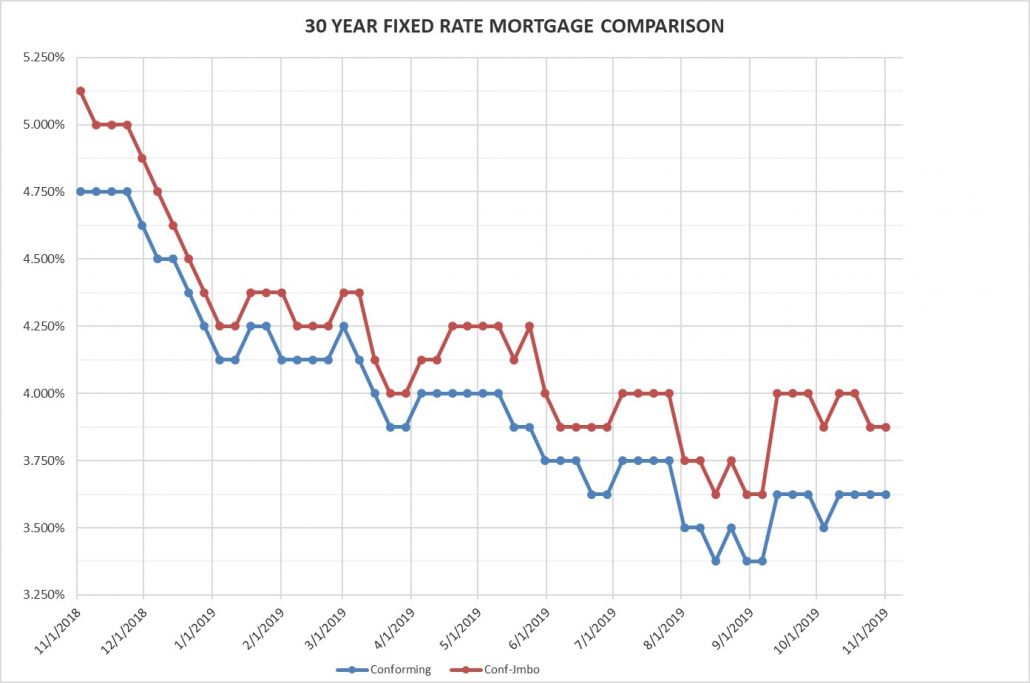
Rates for Friday November 1, 2019: Last week there was an error in the rate numbers below, the chart was correct but not the numbers, they did not reflect the 0.125% drop in the high-balance rate from the prior week. This week the high-balance rate further compresses to the conforming rate, which is flat this week. Following all the economic news reported today I was expecting rates to be a bit higher. We may be nearing the end of a cycle so a bump next week would not surprise me.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.625% Flat
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Do not forget to turn your clocks back before you go to sleep on Saturday night or you’ll be early for church…or is it late? I can never keep that part straight.
If you live anywhere in Southern California you have likely smelled smoke over the past few days. Unfortunately, it is that time of year again where too many of our fellow Californians are experiencing trauma and tragedy due to major fires. Here is what has become a semi-annual link I provide for those who are wanting to help: Donate to the Red Cross The Red Cross does what no other entity, public, private or non-profit, does when it comes to disaster relief and assistance, every little bit helps. If everyone who receives this Weekly Rate & Market Update donates just $10, more than $6000 will be raised to assist with food, blankets and housing. Take a minute and click-it!
I was half-right last Friday, the Washington Nationals did win their first World Series ever, but it took more games than I thought. How amazing that every game was won by the visiting team!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog