

What is the state loan program with no down payment?
Question of the week: What is the state loan program with no down payment?
Answer: This is a very popular topic this past week as several clients have contacted us to inquire about the California Housing Finance Agency’s (CalHFA)“California Dream For All Shared Appreciation” program. As part of the 2022-2023 budget, $300 million was set aside to finance this program to assist first time buyers obtain home ownership in California.
Dream For All will provide down payment and closing cost assistance for qualified borrowers up to 20% of the purchase price of the home in the form of a second trust deed. There are no payments required on the second mortgage, which extends the assistance beyond cash needed to close a new home purchase to lower income needed to qualify.
While there are no payments on the second mortgage, there is a cost, but not at closing. The program looks to self-fund future CalHFA programs by having “shared appreciation” as the cost of program. This means that when you go to sell your home, or refinance the mortgages, you will pay to CalHFA 20%* of the appreciation in your home’s value since the loans were funded. *If you borrow 10% on the second you will share 10% of the appreciation.
Example: You purchase a home for $500,000 with the program and obtain a $100,000 second mortgage with CalHFA as down payment. In five years you sell your home for $600,000, your appreciation is $100,000. At closing 20% of your appreciation, $20,000 (20% of the $100,000 appreciation), is sent to CalHFA; the remaining after paying of the primary mortgage and closing costs you will get the remaining proceeds from the sale.
Unlike past CalHFA programs, Dream For All has considerably higher income limits for applicants, greatly expanding the number of potential buyers eligible for the program.
Here are the basic parameters of the program:
- Only first-time buyers are eligible (defined as someone who has not owned and occupied their own home in the past three years; if you owned a home before but sold it at least threes years ago you are a first-time buyer)
- All borrowers must occupy the property as primary resident
- If married both spouses must be on the mortgage application and occupy the property
- Borrowers must complete two levels of homebuyer education counseling and obtain a certificate of completion through eligible counseling organization
- Meet the CalHFA income limits ($180,000 LA County, $235,000 Orange County)
- Property must be single-family, one-unit residence, including condos and PUDs approved by first mortgage lender
- Properties with ADUs (guest house, granny unit, etc) are eligible
Making this program easier to implement is the primary mortgage is conventional (either Fannie Mae or Freddie Mac), which means their loan limits ($726,200 conforming, $1,089,300 high balance).
CalHFA sets the interest rates for the program, currently 6.375% for conforming loan amount and 7.528% for high balance).
The combined loan-to-value of the first mortgage and second mortgage can go up to 105% of the purchase price; for instance for $500,000 sales price obtain a loan of 85% ($425,000) and a second for 20% of the sales price ($100,000) for a total of $525,000, or 105% of the sales price. The funds above the sales price can be used to pay closing costs. Note in this scenario the 85% first mortgage would require mortgage insurance.
I have compared the Dream For All program with FHA financing, which has a minimum down payment of 3.5%. Depending on how long you own the property and the appreciation of value, there is very little difference between the two programs when all factors are considered for all the money spent: down payment, closing costs at purchase, closing costs at sale, total of mortgage payments, and equity share. The biggest difference is the amount of money needed upfront for down payment for an FHA mortgage, that with the Dream For All program you would be able to keep in your accounts.
As mentioned above, the program is funded for $300 million. The median price statewide in California in February was $735,000. Using 20% of the median sales price for the amount of second mortgages funded for the program, the median loan amount for the second mortgage would be about $147,000. The program has enough money to fund just over 2,000 second mortgages for the Dream For All program. With the current pace of sales in California, and the limitations on who can utilize the program, the funds should be available well into 2024; unless there is a surge in transactions and first time buyers.
When asked what I thought of the program, my reply was that I like OPM, Other People’s Money, to enable me to retain cash. This is one reason why long-term readers of the WR&MU have read many times over the years why I like mortgage insurance and using leverage to purchase homes with low down payments. The Dream For All program penciling out to be very close to the total cost of ownership over time, including paying part of the home’s appreciation to CalHFA, makes it a very good option for many homebuyers.
Before jumping and applying for the program, let’s look at all the loan options available to you, including conventional and FHA products, to determine if the Dream For All program is your best option.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Softening, weakening, slowing, are the adjectives used in the media this week to describe economic data releases. The final estimate for GDP for the 4th quarter of 2022 was revised to 2.6%, down from initial estimates of 2.9% growth. Consumer sales slowed to 0.2% in February after very robust 1.8% increase in January, weaker sales in automobile and trucks, and hospitality spending in bars, restaurants and hotels were the primary cause for the low growth. The data, combined with an increase of 4.6% in the personal savings rate reflect a public that is slowing its spending either as a result of inflation, or in anticipation of a recession. Either reason results in less spending which slows our economy.
Also softening, was inflation according the to key inflation index used by the Federal Reserve when determining what direction to go with its benchmark interest rate. The Personal Consumption Expenditures Price Index (PCE) increased only 0.3% in February, after a 0.6% in January. Year over year the PCE index is up 5.00%, down from 5.3% in January. The news was well received by markets, a collective holding of breath was released on the news due to the Consumer Price Index showing inflation had increased 6% in February. For workers the lower PCE number is good news as personal incomes increased the same amount, 0.3%, for the month; wages keeping pace with inflation for the month for the first time in a while.
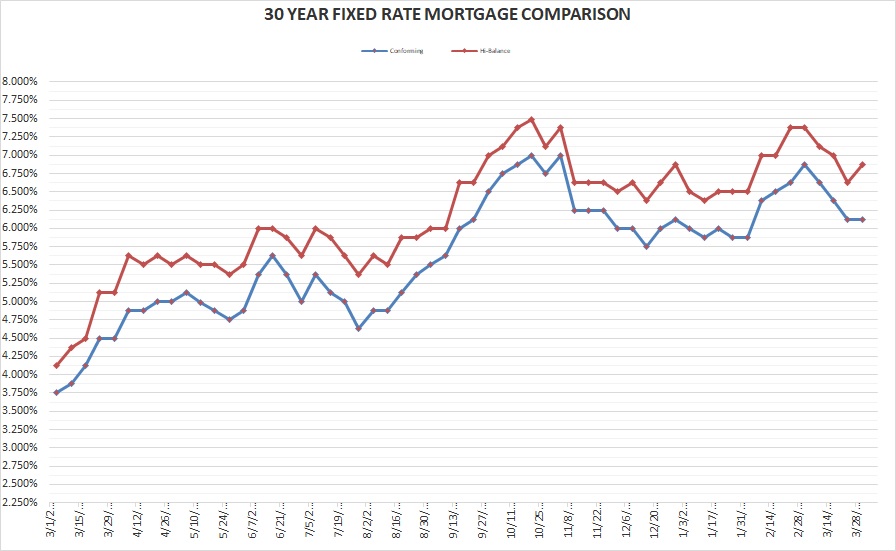
Rates for Friday March 31, 2023: A very slow week in the mortgage markets, a welcome slow week, as investors digested the data showing the economy and inflation is slowing; increasing the chances the Fed will slow rate increases sooner than later. Conforming rate is the same as last Friday and the high balance pops up for the week.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.125% Flat
30-year high-balance conforming 6.625% Up 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It’s here! Yesterday all major league teams started the 2023 season, and I am happy I can now have a ball game on in the background while I work. Whether my beloved Phillies against the unbeloved Mets, or the Mariners playing the Royals, if it is being broadcast I will listen. Some like to listen to soft jazz, or classical as their background music, I prefer the languid commentary and play-by-play of a baseball game.
There will be less background noise than prior seasons however due to the introduction of a pitch-clock to the league. Batters and pitchers must be ready and the batter’s box and pitching the ball within their time limits or face a penalty of a strike for batters or a ball for pitchers. Opening Day saw the impact of the pitch clock as of the games played five were over three hours and nine were under two and a half hours. For the last several seasons rare has been the game that finished in less than three hours.
Go Phillies!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


