

Youngsters think today’s rates are high.
Question of the week: Youngsters think today’s rates are high.
Answer: Okay, so it’s not a question.
This comment was made on a social media post from long-time (emphasize long) real estate agent Brian, who put up pictures of commercial mortgage rates, and some listing info for properties from what I have deduced to be 1993.
The commercial rates were adjustable rates at 8.75%, the homes were a listing of $129,900 in the North Long Beach section of Long Beach (estimated value today $650,000) and homes in the Park Estates area, which sold for $365,000 (estimated value today $1.2 – $1.6 million, possibly over $2 million).
The comment about “youngsters,” and “rates,” is not uncommon from those over a certain age as many of them purchased their first homes with rates of 12%, 15%, 18%…one individual of certain age told me discussing his children being able to buy, “heck my current payment is the same as my first house payment in 1988…”
I had to remind him that his current mortgage payment is based on a $250,000 loan with a rate of 2.75%, and his first house was purchased for $85,000. Apples to bananas in comparison when his kids, if buying today, are looking at home prices of $600,000 or more, putting minimum $21,000 down, and an interest rate of 6.875% and a payment of $3744 per month, more than 3-times his payment.
I have digressed as usual. Yes, today’s “youngsters” do think today’s rates are high—because they are high.
And yes, they do not have the perspective of purchasing property in the 1980’s, when mortgage rates approached 20%, or even the early 1990’s when they climbed as high as 9%. They do not have the perspective, because the likely either were not born, or did not know what interest rates were.
Pat and Blake are 38 and 39 years old, both born in 1984. They have been looking at purchasing a home since 2021.
When they entered the market, they were looking at $750,000 homes with rates at or below 3%, but were in the middle of the pandemic housing frenzy, and their offers with 10% down were swept aside by all-cash offers, or those purchasing well over list price.
As 2022 began, rates began to climb and they were writing offers on homes they were not very excited about, but would get them into homeownership, they wanted to buy before their purchasing power dropped below the prices of the homes they wanted.
Today, they are still looking at homes in the $750,000 range, thankfully Pat’s income has increased and between increased savings, and a small inheritance they can put 20% down.
Starting their home search at 2.5% and now at 6.875% for a home loan, it seems justified that they think rates are high.
But let’s look at it from a historical stand point for those older than Pat and Blake who feel today’s rates are really high.
And for their lifetime they are very high.
From 2005 into 2008, the 30-year fixed rate mortgage was over 5.50% for most of that period, with spikes for short period of times up to and over 6.00%. During this period Pat and Blake went from their last years of college to mid-20s. The interest rates they were concerned about were on their student and car loans. Homeownership was something they would think about later when they were ready to settle down, meet someone to settle down with, have job stability and funds for a down payment.
Since 2008, rates have very rarely hit 5.00%, and rarely spent any significant time over 4.50%. for the most part rates have been around 4.00%.
For these “youngsters,” their post-college, working-life, adulthood, has been in a rate environment 50-60% below current mortgage rates.
For youngster’s, today’s rates are high, very high. And they are right.
By the way, I bought our first home in April 1994 for 175,000, put down $7500 to assume an adjustable-rate mortgage at 11.5% that adjusted a few months later to 12%. Being in the industry, I knew in 12-months I would be able to refinance the property at the current value, instead of the low sales price, to lower and fix the rate. I was happy to do so at 6.5% in June 1995.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
A lot of pressure on rates this week as investors saw several economic reports pointing a rolling economy. Recap, good economy typically means higher rates.
Tuesday’s data releases hit three areas of the economy. Increased orders for durable goods in May from manufacturers, which implies increased production, which means more workers and/or higher wages. New home sales surged in May, indicating that families like Pat and Blake (see above for those who skip to this section of the WR&MU) are not waiting for rates to drop to purchase homes, and strong demand for homeownership. Consumer confidence climbed to its highest level since January 2022, showing decreasing concern for inflation and a possible recession. All this positive economic data in one day put pressure on rates to climb.
Yesterday, two more reports added pressure. First quarter GDP estimate was revised from 1.3% to 2%, showing much stronger growth in the economy that previously thought. The report indicates that the Fed’s rate hike actions are not having the impact it desires to slow the economy and curtail inflation to its 2% target rate. A primary focus for the Fed is labor, if unemployment increases and wages flatten there should be a corresponding drop in inflation. Indicating that the hot labor market appears to not be cooling, initial jobless claims dropped significantly last week, to a four-week low.
Not helping rates, was Fed Chair Jerome Powell and other central bank heads reiterating their commitment to fighting inflation, translating to higher rates. Speaking at a conference in Madrid, Powell made statements that seem to guarantee two more rate hikes this year.
Positive economic news ended the week, at the personal consumption expenditures price index, the inflation gauge preferred by the Fed, had its lowest increase in two years as it increased 3.8% in May. This was in line with expectations, and a positive for interest rates, especially in light of all the positive economic news in the week that shows a very active, and growing, economy that by all economic models should be putting upward pressure on rates.
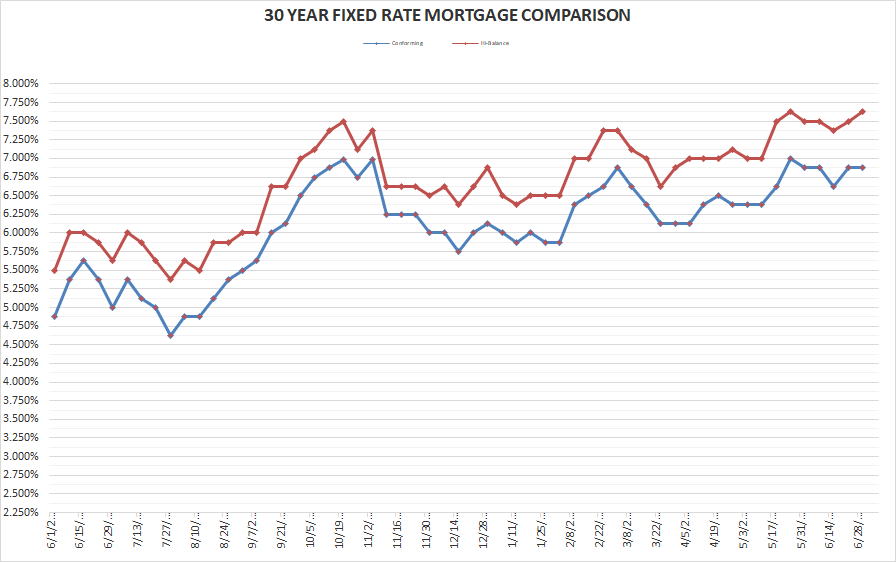
Rates for Friday June 30, 2023 A bouncy week in the bond markets ended the week with conforming rates flat, and a bump in the high-balance rate. It appears we have entered a range of with a top of 7.00% and a bottom of 6.625% for the 30-year rate to bounce between. When will the conforming rate break through the bottom of the range and lead to lower rates?
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.875% Flat
30-year high-balance conforming 7.625% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Looking at the analytics on the Constant Contact website, and see the number of clicks on links in my updates, I am curious as to how many of you who clicked on the bar-top popcorn machine, and how many who clicked on the Academy Museum of Motion Pictures and Grammy Museum have visited or are planning trips.
I am slowly lobbying for the popcorn machine for the self-labelled DC’s Bar & Grill.
Here is one more link for you, which I hope you take the time to click and read. An annual tradition for the WR&MU this time of year as we celebrate our nation’s independence, here is the text of the Declaration of Independence. I enjoy reading this amazing document for the language and word usage, the very strong treasonous language, and the very straight outlining of grievances. The result of the most important debate in our nation’s history, the Declaration was the first major step to not only our independence, but for those in other nations through the decades and centuries striving to achieve the liberties and freedom we are blessed to enjoy.
Have a great week and a fun and safe Independence Day celebration,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


