

What are tax benefits of homeownership?
Question of the week: What are tax benefits of homeownership?
Disclaimer: I am not a tax professional, please consult your tax preparer before filing your taxes to determine deductions, credits or other benefits you may claim.
Answer: As 2022 winds down many of us start filing away folders with our paid bills so we know where to get them on April 14th. As you are filing your 2022 invoices, statements, receipts and bills, you may want to put some of them in a folder labelled: Possible home deductions.
Before we begin on benefits you may accrue on your taxes due to homeownership, let’s cover two important areas of benefits. When filing a tax return there are deductions and credits.
Deductions are a reduction in your taxable income. Credits are a reduction in the taxes you owe.
Deduction: You are married and your combined income is $150,000 in 2022 and have itemized deductions totaling $50,000. Your taxable income is $100,000.
Credit: Based on your adjusted gross income you owe $20,000 in federal income for 2022, you have a tax credit of $7500. You owe $12,500 in federal taxes.
When preparing your taxes, you can either take the standard deduction allowed for all filers ($12,950 for single filers, $25,900 for married filing joint filers), or you can itemize your deductions. If your total deductions are less than the standard deduction, take the standard deduction.
Here are some of the most frequent deductions filed by homeowners:
Discount points If you purchased a home in 2022 you can deduct the points you paid for your mortgage. If you funded a $600,000 purchase loan and paid one point, you can deduct $6000 from your taxable income.
Mortgage interest If your mortgage was funded before December 15, 2017, you can deduct mortgage interest on mortgages up to $1 million on your primary residence. Due to the Tax Cuts and Jobs Act of 2017 (TCJA), the mortgage interest deduction for loans funded after that date is limited to interest on mortgages up to $750,000. Note these amounts are for joint filers, for single filers the maximum loan limits for interest deductibility are half the amount—a financial incentive to get married!
Property taxes Depending on the amount you pay in other taxes, some, all, or none of your property taxes may be deducted. One of the provisions in the TCJA was to limit “SALT” (State And Local Taxes) deductions to a total of $10,000. State and local income taxes, property taxes comprise the SALT provision. If your state income taxes are $10,500 and your property taxes are $8000, prior to the TCJA your deduction would be $18,500, today the deduction is the $10,000 limit.
Home office expenses If you are self-employed, you can deduct the pro-rated expenses for a home office. The easiest way to claim the deduction is $5 per square foot of home office space up to 300 square feet, if your expenses are higher than this calculation a more detailed filing may be appropriate.
Energy efficiency There are several deductions and credits available for energy efficient improvements to your home. Some of the eligible improvements are installing electric car charging stations, solar energy systems, solar water heating, energy efficient water heaters or furnaces, improvements that reduce energy consumption such as insulation, roofing, or replacing windows.
Some of the credits are limited based on what credits you have received in the past. Starting in 2023 the Inflation Reduction Act the lifetime credit will go away and there will be a $1500 annual credit available.
HELOC interest If your Home Equity Line of Credit was used to buy, build, or substantially improve your home you can claim the interest, to the limits listed above. If you used your HELOC for business purposes, including an investment property listed on your returns, check with your tax preparer about ability to deduct the interest paid and if subject to the home mortgage interest limits.
Reduction in capital gains taxes If you bought a stock for $350,000 in 2010 and sold it in 2022 for $600,000, you will likely have to pay long-term capital gains on the $250,000. If the same scenario occurs with the purchase and sale of your primary residence, you may not have to pay any capital gains due to two primary provisions in the tax code.
If you have lived in the home for two of the prior five years before selling, you can exclude $500,000 in gains if married joint filer and $250,000 if single filer. Under current tax law this exclusion can be used as many times as long as you qualify otherwise—meaning the purchase and sale of multiple homes through your lifetime. It is also important to note the living in the property two out of five years stipulation, I have had clients who over a period of time changed their residences to different income properties they have owned to reduce their capital gains liabilities.
Capital gains for primary residences are not calculated by subtracting the purchase price from the sales price. The gain calculation deducts acquisition costs, costs to sell, and improvements made to the property. This is a “double dip” advantage as you can take advantage of the credits for improving your home for energy efficiency in the year of the improvements, and then deduct the cost of those improvements when you sell the property to reduce, or eliminate, capital gains.
Improvements for medical needs If medical expenses are greater than 7.5% of your income, the are deductible. That can be a high-bar for many families, consider the $150,000 income earning couple above, they can deduct any medical expenses that exceed $11,250. If you make any home improvements that are due to medical conditions, the cost of these improvements can be included in deductions for medical expenses. Installing safety bars, ramps, doorways expanded to enable wheelchair access, lifts, railings, are some of the costs that can be included in medical expenses for your tax filing.
Note what payments and expenses are not included in the list of tax deductions and credits for your primary residence. The portion of mortgage payments that go to principal, homeowner’s insurance, homeowner association dues, utilities, none of these expenses for your primary residence are deductible.
As noted above, I am not a qualified tax professional, CPA, or tax preparer. Before filing your taxes consult a tax professional to ensure you are availing yourself of all available deductions, and not claiming deductions for which you do not qualify.
If you, or someone you know, would like to have deductions for homeownership, please contact me to determine how much of a home you can purchase.
Have a question? Ask me!
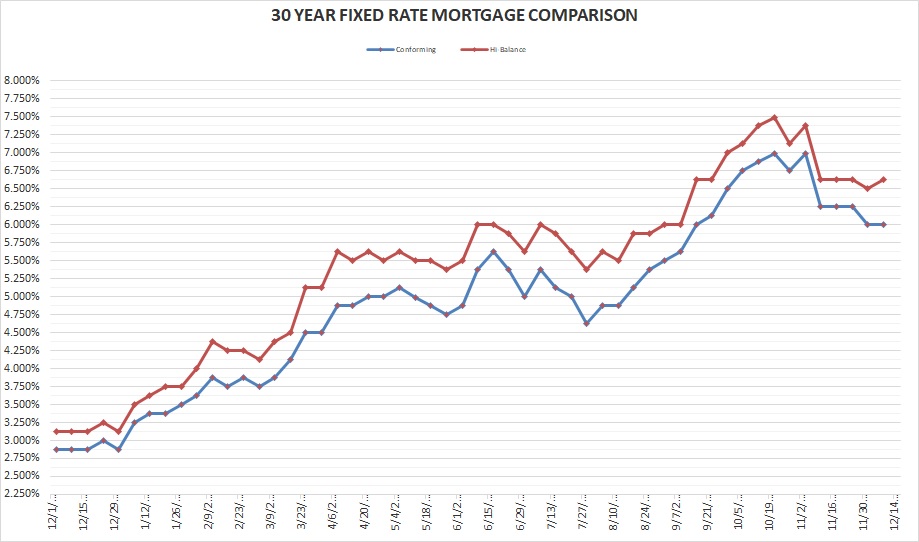
Rates for Friday December 9, 2022: Not a lot of economic data this week to impact mortgage rates. Conforming rate is flat from last week and the high-balance rate up a bit.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.00% Flat
30-year high-balance conforming 6.625% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
In this age where transparency is so important, I admit to having some less than productive hours the past few weeks due to technology. The ability to have a small window in the upper corner of one of my two computer screens streaming World Cup Soccer games live each day is the technological productivity reducer. I am not an every-four-years-for-the-World-Cup soccer viewer. I have followed Tottenham in the English Premier League for years, my high school soccer coach played for them in the sixties, and keep track of international matches and other leagues.
We have no comparable to the World Cup in the United States. Yes, we have a national team, but it is not a national game. There is no sport that generates the passion and interest on a national scale that comes close to what the World Cup means to other nations.
If you are not a soccer fan, I wish you were to enjoy the excitement of this international contest with great
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


