

Who do you know?
CORRECTION: In last week’s WR&MU I indicated the federal tax credit for residential solar installation would drop to 22% in 2023 and go away in 2024. Avid WR&MU reader Dennis (no relation) Boone let me know that included in the Inflation Reduction Act of 2022 was an increase and extension of the Residential Clean Energy Credit for solar installation, increasing the credit to 30% of the cost and extending the credit to 2032. Thanks Dennis!
Question of the week: Who do you know?
Answer: With today being Veteran’s Day and many off work, this week’s question is more about you than about mortgages and real estate.
Having been in the mortgage industry for over 35 years I have acquired a large Rolodex (for the younger WR&MU readers, it was the “contact app” for decades, perhaps centuries) of professionals across many professions and services who I know to do a great job for clients.
Some of the most important people I know are attorneys, specifically those who specialize in trusts and estates, and family law. In July 2019 our Question of the Week was “Do you have a will and a trust?” that covers why it is important to have wills and trusts, and that you work with a professional to prepare them and not a bargain website.
Family law, unfortunately, is an area where I am asked for referrals as all relationships do not always work out. Even when a separation is amicable, it is wise to have a professional work with both parties to ensure all the legal aspects are followed and to assist in completing the paperwork required.
When you own a home, or have a family, it is important that it is protected should something happen to one spouse or partner or the other. By “protected” I mean have insurance that can cover payments and expenses to replace the loss income that was depended upon to make mortgage, tax, insurance, and other payments. A licensed life insurance professional can assist you with the right policy and coverage for your needs.
Like myself, my client base is aging. What comes with age are various ailments and health issues. Some are more debilitating than others, and the older we get the more costly some of these can be. Protection for the family assets can be had in the form of long-term care insurance, and the younger you are when you obtain coverage the lower the cost. Yes, I know professionals who can walk you through options and help determine whether it is something that might be a benefit and if so various policy options.
Our tax codes do not get simpler regardless of which party controls the tax codes. Whether for yourself as an individual or couple, or if you have a small or medium sized business, I can refer professional CPAs and tax preparers to assist you in tax planning and preparation.
Financial advice and planning is an area where too many people wait too long before engaging professional assistance to plan for when your income goes from end of career heights to social security and retirement funds.
Speaking of social security, what about Medicare and your mandatory enrollment at age 65. What plan, what supplemental coverages, are best for you?
Beyond professionals who work in law, insurance, and financial service areas, I have connections other services you may need, from installing solar or HVAC systems, to putting in a swimming pool.
And of course, quality real estate agents for many areas of the state who treat their clients as if they are family.
Best of all with my network, if I do not have a contact for what you may need, my contacts likely do know someone they know and trust to refer.
Google and Yelp are great resources to find a place to eat lunch while in
Charleston, South Carolina, or meeting your daughter and friends for dinner between your midtown hotel and their apartment in East Harlem, but not as great for engaging a professional service that is for protecting your home, family and health, or working on your most valued asset—your home.
Please contact me if I can be a resource for you, you know a guy who…knows a lot of guys and gals who do great work!
By the way, if you are travelling and looking for some restaurant ideas, I have quite a few on my Yelp profile!
Have a question? Ask me!
If you had told me a year ago that a Consumer Price Index report showing 7.7% inflation would be celebrated, I would have given you a very funny look. But that’s what happened yesterday when the Commerce Department released CPI data showing prices increased 0.4% in October, below the consensus estimate of 0.6%. The 7.7% year over year price increase was a half-percent drop from September’s 8.2% CPI increase, and the lowest amount since January.
Investors reacted positively to the large decline in price increases, and particularly the 0.3% increase for the month, 6.3% from 2021, of the “core” rate, which has energy and food stripped from the price index. This is the data the Fed looks at when making policy as it is more stable due to volatility in food and energy prices.
Markets reacted very positively to the data, however…let’s not pop the corks on all the bottles just yet. As most of the country heads into colder weather and higher energy consumption, there are several items in the report that cause trepidation to announcing inflation is falling to an extent that it will be in a “normal” range sooner than later.
Grocery prices were up 0.4% for the month and 12.4% for the year, the highest increase since 1979. Interestingly the cost to eat at home has been increasing at a higher rate than the cost of eating out, up, 8.6% for the year, and has been since last October. Restauranteurs have been struggling to hold the line against higher food, beverage, energy and most importantly wage increases.
Gasoline, after dropping in prior months, leapt 4% for the month and up 17.5% from 2021. For home heating, electricity prices were up 14% and home heating gas up 20% compared to last October.
On the housing line, rents are up .7% for the month and 7.5% annually, the largest increase since 1982. On the positive side of dropping prices are used cars, medical expenses, closing, house wares, and airline tickets.
Inflation may be slowing, but wages are still not catching up, with inflation adjusted wages down 2.3% from last October, putting pressure on households to refrain from running up credit or cutting heavily into savings. The news will not stop the Fed from increasing rates, however it may offer some cover to slow the pace of the increases.
One final note, the cost to relax and get-away from news, inflation, election dissection, your team losing in the playoffs, or winning, alcohol prices are up 5% for the past year, the highest increase since 1992.
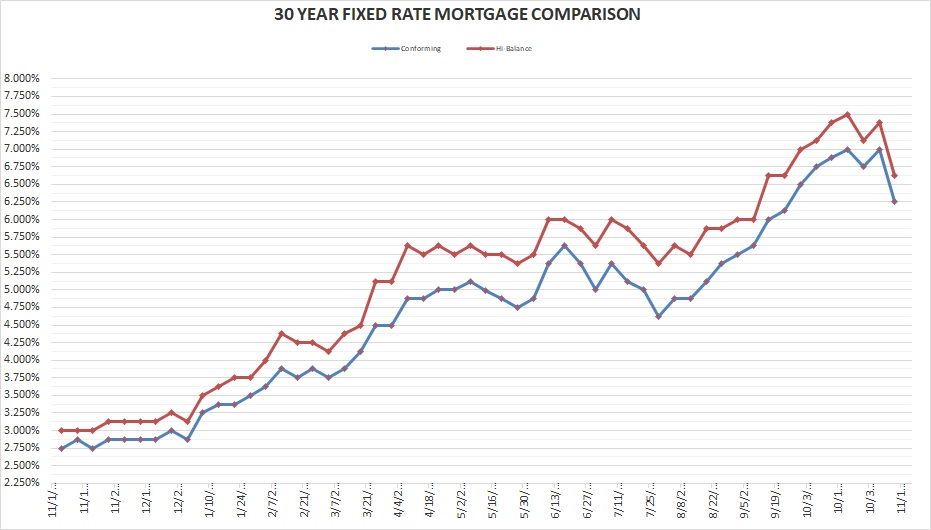
Rates for Friday November 11, 2022: The CPI news had an instant reaction in the markets, and mortgage rates benefited. The drop in rates from last Friday is the largest since the final week of March 2020 as rates dropped following a 0.875% increase in two weeks in reaction to the shutting down of the economy for the pandemic.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.25% Down 0.74%
30-year high-balance conforming 6.625% Down 0.75%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
From the call to volunteers in April 1775 to protect the cache of arms that had been amassed by militiamen in Concord, Massachusetts, through too many wars, to today, men and women have stepped up to put themselves between those who wish to attack our country, our allies, and our citizens. No amount of gratitude can be properly stated to convey what we owe these brave men and women. Thank you.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


