

Can I get a mortgage if I change jobs?
Question of the week: Can I purchase or refinance if I changed jobs?**
Answer: Yes, maybe, no…our most common question of the week answer applies this week. We will answer the question in this order.
Yes, you can purchase a new home, or refinance a current one, if you have changed jobs in many—most?—circumstances.
YES…
It is estimated that 80-85% of American workers are W2 employees; i.e. they are paid on an hourly or salaried basis.
If you are changing jobs in the same industry, or generally same line of work or employment, the job change should not be a hinderance to your ability to qualify for a loan. Note, “job change,” not “income change;” if your new job will pay less, it will impact they amount you may qualify for with your new mortgage.
Francine has been a registered nurse for six years and has worked at ABC medical clinic in Long Beach for the entirety of her career, where she makes $50 per hour. She wants to move to the Central Coast to be closer to her family, as well because home prices are lower.
She finds a job in San Luis Obispo that will pay $40 per hour, a twenty-percent cut in pay, however there are plenty of housing options for her in the $400-450,000 price range.
Her job starts in March, she enters a contract to purchase a $425,000 home in mid-February and we close escrow towards the end of March.
Even though she took a pay cut to move, she has a job in the same field, a contract from her new employer, and by the time we close she will have received a paycheck showing her pay. All of these factors enable her to qualify for a home loan.
What if I am not W2 but receive a form 1099 for my income, I work on commission or on contracts?
Roderick has worked in the tech industry for many years. He has contracts with several companies to maintain their computers, repairing, installing new software and updates, making fixes after Bill clicks on the “your password is expiring” link. His gross income is $150,000 per year, he has some deductions on his IRS Schedule C that brings his taxable income to $110,000 per year; which is the amount we would use for his qualifying income.
He recently was hired by one of his clients that is expanding their business and wants Roderick to be their in-house CIO (Chief Information Officer), and are giving him a salary of $125,000 per year.
Roderick’s new qualifying income is $125,000 per year that is paid as salary. Like Francine, a contract and a paystub would be the necessary documentation for closing using that income.
Moving from W2-to-W2 income, or from 1099 to W2, is usually not an issue for mortgage qualifying.
Maybe…
Instead of moving from one nursing job to another, Francine takes a job in the Central Coast managing the tasting room and gift shop for a winery and has a contract of employment.
Underwriting will scrutinize this transition a lot more than moving from nursing to nursing. The contract is a huge factor, as will be the paystub(s), however what experience does she have in the wine, or retail industries? Management?
Francine’s tenure at her prior job included staff management, making shift assignments, ensuring supplies were on hand to treat patients, in addition to her duties as a nurse. She writes a strong letter of her duties on her prior job and the similarities between her new job—which were sufficient to be hired. As well, her current and new employers provided letters supporting her experience and duties. Underwriting approves the mortgage.
Roderick, instead of going to work for one of his clients, wants to move out of the area. He works in the Sacramento and wants to move to San Diego.
Underwriting is concerned due to his clients being in Northern California and his move to San Diego, this could result in a drop in income. Roderick writes a letter stating that most of his work is done remotely, rarely visiting his clients. If a major issue comes up, he can easily travel to the client for a few days to solve the issue. He asks his clients to write letters stating that he works remotely for the vast majority of his service with them. The underwriter has concerns about increased expenses for travel to Northern California when the need arises.
Roderick has already been traveling back and forth as he determines where he would like to live in San Diego and produces a contract with a new client in Oceanside that allays the underwriter’s travel expense concern.
No…or extremely difficult…
Francine has exponential growth in her followers on her “Home remedies” internet presence. She has slowly been increasing sponsors and advertisers on her various feeds and decides to quit her job and pursue being an social media influencer full-time.
Even though she is in the same industry, underwriting will use the income on her tax returns from the on-line income to determine qualifying. Since she is in the process of building the income, Francine will need to wait until she can show sufficient annual income to support a mortgage and other obligations.
Roderick works as an in-house CIO. Over the years he has made many contacts at other companies through his work, going to industry conventions and association events. He is recruited constantly but has remained declined offers.
Finally, with encouragement from his wife, he leaves his company and starts his own business as an external-CIO for hire on a retainer plus costs basis. His first client is his existing company, and after several months has signed up more clients.
After his first year his taxable income is almost the same as his salary from his prior employment. Underwriting is concerned because they do not have two-years tax returns showing his revenue and expenses. Roderick’s CPA writes a letter breaking down his expenses, shows they are very stable and tied to percentage of revenue. Roderick provides copies of his contracts showing they are in place for the coming year, and several are multi-year contracts.
Based on his experience in the industry, and Roderick’s ability to quickly build revenue to match his prior W2 income, after expenses, underwriting approves his income.
Or income calculation is…
The scenarios above are based on standard mortgage income qualifying. There are mortgage products out there that use other methods to calculate income, such as asset depletion (calculate income based on amount of liquid assets available in investment and retirement accounts), or using deposits in bank accounts over a period of time.
As an industry, we try to get to “how” when it appears the answer maybe “no;” so if the answer is “no you don’t qualify” it can be worth explaining other options to see if there is a “how” available.
Have a question? Ask me!
Want to schedule and appointment? Click Here
There were uncertainty and choppiness in the job market in 2025, not a lot of jobs were added by businesses, but not a lot of people were laid off. Following ambiguous year for businesses hiring and firing patterns, the report for January is a good way to start the year. The economy added 130,000 new jobs, much higher than 55,000 expected, and the most in 13-months, despite winter storms through much of nation. As well, unemployment drops for second month in a row, from 4.4% to 4.3%. The data reinforces the view that the Federal Reserve will not be changing its benchmark interest rate in the near future as it appears the labor market has stabilized.
More good economic data was released this morning showing that an important measure of inflation shows price increases slowed to a five-year low. In January the consumer price index increased 0.2% and annual inflation slowed from 2.7% at the end of the year to 2.4% to start the year. Stripping out gas and food, the core rate increased 0.3%, slightly up from December, and the annualized rate dropped from 2.6% in December to 2.5% in January.
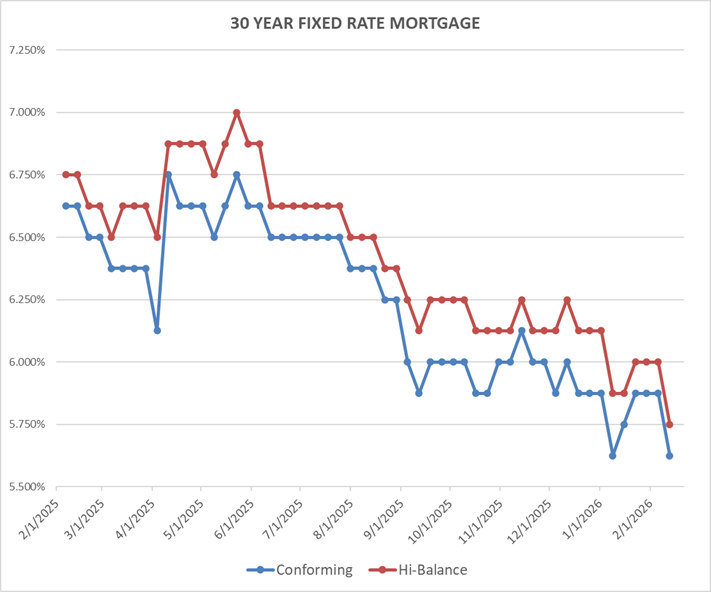
Rates for Friday February 13, 2026: Investors liked the news this week, and not needing to guess what the Fed might due as improving inflation and jobs are what are desired. Rates drop from last Friday, and for the second time this year are only 0.125% the 3-year low, briefly reached in September 2024.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 5.625% Down 0.25%
30-year high-balance conforming 5.75% Down 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
**Our question of the week arose from Leslie’s recent work in putting together a summit for those looking for “what’s next” that may involve a change in careers, and income.
Over the years I have been solicited by many companies to include their product or service in the WR&MU. I have declined them all. Until now…
If you’re interested in starting something new in retirement, or just something new in general, you might be wondering what options match your interests and let you transfer your skills and wisdom to build something new that brings you joy.
My wife Leslie is hosting the Second Act Business Summit on March 2-7, 2026. In a virtual format, you can watch up to six half-hour segments each day from experts who consult specifically on business options and creative endeavors that might interest you, tools and systems you need to build a thriving business, and the coaching and supports you need to maximize your potential. Each speaker offers a free gift.
The event is 100% virtual allowing you to watch it as your own pace, and the best part is it’s Free! Check it out by clicking here. Checkout the VIP package that she’s offering for a mere $27.


