

The balances are not correct on our credit report
Question of the week: The balances are not correct on our credit report.
Answer: Okay, okay, it’s not a question, but the format is the format. This is a follow up on our prior two WR&MU in which we covered whether you should get new credit before applying for a mortgage to purchase or refinance your home, and a follow up regarding getting new credit while you are in escrow for your new home purchase or refinance.
This statement under “question of the week” is fairly frequent from clients after we send them a copy of their credit report.
You receive a copy of your credit report and see a $1200 balance on your Chase Visa, a $350 balance on your Home Depot MasterCard, and a $25,000 balance on an equity line that was paid off when you sold an vacation property two months ago.
You contact me and let me know that you have paid off the credit cards, and of course they equity line is paid and closed.
Why does this happen?
Credit companies report to the credit bureaus on the date of your monthly statement. You went to Vegas for your anniversary weekend and charged $1200 on your Chase card, then the next weekend you went to Home Depot and charged $350 to complete the honey-I-will-do list you gave your spouse as an anniversary gift (they get more exciting the longer you have been married…).
Your credit statement is issued on the 10th of the month, you paid off both cards on the 15th of the month, we ran your credit report on the 25th of the month. On the 10th Chase and Home Depot reported the balances to all three credit bureaus (Experian, TransUnion, Equifax), and they will on the 10th of next month. If you have not used your credit cards between the statement dates, because you paid them off, if we pulled credit on the 11th of the next month both accounts would show zero balance.
Does it matter that your credit report shows balances on credit card accounts you have paid off? Probably not, but maybe.
It may matter if, as mentioned in the WR&MU regarding obtaining credit before you apply for a loan, depending on the credit balance on the report and what percentage it is of your available credit, your credit score may be impacted. As well, depending on your debt-to-income ratios, the minimum payment required on these balances may put you in jeopardy of qualifying. Since minimum payments on most credit cards are 2% of the outstanding balance, the minimum payments on the Chase and Home Depot cards would be $24 and $7 respectively. In most cases this would not endanger your ability to qualify.
What about the equity line that was paid off?
This could present a bigger problem as it raises a potential red flag that you own other property that is not disclosed on the mortgage application, as well depending on the minimum payment your qualifying ratios may be in jeopardy.
This is an easy problem to solve. By providing a copy of the closing statement from the vacation property sale escrow to our credit company, we can have them update your report to show the credit line is paid in full, with no balance and no payment.
If there are errors on a credit report, with proper documentation, i.e., a statement or transaction record from the creditor, we can work with the company we use for our credit reports to correct anything in error.
Regarding “our credit company.” We contract with a third-party company that is recognized and accepted by the mortgage industry, including Fannie Mae, Freddie Mac, FHA, lenders, etc, to provide “tri-merge” credit reports and scores. “Tri-merge” is the fancy lingo for a credit report that merges the reports from the three major credit bureaus into one report.
Besides history, balance and payment details for each open, and closed within the past seven years, from creditors, the reports also list recent inquiries, any public records such as tax liens or judgments, employment history as reported by creditors, and address history, again as reported by creditors.
Have a question? Ask me!
Retails sales continue to increase. According to reports this week consumers continue to ring cash registers as retail sales in October were up 1.7% from September. Very good news for the economy, but…as reported a few weeks ago in the WR&MU, inflation spiked in October, which accounts for about half of the increase in retail sales; this is because the sales are based on unadjusted dollars of sales.
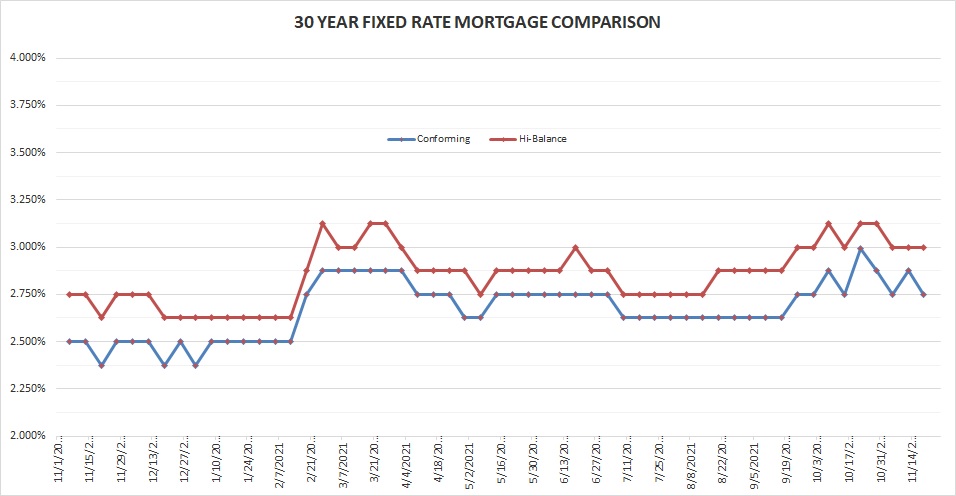
Rates for Friday November 19, 2021: Rates continue to have small fluctuations week to week as investors sort through economic data and prospects for higher rates, impact of inflation, Fed moves and budgets in Washington. The conforming rate slips down after last week’s bump.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 2.75% Down 0.125%
30 year high-balance conforming 3.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
This will be a record setting Thanksgiving in the Smith household, the fewest we have had.
Every year for the past few decades we have hosted Thanksgiving dinner. It is my favorite holiday and enjoy spending the day prepping, cooking, baking, cleaning (I think cleaning pots, pans and dishes as you go is about 50% of the time spent in the Thanksgiving kitchen) for our dinner with family and friends. Our table varies from about seven or eight to twelve or fourteen.
This year with our daughters and nieces away from home, Leslie’s dad having passed away in January, we find ourselves with an intimate table of four as Leslie’s sister and brother in-law join us.
I’m glad we have a 20-pound turkey so there is just a small chance we won’t have enough…The biggest challenge is how to cut down on the recipes for the side dishes!
Happy Thanksgiving everyone,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


