

Is it easier for the self-employed to get a mortgage?
Question of the week: Is it easier for the self-employed to get a mortgage?
Answer: Somewhat, but there is still a lot of documents needed for self-employed income to be qualified for the application.
After the social and economic shutdowns in March 2020 due to the rapid spread of the Covid-19 coronavirus, guidelines for qualifying income became stricter for all applicants.
For wage earners, those who receive a W2 at the end of the year, the new guidelines required verbal verifications of employment from employers on the date of funding, and attestations from applicants that there had been no change in their income or employment status since they signed their application.
For self-employed applicants the requirements, besides most recent tax returns filed, included a year-to-date profit and loss statement to the end of the month prior to the application date and three to five months’ bank statements for the business supporting the income on the P&L. Before funding another P&L to end of the month prior to funding and additional bank statements to that date of the new P&L.
For applicants using rental income for qualifying the same guidelines required for self-employed borrowers were in effect to show that rents were being paid and collected during the pandemic.
Earlier this month Fannie Mae and Freddie Mac (GSE) announced they removed prior Covid policies for income verification and qualification, however for self-employed borrowers the requirements, even though rolled back to pre-Covid, still require several levels of verification documents.
Here are the new guidelines for self-employed applicants as of February 2, 2022:
- Self-employed income will be based on income tax returns no older than 2020
- Year to date profit and loss statement within 60-days of closing, and three most recent month bank statements
- Verification business is still in existence within 20-days of closing as evidenced by
- Current work contracts or invoices
- Current business receipts
- Verification through phone call or other means the business is open
- Business website demonstrating activity supporting current operations, such as making appointments for services
Recent bank statements showing deposits for the business within 20-days of closing should suffice to show an active business in most instances.
In the guidelines is the statement that lenders must determine, using the documentation provided from above, the extent to which a business is still being impacted by Covid-19.
For self-employed borrowers, if you have filed your 2021 tax returns you will need to provide them with your application. If you are closing after April 15th, you will either need to provide your 2021 returns, or a copy of the extension you filed indicating your returns will be filed later in the year.
When clients grumble about the amount of documentation they need to provide to obtain a mortgage, I remind them they are borrowing a very large sum of money. Often highly leveraged, i.e. less than 40% or more equity. The person making the decision to approve the loan does not know you, will never meet you, and can only make the decision based on evidence showing a very clear indication of your income and its likeliness to continue.
Have a question? Ask me!
Don’t look for inflation to cool down in the near future. The Producer Price Index, the cost of wholesale supplies (i.e. what companies pay before passing along to consumers), for January was released on Tuesday and it showed a 1% increase for the month, and 9.8% increase from January 2021. If companies are paying 1% more for their supplies, how much more will the consumer pay for the goods and services they pay? Until the PPI slows its growth we cannot expect to see a slow down in inflation for consumers.
After slumping in December, retail sales surged in January. Earlier this week the Department of Commerce reported retail sales were up 3.8% in January, in the same report the DOC revised December sales to show they dropped 2.5% from November. The drop in December is good context to understand the January increase, reflecting an increase of 1.3% from November to January in sales. Further impact on the retail sales data is that prices increased 0.6% in January, absent inflation sales increased 3.2% for the month. Carrying the data further the 1.3% increase in sales from November, absent inflation, is 0.3% (prices increased 0.4% in December). While more dollars are being rung up at the cash registers, not that many more units are being purchased.
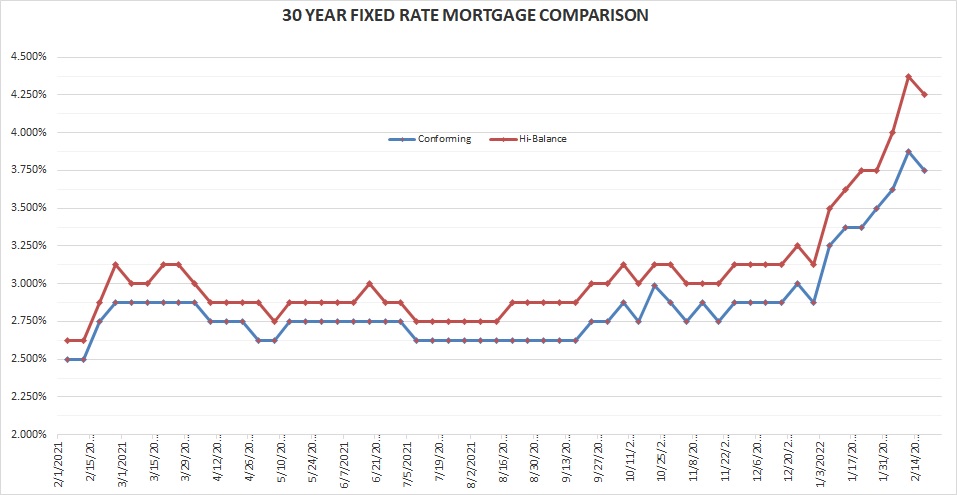
Rates for Friday February 18, 2022: Rates slip back down from last Friday as investors move their money from stocks to bonds and mortgages on concerns of the Russia-Ukraine situation escalating. While we have a dip this week, the overall trend for the near, mid?, long?, will likely but up for rates with the Fed getting more assertive in it messages regarding raising rates to stifle inflation.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 3.75% Down 0.125%
30 year high-balance conforming 4.25% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Congratulations to the Los Angeles Rams, their families, friends and fans for winning the Super Bowl. Last year was the first year that a team played the Super Bowl in its home stadium, and the Tampa Bay Buccaneers won the trophy. Last week there was a repeat with a team playing and winning the Super Bowl in its own stadium.
For those who are of a gambling nature and believe in trends, the Arizona Cardinals are currently 2500 to 1 to win Super Bowl LVII (57 in non-pretentious format) being played in their stadium next February; a $10 bet returns $25,000 if the Cardinals follow the Buccaneer and Rams with a Super Bowl victory.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


