

How much more is it to buy a home this year from last?
Question of the week: How much more is it to buy a home this year from last?
Answer: Using the most current sales data from the California Association of Realtors, sales from March of this year, and comparing to March of last year, prices and number of sales are up statewide, up and down in Los Angeles County, and up in both categories in Orange County.
The median price statewide is up 3.5% for the year, up 3.7% in LA County, and 3.6% in Orange County. While statewide prices are up from February to March this year (6.7%); they are down month-to-month in Los Angeles (-2.7%) and Orange Counties (-1.1%).
Year-to-year total sales volume rose statewide (4.9%) and in Orange County (5.4%), but dropped in Los Angeles (-3.7%).
How does this translate your cost to buy a home?
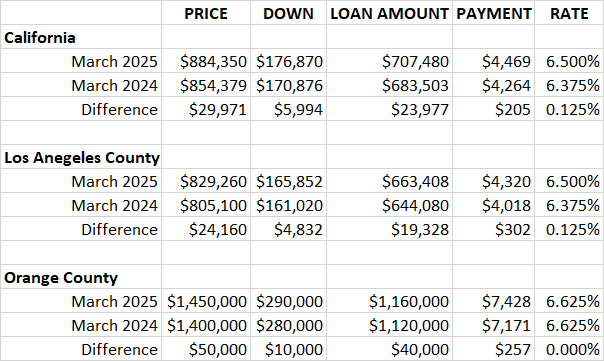
As you can see below, prices from last year led to higher down payments, higher loan amounts, and higher monthly payments*.
Higher mortgage payments were less than in the prior years due to the conforming rate going up only 0.125% from the last Friday in March 2024.
Overall, the increase in down payment and monthly payments is considerably less than the increases in these areas we have seen for the past several years.
*Payments are calculated on the rates on the last Friday of the month using the same criteria we have used for our Friday rates for more than a decade, 20% down payment, 740 credit score (higher score results in lower rate), cost of 1.25 points for an owner-occupied single-family residence.
With the uncertainty still prevalent in all markets forecasting the housing and mortgage markets is near impossible. Is economy heading into a recession? Will rates go up to try to stifle inflation rising again? Will labor markets turn down resulting in layoffs and less buyer demand? One can read analysts from several different outlets or think tanks and get several different predictions.
I continue to provide the same advice to clients asking, “is now a good time to buy our new home?”
“Can you afford the home, is the payment within your comfort range, is the house you want on the market? If so buy it.”
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Markets reacted positively to the Federal Reserves announcement it was not moving its benchmark interest rate. In comments after the announcement Fed Chair Jerome Powell warned of economic challenges are on the horizon with higher risks of unemployment and inflation. One would traditionally push rates down (higher unemployment), the other push rates up. If both were to occur, we are likely in a period of stagflation. Historically, rates go up when the economy is in stagflation.
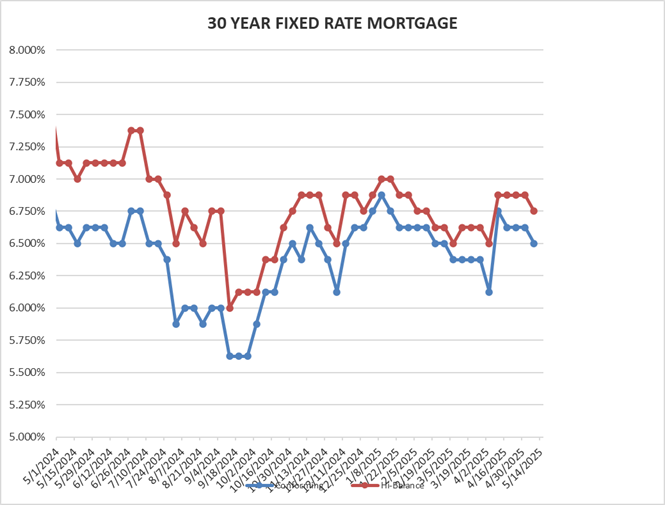
Rates for Friday May 9, 2025: Rates dip week to week for the first time since mid-April.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Down 0.125%
30-year high-balance conforming 6.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
May, the month of celebrations with Mother’s Day and graduations for those completing high schools and colleges. We celebrate both this month as our youngest, who completed her course work for her degree from Pace University in New York City in December has her ceremonies coming up.
We will be travelling to the Big Apple for the Big Walk across the stage, as such no WR&MU next week.


