


Does my insurance policy cover my home if it is damaged due to civil unrest?
Question of the week: Does my insurance policy cover my home if it is damaged due to civil unrest?
Answer: The answer is the same as many answers to the question of the week: yes, no, maybe.
I asked this question to two friends of mine, Eric Lenahan and Todd Caviliglia, who are agents with State Farm and Allstate respectively. Their answers resulted in the answer above.
Some carriers have written in their homeowners’ policies coverage for “civil commotion or riot” that result in “pillaging, looting, vandalism, damage…” These policies also cover your personal property if it is damaged, lost or stolen at the “scene of civil commotion or riot.” In other words, if you are filming such activity with your video camera and it is grabbed and smashed, it would be covered if your policy has this coverage.
Some carriers have written in their homeowners’ policies exclusions that specifically state that damage, loss from looting (or pillaging), as a result of civil unrest or rioting are not covered by the policy. If a policy has this exclusion and you want the coverage it may be found through a broker who can find a policy specifically covering civil unrest damages and claims.
What if you live in a condominium? There is a greater likelihood of a condominium complex, or individual unit, in a city sustaining damage due to civil unrest than a single-family home in the suburbs. Condos are interesting because most units have two policies. A master policy covers the homeowners’ association and all the common grounds and structure owned by all the owners. For example, the exterior walls, fencing, garages, the roof. An individual policy owned by the owner of a unit in the complex will cover the personal property of the homeowner, and cover furnishings and coverings in the unit. For instance, the individual policy will cover the replacement of kitchen cupboards, appliances and other damage to the interior of the unit if there is a kitchen fire.
What if the condo complex has damage to the lobby, vandalism on walls and broken lights in common areas due to a civil disturbance? What if the ground floor of the building is commercial space and there is damage to those spaces, as well a fire is started that damages units above the ground floor? What is covered by the master policy? What is covered by the individual policy?
Eric and Todd both stressed that it is important that homeowners know what their policies cover and what they exclude. As Eric said, the policies are written by attorneys and the language can be very difficult for many lay-people to understand as to wherefor is covered except when who-fore acts in certain ways unless what-for condition is in existence.
If you are concerned if you home is covered should it be damaged, looted or otherwise harmed as a result of civil unrest it is highly recommended you read your policy and also go through the coverages with your agent or broker. Not all policies are the same, know what your policy covers.
It is my hope that none of the readers of the WR&MU will need to file any claims on the homeowner policies for any reason, but if you do need to file one that you are aware of what is and is not covered.
Have a question? Ask me!
<Insert shocked face here.> A shocked face is the reaction of almost everyone when the employment data for May was released today which showed 2.5 million jobs were filled for the month. Expectations were for the economy to shed 7.25 million jobs in May. The re-opening of the economy in states across the country fueled the surge in employment as workers returned to jobs. Bars and restaurants, the first and hardest hit of all industries, recalled 1.4 million workers in May, out of over 6 million servers, bussers, cooks and other workers who lost their jobs in March and April. Construction jobs saw 464,000 return to work, retail increased payrolls by 368,000 and 225,000 returned to jobs in the manufacturing sector. After record job losses in April, the healthcare industry brought back 312,000 workers.
It seems odd that this is good news, average hourly wages declined in May. Why is this good news? As mentioned last month, April saw a spike in average earnings as the overwhelming jobs lost were to lower wage earners. With the return of workers in bars, restaurants, retail and other industries that have a lot of lower-wage workers the average wages naturally decline due to math.
Economists and data geeks like myself are expecting another surge in jobs in August after the CARE Act benefits for unemployment insurance expire in July. With unemployment payments being boosted $600 per week due to the CARE act, the Congressional Budget Office estimates that five in six with unemployment claims are earning more money from unemployment benefits than they did from their jobs. Once it becomes more financially beneficial to go back to work many workers collecting the additional income will look to get off the unemployment program and back in the workforce.
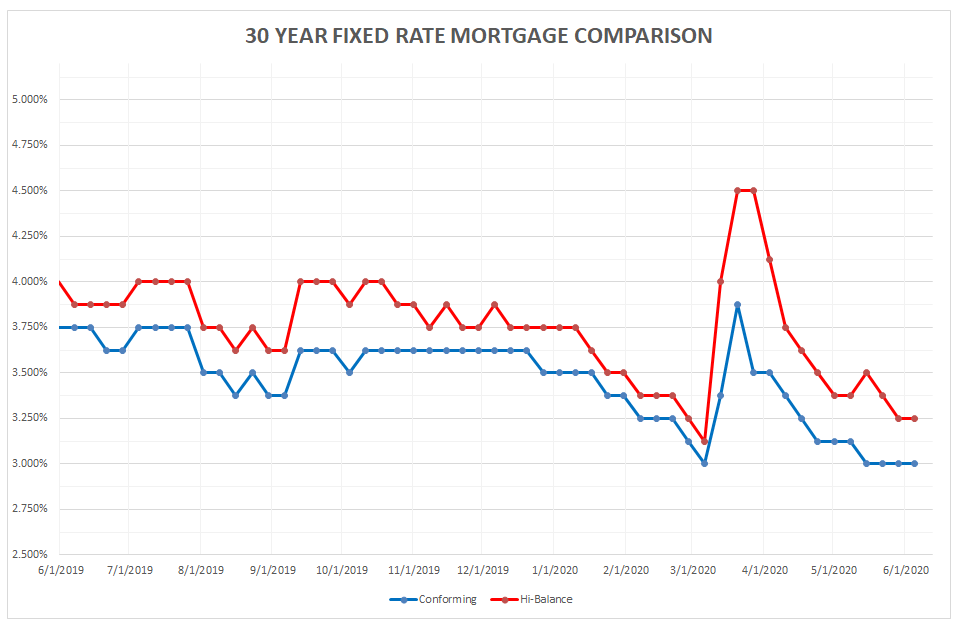
Rates for Friday June 5, 2020: Rates softened a bit earlier in the week as tensions between China and the U.S. ramped up again. As the week progressed, tensions eased a bit and with the employment report today bonds lost some ground as money moved into stocks. The result is rates today are flat from last Friday—good news as stability is slowly returning. We are still seeing large disconnect in the high-balance market from purchases and refinances. Call for details and quotes.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.00% Flat
30 year high-balance conforming 3.25% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
“A wise old owl lived in an oak. The more he saw the less he spoke. The less he spoke the more he heard. Why can’t we all be like that wise old bird?”
In our home in Pennsylvania we had a large wall hanging by our kitchen. It had a branch and four or five owls (I think five since there were five in our family), that depicted father, mother and children, all made out of brass or copper and painted. The saying above was written on the background.
Every day for years we would read about the wise old owl. It was invoked many times by our parents, and later us kids. All that would need be said, “A wise old owl…” and the meaning was clear, ssshhhhh, listen!
For the past several years it has become apparent that there are not many wise old owls on most social media. This past week it has become apparent that there are not as many wise old owls in our neighborhoods, communities, cities and nation. It seems few are willing to be silent and listen to what others have to say. A cacophony of voices, some shouts, some whispers, not speaking with others but telling others what they think the other must believe results in people not listening but reacting.
Turbulent times need wise old owls. We need listeners. When you are heard you are understood, when you are understood and are in turn willing to listen then I am heard and understood. Once we understand each other we can talk. Once we talk, we have removed barriers for solutions to problems.
I don’t need you to agree with me, but I would like you to make the effort to understand. Understanding why I think or feel does not mean you agree with me, it means you care about what I think or feel. If you care about me, and I care about you, we can both be wise old owls and work together.
Try to be a wise old owl, I know I am trying to be one.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


