

Is the Federal government making buying a home more expensive?
Question of the week: Is the Federal government making buying a home more expensive?
Answer: Yes. For many homebuyers the cost of obtaining a mortgage will go up later this year due to new fees imposed on Fannie Mae and Freddie Mac by the Federal Housing Finance Agency (FHFA).
The mission statement of the FHFA as revised in October 2022 states, “Our mission is to ensure that Fannie Mae, Freddie Mac, and the Federal Home Loan Bank System are operating in a safe and sound manner to serve as a reliable source of liquidity for equitable and sustainable housing finance and community investment throughout the economic cycle.”
Over the past several years the FHFA has been very clear that it sees the purpose of Fannie Mae and Freddie Mac (GSEs) is to enable homeownership, primarily for first-time owner occupying homeowners with moderate income.
In recent years the FHFA has increased the upfront fee paid on all loans, as well large increase in pricing for high-balance loans (except certain instances of first time buyers), second homes, and non-owner occupied properties.
A few weeks ago the FHFA announced new Loan Level Pricing Adjustments (LLPAs), essentially the cost (points) that the GSEs must charge lenders for certain factors that appear in a mortgage. These fees are passed onto borrowers as adjustments to loan pricing when a mortgage is locked and funded.
LLPAs have always been part of the pricing matrix for mortgages as loan amount, occupancy, type of property, loan-to-value, and credit score are factored into the available rates and corresponding cost in points (one point equals 1% of the loan amount, 1 point on a $100,000 mortgage is $1000).
In line with its new mission statement, and the current interpretation of “equitable and sustainable,” the FHFA’s new LLPAs continue the trend of the past few years of increasing the cost of mortgages through the GSEs for borrowers who do not fully conform to their mission and purpose.
As an example, with the new fees, homebuyers with low down payments and lower credit scores will see lower fees when the new LLPAs go into effect later this year than they would pay closing a mortgage today. Homebuyers with higher down payments and higher FICO scores will pay more for a mortgage later this year than they would today.
For example, a homebuyer with 5% down and a score of 620 will see the cost of the mortgage lower by one-point (1%); a homebuyer with 15% down and a 740 score will see the cost of the mortgage higher by three-quarters of one-percent (0.75%). If both mortgages are $500,000, the first buyer will see a savings of $5000, the second buyer will see increased costs of $3750.
Here are some other changes to fees that will take effect May 1, 2023 (note, most lenders will add the fees to rate sheets for loans closing on or after May 1, 2023—so for a thirty day rate lock the fees will show up in late March and early April):
- The most contentious change in the industry is higher fees for borrowers with debt-to-income (DTI) ratios higher than 40%. This is a challenge as DTI calculations change during processing and underwriting as interpretation of how to calculate income from non-salary/wage sources can be subjective at times, as well what impact and when in the process will paying down debt to lower DTI be calculated. This new fee can, and in some cases will, cause the price to change on some loans after they have been locked.
- Less of a penalty for credit scores below 680.
- More tiers for credit score pricing. Prior to new adjustments all scores over 740 had the same pricing; the new credit score matrix will have tiers every 20 points from 680 to 780.
- For middle score borrowers (700-759) with less than 25% down pricing will be higher.
- Significantly higher fees for cash-out refinances. This will impact families who have taken out Home Equity Lines of Credit during this cycle of high interest rates who look to refinance and consolidate their HELOC with their current mortgage to lower monthly payments.
Long time readers of the WR&MU know I am a big proponent of putting less money down on a home purchase and having mortgage insurance to save cash in the bank. For some transactions this will still be the case, for others the calculation may change depending on your credit score, DTI, and the amount of the down payment.
These increased fees will expand the benefits that we at Stratis Financial can provide as depending on the circumstances, a more affordable mortgage may be available through FHA, various banks, or jumbo lenders with whom we have relationships and can use to compare your rates and costs to find the best fit for your situation.
Within the industry many of us feel that this is just the latest tightening of the FHFA on Fannie and Freddie with the end goal being the GSEs are lending almost solely to low to moderate income buyers purchasing their primary residences.
A consensus in the mortgage and real estate industries are these new LLPAs costs to borrowers are most harmful to middle-buyers; those with middle down payments, middle credits scores, and mostly middle class borrowers.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
BOOM! Rates have their largest week-to-week increase since June. A combination of many factors saw interest rates for fixed rate instruments (bonds, Treasury bills, mortgages, etc) spike yesterday as prices in those markets dropped (lower prices, higher rates). Last week’s jobs data gave momentum to higher rates and sellers came to market flooding inventory to a paucity of buyers and those buying wanted higher rates. The result were investors in Asia and Europe selling Treasury debt, as well as the Federal Reserve continuing its quantitative tightening policy and dumping Treasuries and mortgages, and a week where the Treasury was auctioning new debt.
Rates for Friday February 10, 2023: As the Mortgage Backed Securities markets started getting more and more momentum with falling prices (again, lower prices higher rates), lenders have tried to keep up by raising their rates throughout the day with midday rate changes. As I write this near noon Pacific, we are close to the close of the markets, and mortgage lock desks are still open. It would not surprise me if many/most lenders reprice once more before the weekend to protect themselves ahead of Monday’s markets opening.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
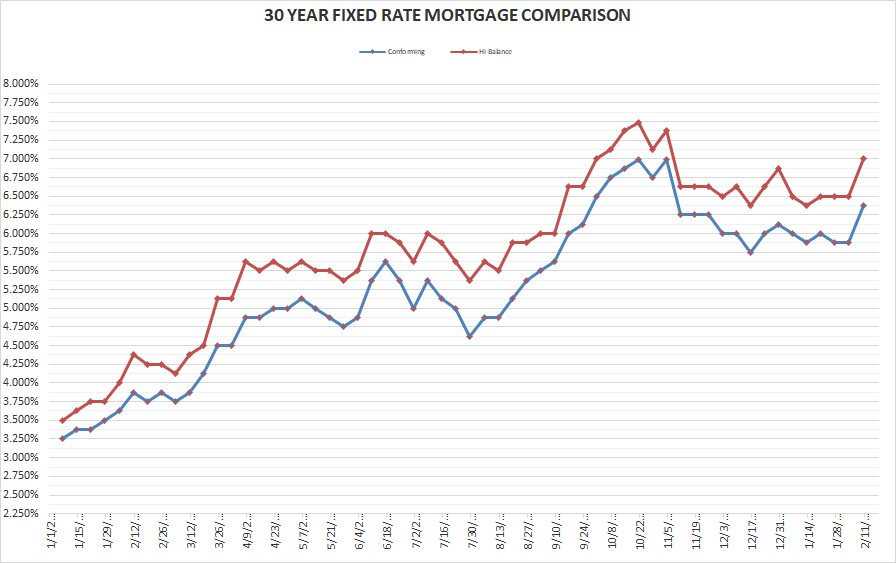
30-year conforming 6.375% Up 0.500%
30-year high-balance conforming 7.00% Up 0.500%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It should be a great game on Sunday, my hope is that it is a great game with an even greater ending….Go Birds! Fly Eagles Fly
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


