

Are we breaking the law?
Question of the week: Are we breaking the law?
Answer: I hope not!
This question came from long time client Tomas. He called in a panic as over the years, decades?, he has purchased several homes, some of which he retained when buying a next home.
His panic was due to the Department of Justice investigating several very high-profile politicians and others for mortgage fraud stating those being investigated had sign owner occupancy statements on multiple loans stating the subject property(s) would be their primary residences.
The investigations are for mortgage fraud as technically you cannot have more than one primary residence.
The high profile, and highly covered, investigations have worried Tomas as he currently has two properties that have loan documents the he signed stating they would be his primary residence, prior to the rate drop during Covid he had three such mortgages.
My answer to Tomas was, “no you need not be worried.”
How can this be?
Because for each of the mortgages he signed the intent to occupy affidavit, and he did occupy the properties as his primary residences.
This question has come up from time to time through the years with clients who purchase homes, get an owner-occupied mortgage, and then purchase another property and want to keep their current property. “Do we have to refinance the mortgage?”
No, because the did occupy the property. The owner occupancy affidavit does not state that the loan is callable and must be paid off or you are in default if at some point in the future you no longer occupy the property.
Tomas purchased his first property sometime in the early 2000’s. After several years, his family had out grown the home and they had the ability to purchase a new home and not have to sell their first home. He purchased his next home and rented out his first home.
A few years later, they moved to Orange County, purchasing a new home and once again keeping their current home and renting it out.
At this point Tomas has three properties, all of which have mortgages that have loan documents stating the properties will be owner occupied.
Covid hits and rates drop considerably. We refinance Tomas’ two prior properties with non-owner-occupied mortgages, and his Orange County home with an owner-occupied mortgage.
Earlier this year, Tomas and his wife, now grandparents, downsized to a smaller home near their home in Orange County and purchased it with an owner-occupied mortgage. Their daughter and family moved into their home and they have retained the refinanced mortgage due to its low payment and interest rate.
Currently Tomas has three mortgages for which he is obligated, two owner occupied mortgages and one non-owner-occupied.
Tomas did not commit mortgage fraud, and cannot be successfully prosecuted for mortgage fraud as in every instance in which he funded an owner-occupied mortgage he fulfilled his intent to occupy the property.
A question that comes up with some looking to obtain a more favorable mortgage is, “if I purchase this home with an owner-occupied mortgage how long to I have to occupy the property?”
This is akin to asking how long will it take for my ice cream to melt and drip all down the cone and onto my hand.
It depends on many circumstances, but you want to be very sure your hand doesn’t get sticky because it is a federal crime that if fully prosecuted and sentenced can result in up to 30 years in prison and fines up to one-million dollars, depending on the severity and if other crimes are involved.
Over the years I have run into a few instances where we helped borrowers whose lenders were calling loans due for non-occupancy.
In one instance, we had an active military member who was transferred overseas not long after purchasing his home with a VA mortgage. Providing his transfer papers and dates sufficed to enable him to retain the mortgage and rent to home out until his overseas duty was completed.
In another instance, a client’s company was purchased and he as transferred to the East Coast not long after purchasing their home. Again, correspondence regarding the transfer, letter from employer it was either move or lose his job, satisfied the lender.
In the mortgage business the approach is guilty until proven innocent. Underwriting is adverse, you have to prove you make the money you make, the funds you have are sourced and legitimate, the property is sufficient collateral, beyond all reasonable doubt.
When it comes to investigating if a borrower has fulfilled the intent to occupy the same holds true, prove beyond a reasonable doubt you did intend and fulfill the obligation.
Do not create reasonable doubt, fulfill your intent to avoid serious consequences.
Have a question? Ask me!
It’s going down. I’m not talking about the social media being filled with pictures of anything pumpkin spice. I’m talking about the Federal Reserve’s benchmark interest rate. The jobs data for August was released today and it pretty much guaranteed a rate drop by the Fed in two weeks. As well, the data has brought into discussion if the Fed may cut by 0.5% (one-half of one-percent), instead of the typical 0.25% (one-quarter of one-percent) that is more typical.
Why? The Labor Department reported that only 22,000 total jobs were created in the economy last month. Leading the way in creating more jobs, as they have been for several months were the education/health care (16,000 jobs) and leisure/hospitality industries (17,000 jobs). Large net losses in employment were professional/business (-17,000) and government (-16,000).
Knocking but no answer. The unemployment rate was 4.3% for the month, the largest since 2021, however the primary reason for the increase from 4.2% was more people looking for work. Looking but not finding as more businesses are not filling empty positions.
The bright spot in the data was wages showing an increase of 0.3% for the month and up 3.7% from last August, both outpacing inflation.
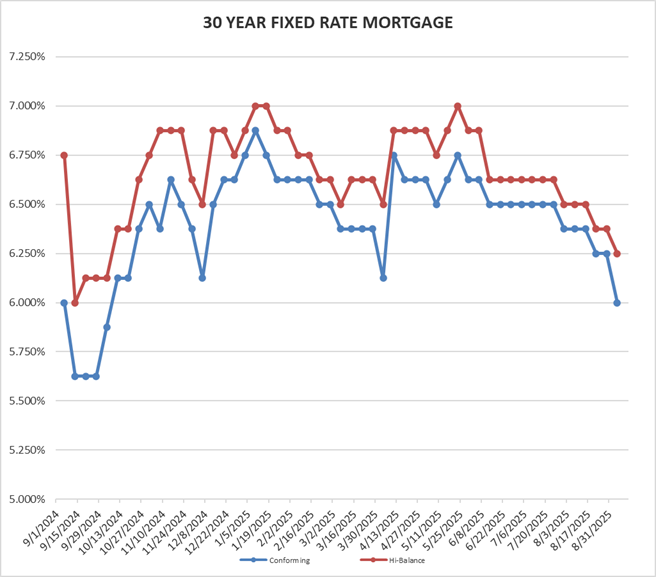
Rates for Friday September 5, 2025: Rates drop to their lowest since October on the jobs numbers.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 6.00% Down 0.25%
30 year high-balance conforming 6.25% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
“Thirty Wonderful” was the tag Leslie put on her social media post of a picture from 31 years ago yesterday of a much younger Leslie and Dennis in wedding regalia holding up our glasses for a toast.
I definitely hit the marital jackpot, and being able to watch the Eagles get by the Cowboys as we ate chicken sandwiches with beer as our anniversary dinner just upped the amount of the jackpot I have hit.
Those concerned about the lack of celebration, we will have a nice evening out this weekend to properly celebrate the past 31 and what is to come in the next.


