What is a Home Warranty Plan?
Question of the week: What is a Home Warranty Plan?
Over the past few weeks I have had several questions regarding the various insurances involved in a real estate transaction. I have decided the best way to address the questions for the next several weeks to have a series on insurance in the Weekly Rate and Market Update, this series will cover home warranty, homeowners’, title, mortgage, and finally mortgage life/disability insurances.
Answer: In Section 7, Part D, subsection 10 of the California Association of Realtors Residential Purchase Agreement and Joint Escrow Instructions (aka the Offer) the buyer has the option of checking whether, as part of the terms of the offer to purchase the property, the buyer or seller shall pay costs not to exceed a certain amount for a one-year home warranty plan. The section also contains a place for the buyer to indicate which company shall issue the plan and what additional coverage beyond “normal” the warranty may cover, such as air conditioning or pool equipment. If the buyer does not complete this section the next clause on the purchase agreement form is checked, which is an acknowledgement that the buyer is waiving the purchase of a home warranty plan.
As a side note, congratulations to the home warranty industry for have their product embedded into the contract used for almost every residential purchase in the state.
Back to our question, what is a home warranty plan? It is essentially an insurance policy that covers a lot of things a homeowners’ policy will not cover if something needs repair or replacement. Appliance, electrical and plumbing systems, if there is an issue and you have a home warranty plan, contact the carrier, let them know the issue and they will send someone out to repair or fix the issue.
From dripping sinks and clogged pipes, to burned out water heaters, to faulty central heating and air, if you have a home warranty plan in place the chances are you are covered for repair or replacement. Most plans will not cover roofs and leaks from above or below, nor flooring, walls or built-ins like cabinets.
The cost of the plan depends on the service call fee you choose for a professional to come out and either fix or replace the issue. This is like a co-pay for health insurance. The lower your co-payments per visit to a medical professional the higher your premium will be; the same for home warranty plans, the higher your service call fee the lower your annual, or monthly, fee will be for the plan.
It is important to note that you do not need to be purchasing a home to obtain a home warranty plan. Nor do most home warranty companies require a home inspection prior to issue a coverage plan. If you have lived in your home for two, five, fifteen years or longer you can obtain a home warranty plan that covers your appliances and systems.
It is important to note that the professionals who are dispatched to inspect and correct your issue are contracted to the home warranty company, you cannot choose a local plumber or electrician that you have worked with before to correct the issue and then bill the home warranty company.
Over the years I have had clients rave about having home warranty coverage and those who have had poor experiences due to the quality of the service professionals dispatched for issues needing fixing.
Before purchasing a plan I suggest you do some research. Contact your real estate professional and ask which companies that have generated positive or negative experiences with clients. Go on-line and research the various companies available and search for reviews—keeping in mind most people bothering to post reviews on-line tend to do so to vent about a negative experience. What are the prices, service call fees and coverages for the different plans from different companies, and what do you feel you need for your home?
One final note, home warranty plans are not just for owner-occupied homes, if you have a rental property there are coverages available to cover the wear and tear that occurs over time and use.
Next week we will discuss homeowners’ insurance and what it covers.
Have a question? Ask me!
Rate cut no surprise. On Wednesday, the Federal Reserve Open Market Committee (FOMC) voted to cut its benchmark interest rate by one-quarter of one percent (0.25%). This action was expected and had been priced into all the financial markets weeks ago. Most rate moves by the Fed are expected so it is the details of the meetings that are market movers as investors try to anticipate the Fed’s next move by what was news comes out of the FOMC meetings.
What we may have learned from the information released Wednesday is that the FOMC is divided. The vote to lower rates was not only not unanimous but had three dissenting votes; the first time in three years there have been three “no” votes for the committee. Two of the negative voters did so because they felt there should be no change in rates; the third voted “no” because he felt that the 0.25% rate cut was not enough and the cut should have been 0.50%. What does this mean for future actions by the Fed? Complicating the answer is that seven of the twelve members of the FOMC say they anticipate one more rate decrease this year. Since that would be a majority of the voting members the expectation is for one more rate cut. This meets expectations from earlier in the year, three rate cuts between August and December, and a future rate cut is pretty much priced into rates.
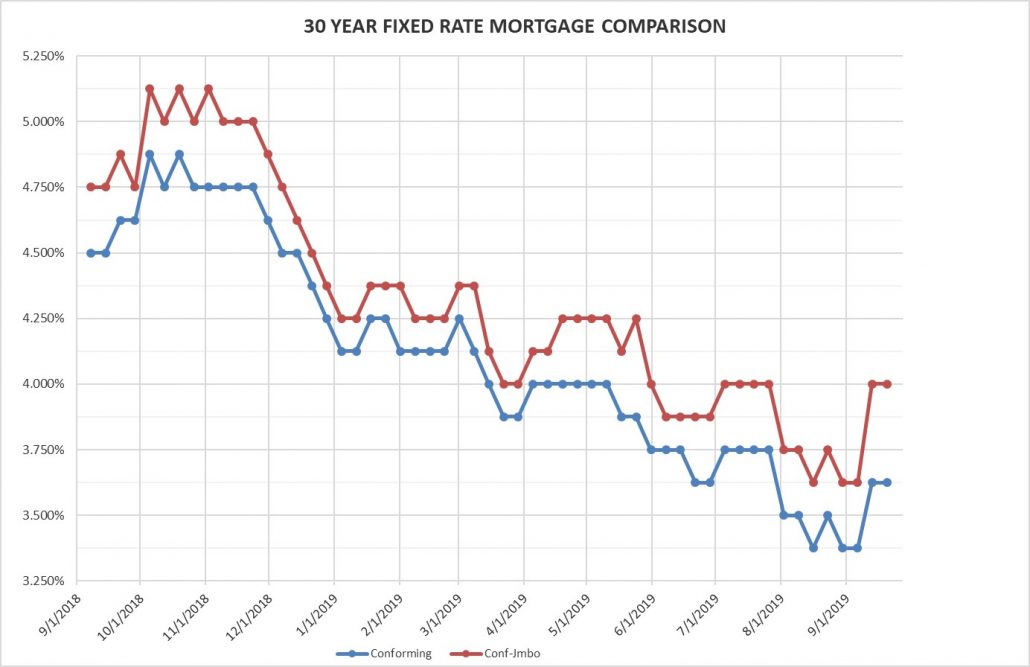
Rates for Friday September 20, 2019: This was another volatile week for mortgage rates as the Mortgage Backed Securities (MBS) prices fluctuated quite a bit every day—especially on Wednesday following the Fed announcement. Over all for the we end up very close to where we were last Friday despite a spike in rates on Monday that slowly disappeared through the week. The charts show that MBS prices may be approaching an interim high (higher prices mean lower rates), which portends a possible up tick in rates again in the next few days. The market is volatile, my advice is do not float your rate, lock it when you can through your escrow period.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.625% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
My personal note this week is a challenge. On the one hand I acknowledge our oldest turned twenty yesterday—I guess that makes sense since Leslie and I just celebrated our 25th, but while I recognize her as being 20 I still see the little girl and probably always will.
On the other hand, after I finish writing the WR&MU this week and post it to my webpage, Facebook and LinkedIn I will be attending a funeral for an incredible woman who has done so much for our community, mostly behind the scenes and without wanting much attention for what she has done. The everyday role models are the ones that I want for my daughters. Not the Oprahs, or Michelles, or Taylors, but the strong women who live and work in our community who take the time from themselves and their families to help others. That was Connie who will be mourned and celebrated later today. She was always smiling, and raising her hand to say, “I can help with that.” And she did help, a lot. So many people in our community are just that much better off because Connie rose her hand, and they never know this is the case or her name.
The wonder, beauty and experience of life is the juxtapositions of joy and heartache amongst other emotions and experiences.
Call or visit someone you haven’t seen or spoken to in a while, say hello and say thank you for being them and letting you be you.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog