

Should we change our homeowners’ insurance?
Question of the week: Should we change our homeowner’s insurance?
Answer: We can also put “auto insurance” in the question of the week as well.
It is not new news that insurance premiums are increasing dramatically in California for all types of coverages. Because of these increases many are shopping around for cheaper rates to cover their homes and autos. Some have no choice as their insurance companies may have declined to renew policies.
While it makes sense to see if lower cost coverage is available, the question is whether it makes sense actually change your insurer.
A major insurer has had a national advertising campaign for the past few years stressing bundling your coverage, which I strongly suggest. The more policies you have with one company, the lower your rates as all insurers have discounts for bundling coverages.
As well, discounts are also given if you are “claim free.”
Going to a new insurer with just your home or auto, may result in an increase in the premium for the other policy based due to breaking the bundle.
While not a written policy, when it comes time to decline renewals, some companies are retaining those customers who have a long-term relationship with the company.
Inability to raise rates for several years due to the California Department of Insurance Commissioner Ricardo Lara’s office denying requests for increases, higher payouts on claims due to wildfires, tremendous increase in costs to repair, replace, rebuild properties due to higher costs of building materials and labor, have all contributed to higher costs for home insurance.
Auto rates are jumping in part to the first item above, as well as more accidents, higher traffic volume, increase in car and car parts theft, and, like home insurance, costs to repair vehicles due to higher price for parts and labor.
Before making a change in your insurer weigh the savings, your current relationship, if any, with your agent, and risk of possibly being dropped by new insurer if you have a claim in the first, or second, year of your policy.
Schedule an appointment to discuss your options if you are considering purchasing a new home or property, or refinancing an existing one and want to know the mortgage options available to you.
Have a question? Ask me!
Cooling trend in effect, in regards to prices not the weather. July’s Consumer Price Index showed prices increased 0.2% for the month, with a year-over-year increase of 2.9%. The annual CPI is the lowest since March 2021, 2.6%, which was followed in April by a jump to 4.2% inflation. The closely watched “core index” (food and energy stripped from index) also rose 0.2% for the month and was up 3.2% from last July. Continuing to put upward pressure on CPI is cost of housing as home prices and rent continue to climb. Overall, the news is positive for rates and, depending on the jobs report for August, strongly support the Federal Reserve lowering its benchmark rate in September.
Not cooling, retail sales. Retail sales jumped 1.00% in July, after dropping 0.2% in June. The monthly increase is the highest in eighteen months. A major force in the higher retail sales was a big rebound in auto sales, which were impacted in June due to the cyberattack on auto dealers. Taking out automobiles and parts from the data sales increased 0.4% for the month. Taking out the 0.2% increase in prices from Wednesday’s CPI data, and sales rose about 0.2%, not bad, not great. That said, the increase in sales shows a moderately strong economy, and allays concerns after last month’s jobs report that economy is slowing and heading into recession.
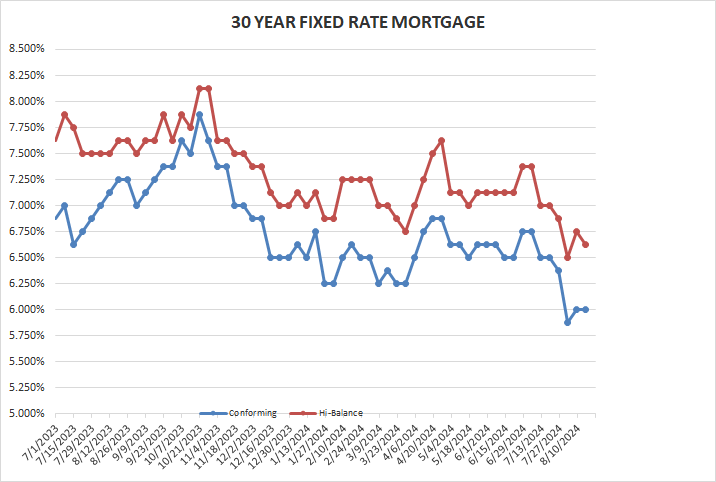
Rates for Friday August 16, 2024: Fixed rate markets, bonds and mortgages, were overall pretty flat this week as the data presented did little to change long-term expectations for rates heading down—at some point. The conforming rate is flat from last Friday, a slight dip in high-balance rates.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.00% Flat
30-year high-balance conforming 6.625% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The dog days of summer ended this week, which astrologically means so should the hot and humid days, drought, thunderstorms, lethargy, fever and mad dogs. I’m not sure about the lethargy part—for some of us that can be longer than 40-days—nor when I step outside most of the rest of the list. Though it has been a while since I have seen a mad dog.
The term dog days of summer originated during the Roman Empire and lasts from July 3rd through August 11th; twenty days before and after the rise and fall of the star Sirius, the brightest star in the sky that is also known as the Dog Star. The attributes of the dog days are part of Hellenistic astrology.
Hellenistic astrologists were obviously oblivious to Southern California in September when determining the hottest weather and thunderstorms for our region. Not to mention increase lethargy as students are back in school staring out windows and trying to stay awake when learning about astrology, mythology, and dog days of summer they miss so much.


