

Are appraisals no longer required?
Question of the week: Are appraisals no longer required?
Answer: No, but yes. In March Fannie Mae announced it wanted to make the “home valuation process more efficient and accurate.” To do this, Fannie stated it is “moving away from implying that an appraisal is a default requirement for valuing a property.”
Sounds like Fannie Mae is getting rid of appraisals.
In its announcement, Fannie indicated it wants to modernize the property valuation process, leverage technology and available data, to “make process more efficient for lenders, borrowers, appraisers, and secondary-market investors.”
Since the early days of Fannie Mae and Freddie Mac’s Automated Underwriting Systems (AUS) the software utilized valuations in their databases to issue “appraisal waivers,” indicating the value of the property submitted in the loan file appeared to be consistent with properties in the area. The appraisal waivers were one of many contributing factors to the mortgage market collapse in 2008 as many properties were over-valued on loan applications and the values accepted by Fannie and Freddie for funding mortgages.
Subsequent to the melt-down of real estate markets nationwide, and the Great Recession, we saw fewer appraisal waivers issued on files submitted through the AUS programs. They were most commonly issued on rate and term refinances for borrowers who had owned their homes for several years and with loan-to-values well below 80%.
With the new guidelines that took effect last week, Fannie Mae is eliminating the appraisal waiver and replacing the waiver with “value acceptance.” While it is the same result of the appraisal waiver, the value acceptance finding on the AUS review, in Fannie’s view, reflects the process of using data and technology to accept the value of the property as provided by the lender.
Properties not receiving the value acceptance designation, may be eligible for “value acceptance + property data.” This option is one that significantly changes the property evaluation industry. With VA+PD, the value of the property as provided by the lender is accepted, but for final approval and funding interior and exterior property data collected by a third party is submitted for the underwriter. The “third party” need not be a licensed and bonded appraiser. The requirements from Fannie are that the data collectors are vetted through an annual background check, professionally trained, and possess knowledge to competently perform the data collection.
The “data collection” is essentially using a camera, or mobile phone, to take photos and/or video of the property’s interior and exterior to show condition to confirm eligibility. Not explicitly stated are what factors the background checks are to be examining, what training is required, nor how to evaluate if the third-party has the knowledge to be competent.
To protect themselves, I am assuming that lenders will require the third party property data collectors are obtained through already approved Appraisal Management Companies, essentially requiring a licensed appraiser to perform the inspections.
One objective Fannie with the change in property valuations is to lower costs for mortgage applicants. If their application receives a “value acceptance” and no appraisal nor property data reports are required, there is definitely a savings to the borrower.
If the application requires a value acceptance + property data designation, there should be reduced cost as an appraiser will not be required to compile a report with comparable sales, evaluating the sales prices, dates, size and conditions of properties, etc. Instead, someone will be dispatched to the subject property to take pictures and transfer them to the lender.
Questions have arisen regarding the efficacy of the reliance on Fannie Mae’s database to provide accurate market valuations of properties. In our current market where some neighborhoods have not had a closed home sale in months, how will Fannie evaluate the value of a home entering escrow?
If some homes have sold in the past six months in an area for $750,000 that were all due to the passing away of the owners, the homes being somewhat dated and run down and not in great condition, and you are buying a home that is unique, larger, in excellent condition that has been recently upgraded throughout for $825,000, how will this be evaluated by Fannie?
From what I have been reading, like the appraisal waiver before it, the value acceptance will not be stating “this is the value given to the property by Fannie Mae;” but rather stating that Fannie accepts the value provided by the lender in the application.
For challenging property values appraisals will still be required. As it has been for as long as I have been in the industry, borrowers will have the ability to appeal appraisals that have values below what they feel reflect the current market for their specific home and area.
For most borrowers the new property evaluation measures from Fannie Mae should be a benefit as it removes the more expensive in-depth appraisal process. That is a good thing.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
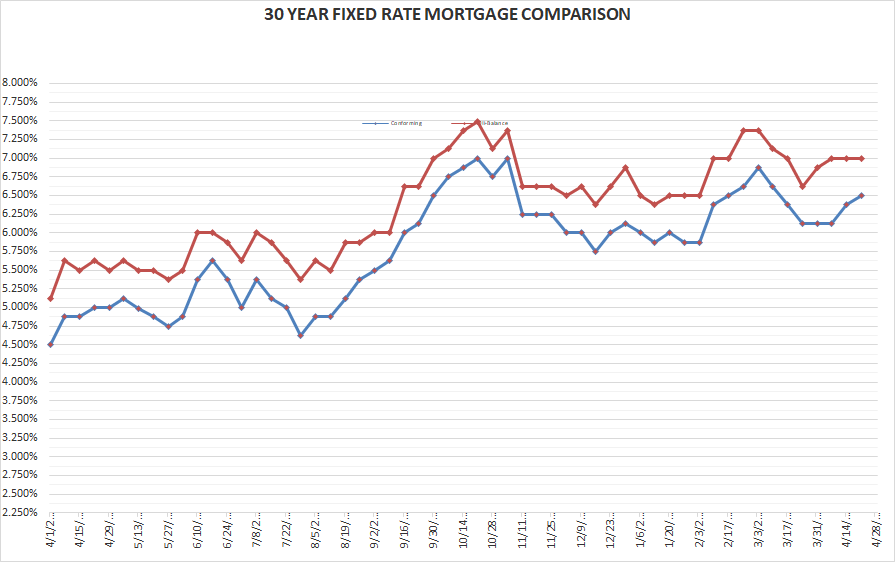
Rates for Friday April 21, 2023: Not a lot of economic news that is typically impactful for mortgage rates. The momentum remains downward in bond and mortgage markets (lower prices higher rates), momentum that started at the beginning of the month with the strong jobs report. Our economy is moving such that inflation remains sticky, supporting continued moves by the Federal Reserve to push rates higher to slow the economy and reduce employment.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Up 0.125%
30-year high-balance conforming 7.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Is it here? Is it over?
With temperatures approaching and exceeding 80 degrees for a few days does this mean “Spring” with it rain, temperatures in the 60’s or below, is over? Is our run of warm sunny days for the next five to six months here? Or are being teased for more damp, cool (cold?) days?
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


