

What does “borrower paid” mean?
Question of the week: What does “borrower paid” mean?
Answer: In the July 16, 2021 WR&MU we answered, “What are points and do we have to pay them?” For those not wanting to click, points are the upfront cost of a mortgage, the higher the points the lower the rate; conversely the lower the points the higher the rate.
When pricing a loan with lenders, mortgage brokers use a pricing engine from the lender. One of the many factors we input to get rates is a pull down that asks “Lender Paid” or “Borrower Paid.”
This query is in regards to the points on the loan. If the lender paid option is chosen, the rate is higher, and the originating broker cannot charge any origination points. If borrower paid option is chosen, the borrower will have different rate and cost options—the lower the rate the higher the costs, the higher rate the lower the costs.
In the WR&MU referenced in the opening sentence above, one of the options for not paying points is having the seller give a credit to the buyer at closing which will cover the points for the buyer (borrower) to buy down the interest rate on their mortgage. If this is the case the pricing factor for the loan will be “borrower paid” to buy down the rate.
Moving forward, “buyer paid” will be written into some sales contracts between buyers and sellers. In this case the buyer paid refers to the commission for the real estate agent representing them in the transactions (known as the selling agent.” This reason for this was covered in the November 17. 2023 WR&MU, which covered a court case that resulted in a major change in the real estate industry regarding sales commissions and who needs to pay who.
Everything is negotiable in a real estate purchase, price, credits, fees to affiliated businesses involved in the transaction, commissions. When writing your offer to purchase your new home consider if paying a higher price and receiving credits from the seller to cover some of your costs, fees and commissions, may be a better “deal” for you than paying a lower price and covering all those costs yourself.
See the July 1, 2022 WR&MU, “Why should we pay a higher price for our new home?”
If you, or someone you know, is thinking of purchase a new home, schedule an appointment on the link below to go through your options looking at total funds needed to close versus monthly payments for your mortgage.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
If you are the average American, in May you bought a new car, spent less on gas, went out to eat less often, and did not go to retail stores as often, as you did in April. This, according to the retail sales data released earlier this week that showed over all retail sales were up only 0.1% from April, which had it retail sales adjusted to show a decline of 0.2% from sales in March. Keeping the total sales data positive was an increase of 0.8% in auto sales from April, balanced a bit by a continuing drop in gasoline prices (down 0.8%, anecdotally, I paid $4.499 for premium yesterday). The 0.4% drop in restaurant sales is a very strong indicator of the impact inflation is having on families as going out to eat is perhaps the number one discretionary spending option.
Taking auto sales out of the data, retail sales declined 0.1% in May. Considering that retail sales data are based on costs at the register and not the number of units purchased, and the core CPI showed inflation at 3.4% in May, one can extrapolate that “units sold” were down about 3.5% in May.
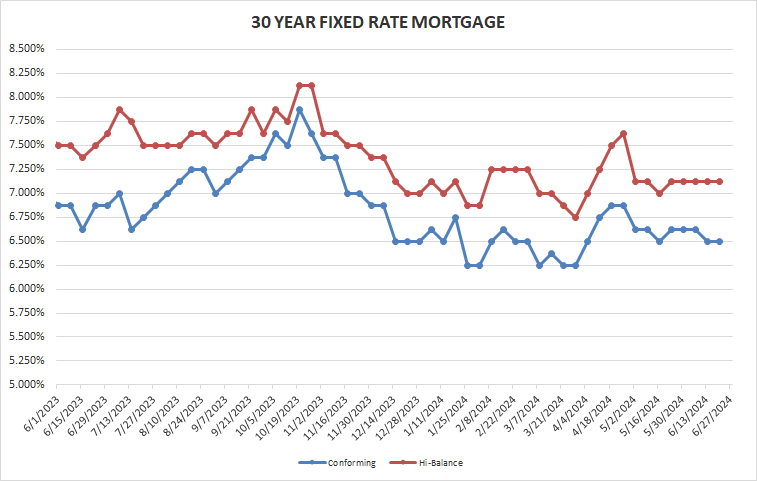
Rates for Friday June 21, 2024: Retail sales did give a bit a boost for the interest rate markets of bonds and mortgages, which results in lower rates, as the data supported a slowing economy which leads to lowering inflation which leads to the Fed cutting its benchmark interest rate. However, the gain was short lived as investors had already priced in a rate cut by the Fed, rates from last Friday remain flat.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Flat
30-year high-balance conforming 7.125% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
For my generation, and a generation or two older, our legends and heroes are leaving us. Basketball legends, especially here in Southern California, Jerry West and Bill Walton passed away in the month. This week one of my heroes, and definitely my mom’s, Willie Mays, died.
Willie was, a bit arguably but not much, the greatest baseball player in the history of the game. I say a bit arguably as for many years, especially in arguments with Mom, I put forth Henry Aaron—who was my favorite along with the great Johnny Bench.
Both Mays and Aaron started their professional careers as teenagers playing in the Negro League before their contracts were purchased from their teams by the New York Giants and Milwaukee Braves.
Mays could do it all, hit, run, hit with power, field and throw, and he did each of those as well or better than anyone. Mays ended his career with 660 home runs, Aaron with 756. I saw an interview, which unfortunately I am unable to find to link, where both May and Aaron were with Roy Firestone who brough up home runs. Both of the greats said they each could have had more home runs, but often all the team needed was a hit to score a runner on base. They put winning and their teams ahead of personal statistics and records.
One final note on Mays that changed the history of baseball. In 1950 when Mays was with the Birmingham Black Barons a scout for the Boston Red Sox had a deal with the owner of the Black Barons to purchase Mays’ contract for $4500. However, the owner of the Red Sox Tom Yawkey declined to make the deal, according to George Digby the scout, he was told, the Red Sox owner and front office “already made up their minds they weren’t going to take any black players.” Not only did the Red Sox not sign Mays, but years earlier they passed on signing Jackie Robinson; who broke the major league color barrier with the Giants rival, the Brooklyn Dodgers, resulting in many pennants won over the Giants.
Not long after the Red Sox passed on Mays, the New York Giants purchased his contract for $10,000. The Red Sox would not break their segregated line up until 1959, twelve years after Jackie Robinson played his first game for the Dodgers.
Baseball historians can only wonder how many World Series titles the New York Yankees would not have won in the ‘50’s and ‘60’s if Willie Mays had played in Boston with first Ted Williams and then Carl Yastrzemski in the outfield with him, and offering protection in the batting line up.
Poignant that last night the Giants played the St. Louis Cardinals at Rickwood Field, in Birmingham, the same field where Mays played and the oldest professional baseball stadium in the country. Mays was to be part of the ceremonies for the game. He was celebrated and honored last night, as were many players from the Negro Leagues who never had the opportunity to play in the major leagues.
One final note, Major League Baseball announced earlier this month that the records and statistics of players in the Negro Leagues would be incorporated into those of the Major League players, resulting in some changes as to career leaders in several categories.
Play ball!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


