

When will we know it is time to buy?
Question of the week: When will we know it is time to buy?
Answer: Not an uncommon question for those of us in the real estate industry; agents, lenders, escrow officers, appraisers, almost anyone directly, or tangentially, active in real estate gets this question not infrequently.
The question is the real estate version of “when should I get back in the market” after a correction in stock markets; or conversely, “when should I sell XXX stock that has risen significantly.”
The question is basically, “can you tell me how to time the market perfectly to buy/sell?”
The question arises from fear. Younger generation(s) have given us FOMO, for my generation not in the know: Fear Of Missing Out. FOMO arose on social media for users to post that they may miss an event, opportunity that will be fantastic—maybe it turns out to be okay, but they spent the time and money because they didn’t want to miss out in case it was great.
Inherently, we delay decisions, important decisions, because of FOMO.
At the beginning of February we showed the increase in cost and payment purchasing a home in January 2024 versus purchasing in January 2023. As shown in the 2/2/24 WR&MU, the cost to purchase a home due to higher prices and rates went up 10.71% in payment due to 6.42% price increase and 6.12% increase in rate.
Those who succumbed to FOMO January 2023 made the right decision, those who did not succumb as they were waiting for rates and/or prices to drop in 2024, appear to have lost out.
“Appear,” as many are still wondering when prices and/or rates will drop to make homes less expensive.
There will be a “when” on interest rates. All indications are rates will drop this year. What is unknown is how far, and when.
If you purchase a home today and rates drop later in the year, next year, at some point in the future, you should be able to refinance to lower your payment, making your home “cheaper.”
If prices rise and rates decline, you are not saving. Running different scenarios using $800,000 purchase price today at today’s rate with 20% down, the payment is approximately $3940 per month, and the down payment is $160,000.
If rates drop to 6% (down 00.5% in payment) and the price increases to $825,000 (up 3.1%), the monthly payment increases slightly, $20, but your down payment increases $5000—along with your taxes and insurance.
Going further, if the home’s value increases 6.3% to $850,000, and rates drop to 5.75%, the payment is $30 more per month than our base scenario ($800,000 price, 6.25% rate), and your down payment is $10,000 higher, and taxes and insurance will be higher.
Finally, what really matters is how long will you own the home? If this scenario was reversed, and you purchase a home for $850,000 and values take a rare, for Southern California, 6.3% drop to $800,000 in a year to 18-months, but you will own the home for several more years, historically the value will increase above your original purchase price within 24-months of that decline.
Also unknown, is what will happen to prices as rates drop? As I have been writing for more than a year, economics fundamentals, i.e. supply and demand, should dictate that prices remain stable, or more likely, in my opinion, continue to increase.
Looking at the above scenarios, as rates go down more families will enter the market to purchase homes, increasing demand. As well, more families that have been waiting to move up, or down if older, but do not want to trade their mortgage rate in the 3% range for a new rate above 6%, will put their homes on the market to buy their next home, increasing supply—but also demand.
Overall, demand should be higher than supply for quite some time absent a major economic downturn that impacts the middle class causing them to need to sell their homes. That event, absent some major external event, is not on the horizon.
Answering our question of the week, the right time to buy a home is when you can afford to buy the home you like. Trying to time the market to get “a deal,” is impossible as the bottom of any market is not known until several months, in some cases year or more, have passed.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Lower rates? Consistent readers of the WR&MU know that the Fed watches not only inflation data but also labor market data as it decides what to do with its benchmark interest rate. Today the Labor Department released the jobs data for February, which was a mixed bag. The top line number, 275,000 jobs added in the month, was not rate friendly. However, digging into the data some rate friendly numbers are discovered. First, while almost 80,000 more jobs were added than expected in February, total job gains for December and January were reduced by 160,000 jobs, greatly reducing the impact new hires last month. Second, wage growth for the month was only 0.1%, below inflation for the month. Finally, unemployment increased from 3.7% to 3.9%; for unemployment the Labor Department uses household surveys where fewer respondents said they were employed and more said they were looking for work. This survey method is not as accurate as actual payroll numbers, but is a gauge of where the labor market is going. All these factors mitigate the impact on rates the large leap in payrolls would normally have on markets, and interest rates. In other words, the overall report does not give a lot of indication the Fed will push off its first lowering of its benchmark to later in the year.
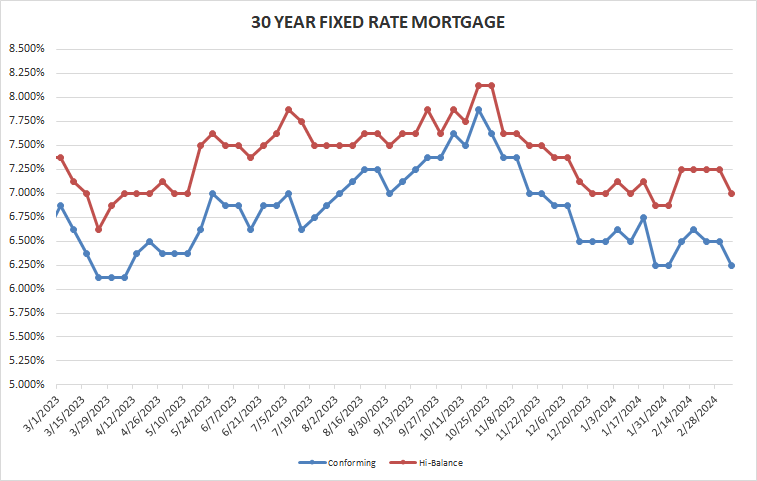
Rates for Friday March 8, 2024: Bonds and Mortgage Backed Securities (which determine mortgage rates) have been strong all week (higher prices mean lower rates), as a result we see a big drop in rates from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.25% Down 0.25%
30-year high-balance conforming 7.00% Down 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
In or out on the Oscars?
Leslie and our youngest daughter are very much in, I am pretty much out. I love movies and going to the movies; however, I am not a big fan of award shows. This started to occur earlier in the century when they became more and more political on the presentations and acceptances, and my interest continued to decline when they expanded the nominees—in large part due to the explosion of movies by streaming companies’ production companies.
Of the several nominees for best picture, I have seen four, Barbie, The Holdovers, Maestro and Oppenheimer. Of these four I enjoyed all of them, however the standout was The Holdovers—the biopics of Bernstein and Oppenheimer were excellent, however the story, casting, acting in The Holdovers has my vote.
Our tradition is hot dogs for dinner on Sunday (OSCAR Mayer), and my watching a movie or show in the kitchen, while my wife, and any guests, watch the big show in our family room.
If you are an Oscars fan, I hope you have a great show and enjoy it. If not, I hope you enjoy whatever your option is!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


