What do you need to pre-qualify us for our new home purchase?
Question of the week: What do you need to pre-qualify us for our new home purchase?
Answer: There are three legs to the pre-qualification stool: Money, Credit, Income. To get pre-qualified, or pre-approved which takes the same amount of time and information, I need information on each of the three legs.
Money How much money do you have for down payment and closing costs? Is all the money your money and in your bank account right now? Are you getting a gift from a family member to cover some, or all, of the funds needed? Copies of your most recent bank, investment accounts and retirement account statements will let us know how much money you will have for your purchase and any reserves your particular loan program may require. I have had clients in the past who have not shown me all their asset statements because, as one client put it, “If I show it to you then you will spend it.” Not true and not possible. I cannot spend any of your money, but I can show you different options for sales prices, loan amounts and monthly payments if I know about all your asset accounts and in what manner they are held.
Credit This category covers not only your current outstanding credit obligations, such as auto loans, student loans and credit cards; but also, if you have any spousal or child support payments or other court ordered payments. We need to know how much you owe, how much you have to pay on a monthly basis and your history of making payments. The quickest and easiest way for us to get this information is from a credit report (which will not show spousal or child support payments). “Is it necessary?” is a very common question when we request the authorization to run a credit report. The answer is, yes if you want to make sure you are getting an accurate pre-qualification for how much of a house you can buy. We can put in the information you provide us and provide some price and loan options, however unless we are viewing a recent credit report the information is not fully reliable for the basis of being pre-qualified. “If you run a credit report you will hurt my credit score,” is a common objection we hear. Running a credit report for the purposes of obtaining a mortgage, or getting pre-qualified, will very likely not have any impact on your credit score—if you have had several (by which I mean more than four or five) such reports run in the last few months one more inquiry may take a few points off your score. If you have had no inquiries run in the last few months for mortgages then our obtaining a report will not have an impact.
Income How are you paid? Are you self-employed? Do you have investment property? Do you have multiple streams of income? How long have you been receiving your income from its current source? Do you have overtime or bonuses? For most clients, this is a fairly easy question to answer. Most people are salaried employees who receive a W2 at the end of the year and we can easily and quickly calculate income. If this is the case then we need recent paystubs and most recent W2. If this is not the case then we will want to see at minimum the most recent federal income tax return that has been filed, and very likely returns for the past two years.
With all of this information we can usually pre-qualify, or pre-approve, you very quickly for a sales price and mortgage amount—by very quickly I mean less than fifteen minutes. If your income is a bit more complicated then we may need a bit more time and information.
What is most typical however, is a conversation that will take more than a few minutes, ideally in person but over the phone is also effective, so I can learn what you are looking for, your tolerances for payments and funds to spend, and making sure you have a full understanding of the transaction you are about to enter into, how the process works and most importantly that you are comfortable with the figures I am providing for price, loan amount, cash to close and monthly payment.
If you, or someone you know, if considering purchasing a home in the future please contact me to go through your options. If the potential purchase is not schedule for several months I strongly recommend having the initial conversations about how to purchase your new home sooner rather than later so that if there are any areas that need to be worked on to ensure approval you can start right away and not delay your purchase in the future.
Have a question? Ask me!
It has been ten years since real estate sales in California were as low as they were in January. The California Association of Realtors released home sale data for January and total sales were the lowest statewide since April 2008, with volume dropping 3.9% from December and down 12.6% from January 2018. The median price is up from last January by 2.1% statewide, but off 3.4% from the prior month with a value of $538,690. In Southern California both the LA and Orange County markets so drops in sale volume month-to-month and year-to year; LA down 25.5% for the month and 14.2% for the year while the OC saw sales drop 17% monthly and 13.2%. The median price in LA County in January was $588,140, down 3.8% from December’s $566,010 and up 0.3% from last January’s $564,100. Across the border in Orange County the median price was $796,500, up 1.5% from the prior month’s median price of $785,000 and up 2.1% from last year’s $780,000. January is historically a slow closing month for real estate as not a lot of escrows are opened between Thanksgiving and Christmas, that said this January was particularly slow. Anecdotally, our office has seen an upswing in purchase business so far this month from prior months—we will see if that is a regional and/or a statewide trend as well.
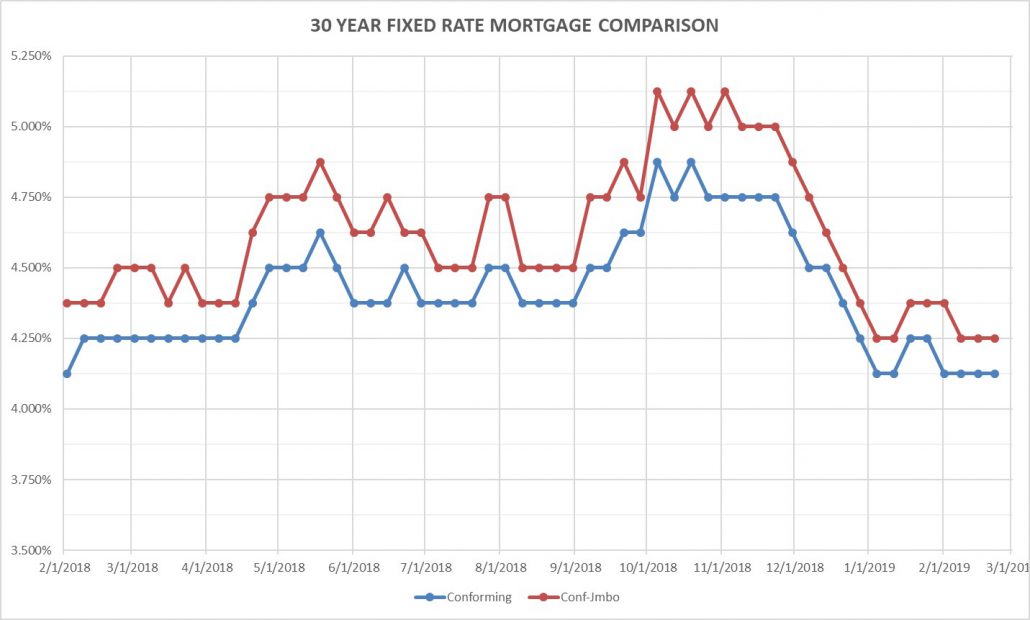
Rates for Friday February 22, 2019: With not a lot of economic news this week rates are flat from last Friday. There is a bit of possible long-term softening as the Federal Reserve Open Market Committee (the FOMC, who sets the direction for the Fed on rates and monetary policy) minutes from their last meeting indicated they will be slowing down their sale of assets consisting of Mortgage Backed Securities and U.S. Treasuries, this will put less supply on the market and less upward pressure on interest rates in the markets.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 4.125 Flat
30 year high-balance conforming 4.25% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
This is a joyous and remembrance week in our family as on the 19th our youngest celebrates a birthday and on the 21st we remember my father who passed away on that date in 2014. Many people over the years have told me they may not read all of the WR&MU, but always ready this third section, the personal bit. This always causes me to smile as my dad did not like that I included this segment, “who wants to read that stuff? You have some good information and then put in that your daughter dances ballet.” I told him many times over the years, “Dad, this is the only section some people read and the only section almost everyone reads.”
Thank you for reading this and validating my stance with Dad.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog