Should we co-sign for our son or daughter’s home purchase?
Question of the week: Should we co-sign for our son or daughter’s home purchase?
Answer: Yes. No. Maybe.
As we have seen in the news lately, many parents will do anything they can to help their children get a leg up, to get a strong start, to ensure a more comfortable life. Some parents do it by trying to help their kids get into certain colleges, some parents do it by helping their children with the purchase of their first home. We all want the best for our children, the question is how far are we willing to go, or for many parents how far can we go?
It is hard for most families to purchase their first home, especially in Southern California. Our question this week is courtesy of long-time friend Andy who was inquiring, not for California real estate but in Central Pennsylvania—where home prices are also challenging for first time buyers given the average incomes and real estate prices. Andy’s daughter and son in-law want to purchase a home, but need a bit of help to do so sooner rather than later. I received an email from Andy with the question above, which after speaking about the situation boiled down to not should he help, but what is the best way to help.
There are several ways parents can help their children purchase a home. Each has different consequences, short and/or long term. A primary factor I have parents consider when we are having these conversations is what will be the impact on their lives today, and in retirement, or if they are retired their future.
Let’s explore the different ways parents can help their children obtain their own home.
SCENARIO ONE: One way some parents help is by purchasing the house themselves. They provide the down payment, they qualify for the mortgage, and they are the only ones on the title and mortgage. Their child moves in and the agreement is that at some point the parents will give the house to their son or daughter.
Typically, under this type of arrangement the child will make all, or some, of the payments for mortgage, taxes and insurance, either directly to lender, tax collector and insurance company. However, we have seen this situation where they do make the payments but pay their parents directly . If the latter the parents can then claim the payments as rent and then, if eligible, write off certain expenses. In this set-up, the parents essentially purchased an income property and rented to their child.
If the agreement is that the child will make the payments for the mortgage, taxes and insurance it is advisable for the parents to add the children to the title of the property. If it can be shown they have made those payments then they should be able to deduct the mortgage interest and property taxes (checking with tax professional first). In this scenario, the parents purchase the home, but essentially turn the home over to their child. In the future, by showing they have been making the payments and living in the property it will be easier for them to refinance in the future, should it be beneficial, and remove the parents from a mortgage obligation and obtain full title.
In this scenario, the consequences for the parents are that they are obligated on a mortgage and the tax liability of owning property. If there is some issue between the parents and kids and the children move out then the parents have to determine what to do with the house, sell it, rent it, make amends so the child moves back in. Having the children participate by making the housing payments to those owed directly creates more of an ownership mentality for them and makes it easier to transition the home later on. The risk here for the children is the parents still control the property and can sell it without the children’s consent—unless the children are on title.
In my opinion, this is the least desirable way to help your children obtain home ownership.
SCENARIO TWO: A more desirable way to assist your children in the purchase of their own home is to co-sign for them on their mortgage application. Most loan programs will allow family members to co-sign for mortgages for owner occupied purposes—what we call “non-occupant co-borrowers.” In this scenario, the child cannot qualify for the mortgage, usually because their debt-to-income ratio is too high. Depending on the parent’s total income and debt obligations, including their own housing payment, they may be able to co-sign for their child and enable loan qualifying. The parents would be on the mortgage and on title to the property.
The parents are still liable for the loan payment, as they are in Scenario One above, however the child is also responsible and have a lot more control over the situation than they do in Scenario One. Some parents are concerned, rightfully, how their being on the loan may impact their ability to get a loan in the future; most loan programs have a guideline for such a situation, known as “contingent liability.” If the parents can show the child has made the last twelve payments in a timely fashion then most mortgage programs will not count the payment for their qualifying.
In the future if it makes sense for the child to refinance then it is easier in this scenario than Scenario One as they are on title and on the loan so there is less to verify for the lender.
SCENARIO THREE: Show me the money! Or in this scenario, show your kids the money. As mentioned in the Weekly Rate & Market Update on March 1st, lack of funds for down payment is the primary reason most families wait to purchase a home. Many parents help their children purchase their homes by giving them the funds needed for down payment and/or closing costs. Many families have the income to qualify for a mortgage, but are short in the amount of cash they need. Enter Mom and Dad who can provide a gift for the funds required.
The process is simple, we only need three items for this scenario: proof of funds to gift, proof funds have transferred to the child, a gift letter signed by donor and recipient.
There are loan programs that allow for gift funds for all of the down payment and closing costs, some programs as low as 3.5% down, other five or ten percent.
If the resources are available this is the easiest scenario to enable parental assistance, and the one that has no long-term consequences other than not having those funds available for the parents own use in the future.
After some conversation, this was the route that Andy and his wife have taken to help their daughter and son in-law purchase their new home in Pennsylvania.
If you are considering helping your children with the purchase of their home in the future, or you are wanting to purchase a home but may need parental assistance, please call me so we can develop a strategy that works the best for everyone in the family and results in that homeownership.
Have a question? Ask me!
Fed says what? After spending part of 2017 and all of 2018 broadcasting they would very likely, extremely likely, raise their Federal Funds Rate three times in 2019. Over the past few months three rate increases became less likely based on the minutes from the Fed’s meetings and this week three increases become not likely at all and even one may not happen. This news was very interest rate friendly.
Existing home sales had their biggest one month increase nationally since 2015 in February. The National Association of Realtors reported today that nationwide sales of existing homes were up 11.8% from January, a huge jump for one month. Total sales were down 1.8% from last February per the report and the nationwide median price of $249,500 was up 3.8% from a year ago. The market is still being held back by lack of first time buyers, in recent history first timers have been about 40% of the market and last month only 32% of homes closed were first time buyers. Over all the news is slightly negative for mortgage rates as higher sales puts more demand on mortgages and shows signs of positive economic news.
Closer to home for most readers, data for California and Southern California was a bit mixed. Statewide total sales also eclipsed 11% for the month, with sales 11.3% higher than January, but down 5.6% from last February. The median price across the state dropped 0.6% for the month and showed a 2.2% increase over the past twelve months with a price of $534,140. The two biggest counties in Southern California showed no consistency between them. Median prices were down in both counties from January, with LA County down 4.3% and Orange County down 0.5%. LA’s median price of $541,390 was up 2.7% from last February, while Orange County’s $792,500 price was down 1.6% for the year. Total sales in Los Angeles Country dropped 2.5% from the prior month and 10.9% from 2018, while the OC saw total sales increase for the month by 1.0% but a sharp drop of 16.5% from last February.
What does this mean? Year over year sales being down sharply in the region are obviously a concern for long term real estate activity, however prices are holding fairly well against the declining sales. With rates looking to stay low for some time the housing market, in my opinion, should move sideways with slight ups and downs neighborhood by neighborhood, city by city, county by county, for the year. Again, in my opinion.
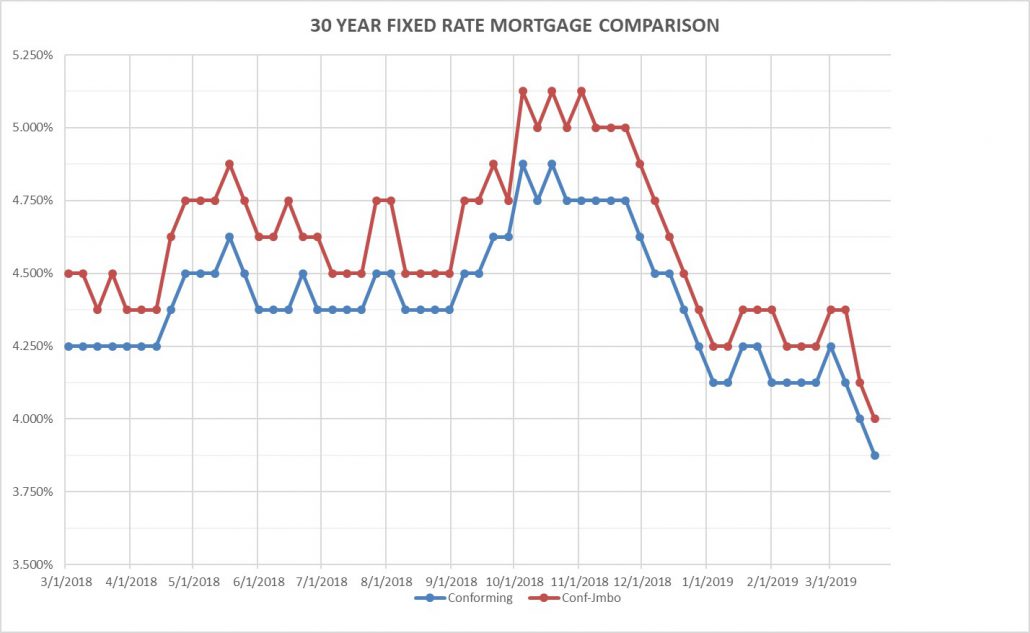
Rates for Friday March 22, 2019: With the Federal Reserve news this week showing a lack of interest to raise interest rates in 2019 rates improved this week and we see the conforming rate drop for the third week in a row and the 30 year conforming rate dipping below 4% for the first time since the second week of January last year when it climbed to 4%. Time for a rate check? Call me.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year high-balance conforming 4.00 % Down 0.125%
30 year conforming 3.875% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
College athletes in major sports are provided a scholarship that includes tuition, room, board and stipends for books and incidentals. The NCAA Men’s Basketball Tournament tipped off this week with teams from 68 colleges competing in a one-and-done contest to determine the national champion, also known as March Madness for the many games that are decided on the final shot and small schools knocking big schools out of the contest.
In 2016 the NCAA signed an eight year contract with some networks that will be worth $1.1 billion per year.
This year it is estimate that one-in-five Americans will participate in some type of pool or bracket challenge for the tournament. According to the American Gaming Association these pools will have about $4.6 billion in wagers on the line. Since the Supreme Court ruled that the it was unconstitutional for Congress to prohibit sports betting several states have passed laws allowing sports betting, as a result of all the new legal betting opportunities in around 25 states it is estimated that almost $4 billion will be bet on the games—40% more than on the Super Bowl in February.
Excluding ticket sales, merchandising and other revenue, the gambling and television revenues total almost $10 billion for the tournament which is held in ten days over three weeks.
But at least the players get a chance to go to college for free.
I have Duke beating North Carolina in the final game. Surprisingly, given the great history of both these teams and their intense rivalry, they have never met in the tournament.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog