Cautionary tale about student debt relief

Question of the week:  Why were local and federal law enforcement at your office complex last week?

 Answer:  Today the Question of the Week is meant to be a bit sensationalist and provocative to entice you so I can give everyone a warning and head’s up, for themselves and family members.

Last Wednesday, as I was leaving for my weekly meeting of the Rotary Club of Long Beach, I passed on my way down the stairs to the parking lot an Orange County Sherriff’s Deputy and a man in a suit who were headed up. The Deputy’s Sherriff’s Department SUV was parked in front of the building and in the parking lot was another marked SUV and a few generic sedans with government plates. I asked the Deputy if I could help him find an office and he replied, “we have it under control sir.”

Since they were standing on the outside walkway outside our office I was a bit curious, wondering if someone in our company was being served for some reason, and called a colleague asking him to let me know if there was anything I needed to know and continued to Rotary.

When I returned there were still some vehicles in the parking lot that we obviously government issue. I immediately went to our bullpen area and asked, “what was that all about?”

Evidently the company, Arete Financial, with offices next to us had been raided by the law enforcement officers. I was told employees were leaving the office one at a time, some with and some without boxes with what was likely their personal effects.

The raid was due to a suit filed in U.S. District Court by the Federal Trade Commission against the company for multiple counts of fraud and deceit. Essentially the company would market via telemarketing, mail and the internet student loan relief. Per the complaint, customers would pay an upfront fee for services, then would also pay monthly payments to the company that were intended to go to their student loan companies after Arete negotiated lower payments and/or balances. Except the payments in many, or most, instances never made it past the company’s own bank accounts and owners. The estimated total they collected is $43 million.

I write about this week because many of the readers of the WR&MU have student loans, have children who have, or will have, student loans, or have other family members or co-workers with student loans. I want to make sure that there is hyper-awareness in the market place about companies soliciting debt-relief services, not just for student loans but consumer debt such as credit cards as well. Some of these companies are legitimate and make honest efforts to assist their clientele, some are not and prey on individuals facing stress and anxiety of their debt and the challenges they may have making payments.

It is easy for us to understand the appeal for consolidating student loans. When we pull credit reports for clients who have financed most of their college costs we see multiple student loan accounts. If someone went to a school on the quarter system and received federal loans as well as obtained private lending from a bank, they could have two loans per semester on their credit report; one for each quarter from both loan sources for a total of up to twenty-four different accounts. It can get confusing as to what is owed on what loan and the statements they receive from some lenders are not the easiest to read. It often makes sense to consolidate all their loans into one new loan and payment.

My advice to clients in this situation is to do some homework and investigate traditional lenders to see what options they have for student loan consolidation. There are many legitimate banks and lenders that can assist with consolidating student loans with very good rates and terms for repayment that can reduce your payments.

As for complete relief, there are circumstances whereby federal student loans may be reduced or eliminated. Someone who meets these circumstances can work directly with the Department of Education, for free, to apply and obtain the relief—DO NOT go to a debt relief company for this service. Many will charge to see if you are eligible and charge to complete paperwork that is supplied by the Department of Education.

We saw many companies pop-up after the 2008 market meltdowns who were advertising “consulting” services to assist homeowners in negotiating short-sales, forbearances or other relief from their mortgages who have owners that later went to jail and/or paid huge fines for fraud and deceit. Today, instead of targeting underwater homeowners many “debt relief” companies are targeting young adults with student loans.

Today student loan debt is over one trillion dollars and growing, which creates a huge market for those looking to take advantage of others for their own financial gain. I have likened the extraordinary increase in college tuitions to the increase in the housing bubble prior to its popping in 2008, cheap money is offered to those who want something of which there is a limited quantity which forces prices up due to supply and demand. The target market for defrauding debtors with student loans is growing and it is a numbers game for the crooks, more calls made equates to more potential victims.

An aspect that makes it difficult to assist someone who may be vulnerable to a credit scam is that most people who are in financial trouble to do not talk about it to parents, siblings, friends, co-workers or even spouses. They may be embarrassed about having financial challenges, or feel the situation is too private and intimate to speak to others. Because of this I encourage sharing information about debt relief scams and fraud, not in a manner suggesting someone may be in trouble but as a heads up to be very wary if considering consolidating debt.

Clichés become clichés because there is a lot of truth in them, one is, “if it seems too good to be true it usually is not true.” This is very true with offers to assist you with reducing loan payments or eliminating debt.

Here is the link to the Federal Trade Commission website describing their action against Arete Financial.

For those interested in more of the details, here is a link to the complaint filed in Federal Court—where you can read how the company obtained powers of attorney and used them to change email addresses, log-in names and passwords so victims could not sign into their student loan accounts to see what was happening.

If you, or someone you know, has any questions about debt consolidation, credit issues or options please contact me and I will see if I am able to assist.

Have a question? Ask me!

After last week’s lack significant economic data, this week we have had several important data releases. Price data was released this week, with both the Consumer and Producer Price indices both jumped 0.4% in October, the highest in seven and six months respectively. The increase was mainly due to higher gasoline prices in the month. Regular readers of the WR&MU know that when looking at prices the “core” rate (strips out food and energy from the data) is the rate the Fed and other use to gauge inflation. In October, the core CPI rate was up 0.2% and the year over year rate was up 2.3%, down from 2.4% in September. Overall the news is mortgage rate friendly as it shows an absence of inflation to the extent that rates should increase.

Rates will be on hold, was the message from Federal Reserve Chairman Jerome Powell this week. Last year at this time the sentiment was the Fed would increase rates two to three times in 2019 after it raised rate four times in 2018 for a total of a 1% increase. As we got into the year the pundits and hand-wringers kept up a concern that the economy was headed to a recession by the end of the year and the sentiment was that the Fed would lower rates at least three times by the end of the year—the Fed has lowered rates three times for a total of a 0.75% decrease. Powell now says that absent significant decline in the economy. Powell stated the Fed’s outlook, “of moderate economic growth, a strong labor market and near our 2% objective” supports having a neutral policy on rates. The statement was neutral for rates since it called for the status quo.

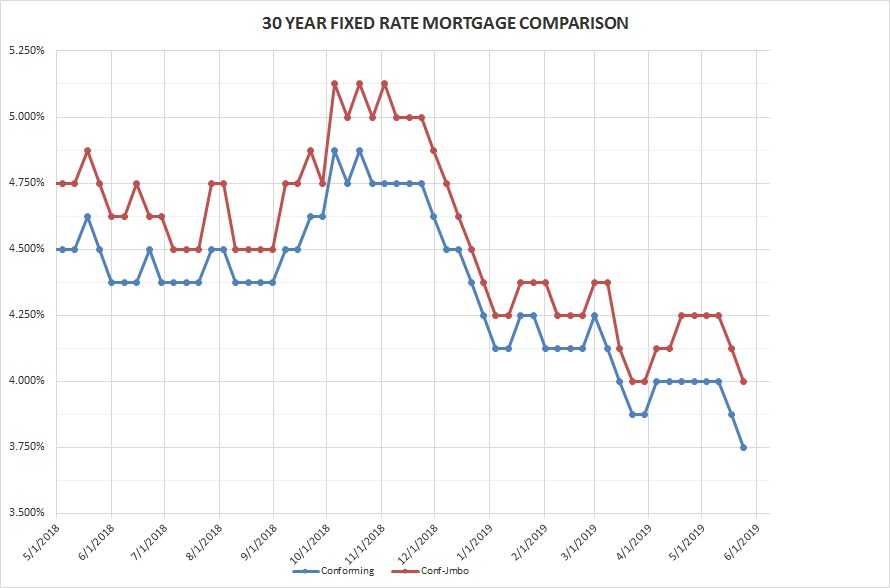
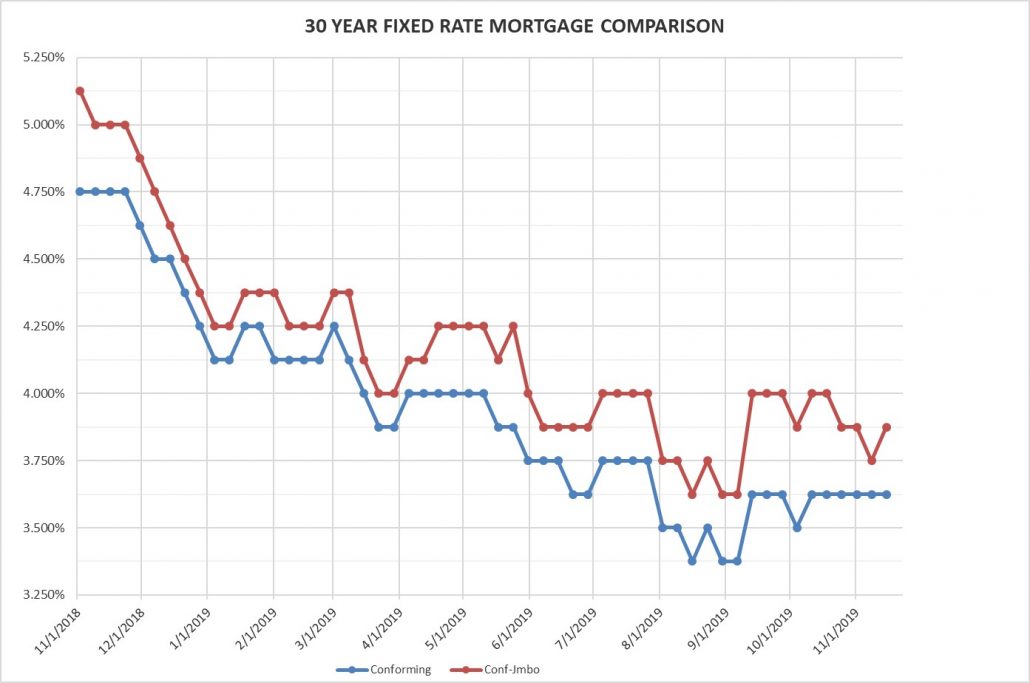
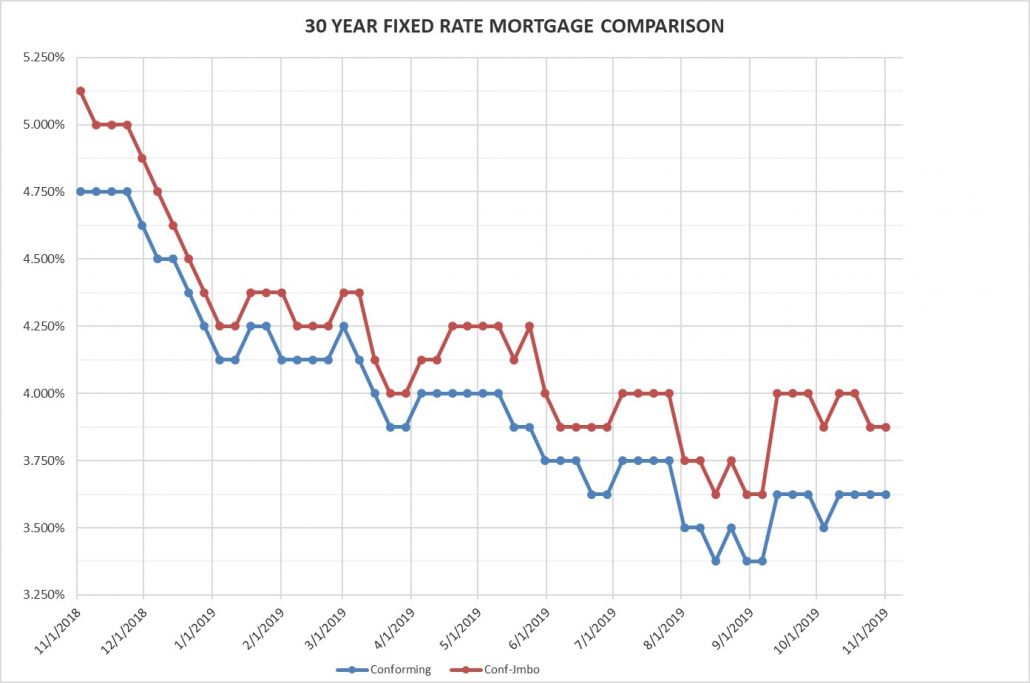
Rates for Friday November 15, 2019: While the Fed announces steady rates that they control, in the open market there is a sense of a bit less stability. Stock markets continue to set new highs, but for how long and if/when there is a correction will funds flow into fixed rate investments and push rates lower? Maybe. For now, the 30 year conforming rate extends its Friday-to-Friday streak of no change to five weeks and the high-balance conforming rate bounces off its nine week low. There is more risk for loss should rates increase then the potential benefit from a chance rates drop further—do the math and you will likely want to lock your rate when possible.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.625%     Flat

30 year high-balance conforming                   3.875%      Up 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Recognizing long ago what I strongly feel is false inflation in the college and university tuition markets, I have been waiting, and very much hoping from about ten years ago when the costs really began to jump, for the tuition bubble to pop. I contend that the increase funds are not going into classrooms to better educate the students than the education prior generations of students received. If a school wants to build a fancy new science lab, or a new school of sociology, they do not use tuition funds, but undergo tremendous capital campaigns. Most colleges with the highest tuitions are sitting on endowments of billions of dollars, and continue to raise tuitions. Growing in proportion to tuitions have been the size of the bureaucracies and administrations (redundant?) on campuses by adding new “Deans of ____.”

Part of the issue is the mantra that every kid needs to go to college. Many kids wash out of college very early on because it is not for them. Freshman dropout rates are growing exponentially, and not because of the costs so much as not being able to handle the workloads, independence and not being interested in what they are supposed to be learning. This increases the number of kids applying, which in turn enables the schools to raise tuitions. I have a lot of sympathy for these students who feel forced to go to college so as not to have the stigma as a non-college student, but at the same time wish their advisors, mentors and others who have influence encourage them to attend a local community college or state school to get their feet wet instead of tossing them into a foreign environment with highly competitive kids and academics.

As the parent of a student in her sophomore year in college and a student in her senior year of high school applying to colleges, I am pretty familiar with the financial challenges of students and families and the somewhat hypocritical position of colleges continually soliciting billions of dollars a year across the country while increasing the cost of their product with no tangible benefit to their clients, the students.

I listen to podcasts and one of my favorites is Malcom Gladwell’s “Revisionist History.” He had two excellent shows on college costs and financing, the first is “Food Fight,” which explores how two similar colleges use their funds differently, and the other is “My Little Hundred Million,” in which he looks at one man’s donation that altered a school’s history and compares it to other schools raising money just because they can. I encourage you to listen to them both (and all of his podcasts!)

Off my soap box…..for this week!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Can I get a mortgage if my parents co-sign because of my poor credit?

Question of the week:  Can I get a mortgage if my parents co-sign because of my poor credit?

Answer: Over the past year, years really, we have had several Questions of the Week that deal with credit reports; What can I do about my credit, Should we consolidate our credit, Why did my credit score drop, and How do inquiries impact my credit, are just a few of them.

What we have not addressed in several years is what if you have poor credit and want to buy a home. The question of if your parents, or another connected party, can help you purchase your new home if you have poor credit.

The quick answer is, No. Of the three factors that are considered for a borrower in loan qualifying, income, credit and cash to close, credit is the one area that outside assistance is not able to enable qualifying.

Mortgage underwriting guidelines state that the lowest middle credit score of all borrowers on an application is the score that will be used for qualifying and pricing the loan. For instance, Angela and Adam are recently married and wish to purchase a home. Angela’s credit scores from the three major credit agencies (Experian, TransUnion and Equifax) are 763, 744 and 768; her middle score is 763. Adam had a few issues in his past and his middle scores are 689, 703 and 679; his middle score is 689. Since Adam’s middle score is the lowest of the two, the score for the file is 689.

Some programs require a minimum score of 700 to be eligible. If one of these programs were the one Angela and Adam wanted for their home purchase or refinance they would not be eligible for the program. “Dennis, what can we do? Can my parents co-sign for us?”

If you are unable to qualify because your income is low, we can add a “non-occupant co-borrower” to your mortgage application to enable you to qualify. If you are short funds to close you can get a documented gift from your parents or other connected party to qualify. If you have a credit score that is too low for the loan program for which you are applying the only way you can qualify for that program is to increase your credit score.

All is not lost. There are different options that may be available to Angela and Adam to achieve their home purchase or refinance goal.

One option is to look at Adam’s credit report and see if there is something that can be done to increase his score. Perhaps paying an account down, or off, may raise the score the eleven or more points needed; or sometimes opening an account will get the extra points needed. Not all credit reports are the same and the composite data that creates the credit score is influenced by many, many factors. Depending on what is on the report it may be fairly easy to increase the score.

A second option is to see if there is another program that may enable Angela and Adam to achieve their goal. While more expensive because of mortgage insurance, FHA mortgages are often used for clients with lower credit scores because their minimum scores for different programs are a lot lower than those for conventional and most jumbo programs. The decision factor in this case is the trade-off between the current higher mortgage cost due to the mortgage insurance versus the potential higher cost if waiting to purchase or refinance due to higher home values and/or rates. It is not an unusual reaction to want to have the mortgage product with the lower costs, however that product is not available to you, a change in mindset may be the most beneficial to you in the long term as you are able to purchase your home today.

A third option is that perhaps mom and dad can co-sign—with Angela. Depending on the ability of everyone involved and the mortgage program, by dropping Adam from the mortgage and adding mom and dad as co-signers the transaction may be able to continue.  

One other option we have employed is for mom and dad to purchase the property as an investment property. Angela and Adam move in and make all the payments for the mortgage, property taxes and insurance. In the future, when Adam’s credit scores are better, depending on the rates and the market Angela and Adam may want to refinance to put the home and mortgage in their own name.

Since a low credit score cannot be cured with adding co-borrowers, it is advisable for you to know what is on your report and address any issues that are negatively impacting your credit as soon as you can. We have plenty of experience analyzing credit reports and assisting borrowers increase their scores.  Sometimes this can happen in a short period of time, sometimes not. For the latter, I always bring up a client from more than twenty years ago, Yvonne.

Yvonne and her husband wanted to purchase their home but had undergone some economic traumas that resulted in low credit scores. Yvonne was determined to own her own home and for almost two years she worked to improve their credit. She would constantly check in with me and we would review her accounts and her plan, checking her credit report every 5-6 months to see where they stood. Finally, the day came when their credit was rehabilitated and they purchased their home. When I called to tell Yvonne her loan had funded and she was going to be a homeowner she was not the only one on the call with a catch in her throat and blurry eyes.

Poor credit and low scores can delay your home ownership, but do not let it prevent it. Be like Yvonne and tackle the problem as soon as you can.

In regard to parents co-signing, in March we answered, “Should we co-sign for our son or daughter’s home purchase.”

Have a question? Ask me!

This was a very busy week for market impacting news and data. In order of the announcements this week and positive or negative impact on rates:

One year after hitting a peak, consumer confidence in October was down slightly from September, but by less than prior months. Over the past year the consumer confidence chart looks like a ride at Knott’s Berry Farm. The valleys have been getting higher since January and the trend line looks like the next trend is back up. The over-riding news from the report is that consumers are reasonably confident and holiday spending should not be curtailed. Over all the news is somewhat negative for rates as high consumer confidence can lead to high consumer spending, which is about 65-70% of our economy, which leads to economic growth.

Consumer confidence and spending resulted in another positive quarter of growth for the Gross Domestic Product. The 3rd quarter increase of 1.9% was down a peg from the 2nd quarter growth, but higher than the 1.6% that was expected from most of the experts. Inside the report, the spending by consumers in the quarter more than counter-balanced a large drop in business investment caused by a drop in oil prices and the trade conflict with China. Showing stronger than expected growth, despite consumer spending dropping from the extremely strong 4.6% growth in the 2nd quarter to 2.9% in the 3rd quarter, plus residential housing investments increasing for the first time in five years, the GDP data is negative for mortgage rates.

Following the GDP data release was the announcement from the Fed that it cut its benchmark interest rate by 0.25%. This move was expected and on its own had not impact on mortgage rates. In making the rate announcement the Fed used its normal Fed-Speak to announce that it would likely take a pause before enacting any more rate cuts. Some investors have expected more rate cuts in the near future and a pause puts them on the wrong side of the market. From their announcement, it appears the Fed is content with the current path on rates as they forecast continued moderate growth in the economy, a continuing strong labor market and inflation very near its 2% target. Overall the news is a bit rate negative due to the Fed taking off the table the certainty of another rate increase and the more positive message than it has supplied in prior announcements.

Thursday, it was back to consumers as the Commerce Department released data for September on consumer spending, personal income and inflation. Consumer spending increased for the month at a mundane 0.2% rate, down from August’s dull 0.3% growth. While dull and mundane, September was the seventh month in a row of increased spending. The increase in spending was supported by higher earnings as incomes rose 0.3% in September, reflecting the strongest labor market in fifty years. With spending increasing at a slower pace than incomes it is not surprise that the savings rate increased to 8.3%, near post-recession highs and showing that while consumers are spending steadily they are doing so within budgets that enable saving as well—something that was absent prior to the Great Recession. Because the growth in spending and incomes have been moderate the pressure on prices has been the same, prices have increased only 1.3% from September 2018, the matching February as the lowest since 2016. This news is neutral for mortgage rates as it reflects an economy that is not booming nor busting but chugging along.

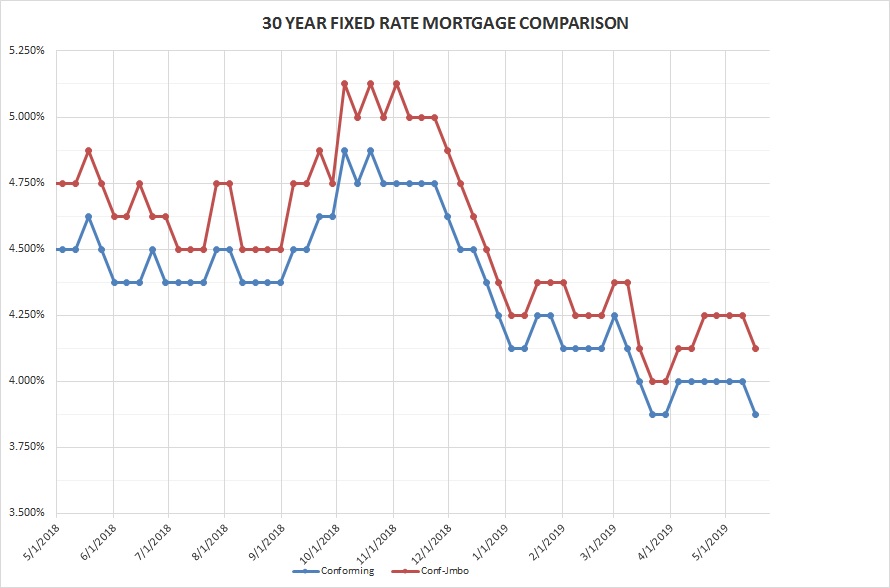
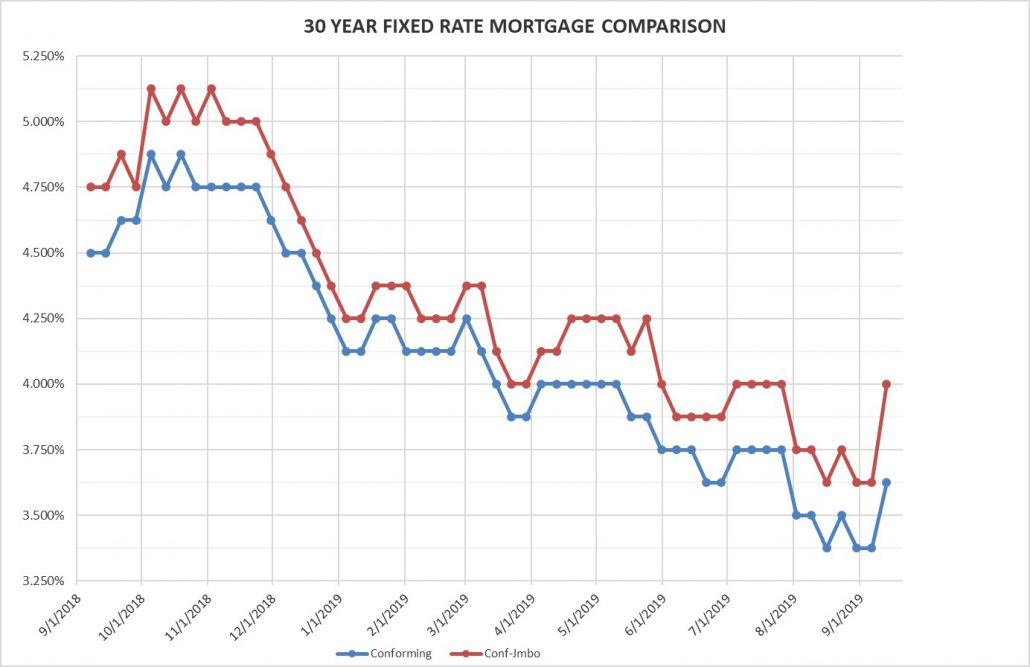
Rates for Friday November 1, 2019: Last week there was an error in the rate numbers below, the chart was correct but not the numbers, they did not reflect the 0.125% drop in the high-balance rate from the prior week. This week the high-balance rate further compresses to the conforming rate, which is flat this week. Following all the economic news reported today I was expecting rates to be a bit higher. We may be nearing the end of a cycle so a bump next week would not surprise me.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.625%     Flat

30 year high-balance conforming                    3.75%      Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Do not forget to turn your clocks back before you go to sleep on Saturday night or you’ll be early for church…or is it late? I can never keep that part straight.

If you live anywhere in Southern California you have likely smelled smoke over the past few days. Unfortunately, it is that time of year again where too many of our fellow Californians are experiencing trauma and tragedy due to major fires. Here is what has become a semi-annual link I provide for those who are wanting to help: Donate to the Red Cross The Red Cross does what no other entity, public, private or non-profit, does when it comes to disaster relief and assistance, every little bit helps. If everyone who receives this Weekly Rate & Market Update donates just $10, more than $6000 will be raised to assist with food, blankets and housing. Take a minute and click-it!

I was half-right last Friday, the Washington Nationals did win their first World Series ever, but it took more games than I thought. How amazing that every game was won by the visiting team!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

Did I miss it; did I miss the bottom for rates?

Question of the week:  Did I miss it; did I miss the rates bottom?

Answer:  Maybe.

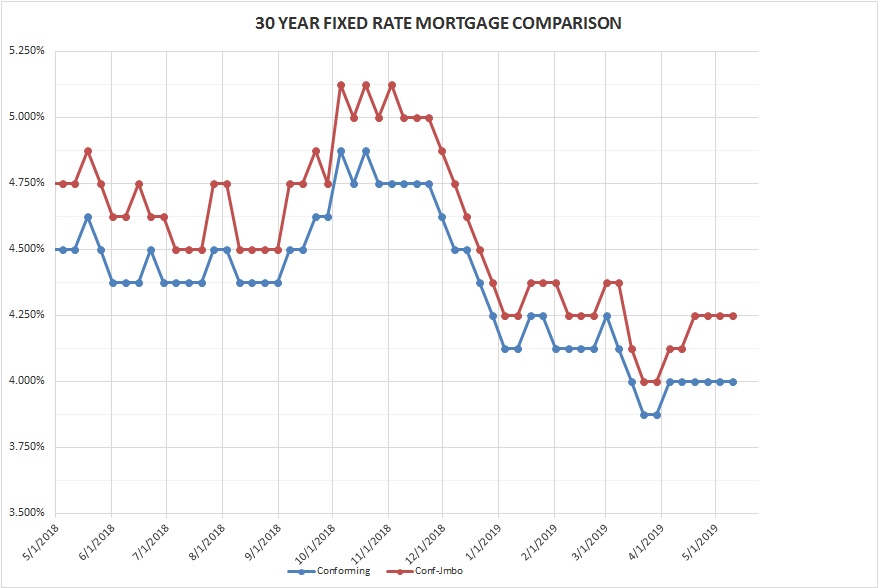
As you will see below rates this week went up the most in one week since the week ending October 5, 2018. When rates climbed at the end of last September they ended up peaking for about a month before we had a long slide down (down every Friday for five of six weeks).

Rate increases this sudden and this high are rare but they do happen. Why? Usually rates jump up on very positive economic news, political news, or a geopolitical event. This week the trigger for the rate jump appears to be the nice-nice talk between China and the United States on tariffs and trade agreements. This made investors positive about American businesses and removal of a drag on the economy and they left the safety of bonds and mortgages and bought equities, i.e. stocks in corporations.

Further pushing rates higher was today’s news that August was a very strong month for consumer spending as retail sales climbed 0.4% with a very large 1.8% increase in vehicle purchases. Consumer spending is 65-70% of our economy and if the cash registers continue to ring at a growing pace the economy will grow as well.

Also in the reports today was that hourly earnings are up 3.2% year over year, well above inflation which provides support for continued consumer spending.

All this good news in negative for lower rates for several reasons, primarily they show an economy that would be further away from the recession many pundits and media outlets have been used to fill the airwaves, interwebs and newsprint. Secondly, the potential of the trade war with China cooling down adds more support to pushing out any possible recession even further.

Currently the mortgage markets have priced in a rate cut of 0.25% by the Federal Reserve when it Open Market Committee meets, what is uncertain is whether there will be more rate cuts later this year. The economic and political news is making further cuts somewhat more unlikely—which investors have also been reacting to as some have been making decisions based on at least one further cut after next week.

If, for some reason the Fed does not cut its benchmark rate next week be prepared for another spike in rates.

So, did you miss the bottom? For the short term it appears that it is likely you did. For the medium term the answer is unknown as the current spike could be a sell-off to protect profits, in which case they will slowly move back to bonds when they feel equity markets are peaking, or near peaking.

All that said, even if you missed the bottom rates are really, really good. The current rates are where they were in July, which were near multi-year lows. If you have been considering making a purchase or refinance for the bottom of the market, you may want to consider doing so from the perspective of rates bouncing off what may have been the bottom.

Have a question? Ask me!

Typically this section of the WR&MU covers what is happening in the economy that impacts rates, today that was the first section!

Rates for Friday September 1, 2019: We will see over the next week or two if the spike in rates is a blip or a trend. I suggest not floating your rate and locking when you are able to avoid further rate loss should rates bump up more.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.625%     Up 0.25%

30 year high-balance conforming                     4.00%       Up 0.375%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Thank you to everyone who sent happy anniversary issues to us last week. We had a great time scheduling nothing to do every day and knocking that important item off our to-do lists!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Should we consolidate our credit?

Question of the week:  Should we consolidate our credit?

Answer:  With interest rates so low this is a question many people are asking themselves, and me. Like many financial questions there is no uniform answer, and possibly no “right” answer. If you are asking this question the best course of action is to try to make an objective analysis and do the math to determine whether you feel consolidating your credit is right for you and your family.

What does it mean to “consolidate credit?” In its simplest form, consolidating credit is paying off existing credit obligations with an existing, or new, credit account. For instance, you have likely received solicitations in the mail from a credit card company offering you a very low rate of interest, possibly zero percent, for twelve months if you transfer balances from other credit cards. If you make the transfers and pay off other credit card accounts you are consolidating your credit obligations from several accounts to one account.

Here is how the math may look. You have three credit card accounts with five to eight thousand dollars one each account, let’s say the total owed is $20,000. The average rate on credit cards is about 15%. If your accounts are average you are paying $250 per month in interest on your cards. Your minimum payments are probably $400 per month for all the cards, which means you are only paying down $150 per month on the cards. If you transfer the $20,000 to a zero percent account and make the same $400 per month payment you will lower the balance on the account by $4800 in twelve months, versus only $1800 if you had maintained your cards and payment pattern.

Of course, after the initial twelve-month period the interest rate will go up and you will likely be paying 15%, or more, in interest—just on a lower balance.

I am asked the “should we consolidate our credit” question with another objective in mind, the question is really, “should we refinance our home and pull out equity to pay off other debt?”

Using a mortgage for debt consolidation is known as a “cash-out refinance.” Using a cash-out refinance to consolidate debt can the math a bit more complicated.

The most common debt consolidation with a refinance is to pay-off a Home Equity Line of Credit (HELOC) or other second mortgage. Typically, this type of refinance is undergone to fix the rate on a HELOC and force amortization of the balance; most HELOCs have a minimum payment of interest only and therefore many/most homeowners with HELOCs do not pay much, if any, principle on the debt. It us usually the case when a HELOC is refinanced into a new primary mortgage that the mortgage payment will increase, this is in part due to the amortization.

When dealing with consumer debt such as credit cards, student loans, auto loans or other non-mortgage debt, a big factor is the extension of the debt being paid off. Most of these credit obligations have installment periods of less than five to seven years, and while credit card balances can last seemingly forever, if no balance is added making the minimum payments will generally pay off the card within ten years.

If consumer debt is rolled into a new cash-out mortgage transaction  consider that most mortgages are thirty year mortgages, so if you do consolidate credit debt you are extending that debt to a thirty year payment plan—unless you sell the home before the mortgage is paid off.

Depending on your situation a cash-out refinance to consolidate debt may make financial sense for you and your family.

Consider a family that has owned their home for ten years and owe $250,000 on their mortgage with a 3.75% interest rate and their current home value is $525,000. They did some remodeling on their home a few years ago so in addition to the mortgage they have a HELOC with a $100,000 balance and the rate is Prime + 1%, or 6.25%. They also had a medical emergency with a child and needed to help a parent with relocating and have accumulated about $30,000 in credit debt they are having a difficult time paying down.

Their total payments are about $1400 for the mortgage, $525 for the interest on the HELOC and $600 for the credit cards. They have two car payments totaling $700 per month but those will be paid off within the year and will not be part of any consolidation plan.

The balances being considered for being paid off total $380,000 with payments of $2525 per month.

When considering interest rates long-term readers of the WR&MU know that two major factors are the purpose of the loan and the Loan-To-Value (LTV), which is the loan amount divided by the value of the property. The lower the LTV the better the rate, to a certain level. Purchases and rate and term refinances (refinancing just to lower the rate and payment with no equity being pulled out of the property) have better rates and pricing than a cash-out refinance*.

In this case we have a cash-out refinance at 72% loan to value. Let’s assuming the market rate for this loan scenario is 4%, which would result in a monthly payment of about $1815 per month.

With monthly savings of $710 per month it seems to make sense to proceed with the transaction and pay off the debts with a new mortgage. But is this the right decision?

What if instead of paying off the credit card debt just the HELOC was paid off with a new mortgage? Now the mortgage balance is $30,000 less at $350,000 and the monthly payment will be $1670 per month, a savings of $855 per month.

With this scenario, instead of putting revolving credit into a thirty year loan the savings from consolidating the HELOC into a new mortgage are used to pay down/off the credit cards.

If the family keeps their total monthly credit payments, absent the auto loans, the same at $2525 per month, pay $1670 on the new mortgage, they have $855 per month to pay on the credit cards. Instead of paying about $2700 per year in principle on their credit cards they will be paying almost $5800 per year—cutting in half the amount of time to pay them off.

This is just one scenario out of many that we can, and do, run for homeowners who feel their debt is becoming more and more challenging and may be able to take advantage of the current low rates to provide some financial relief and monthly savings.

A few points I need to make in conclusion. First, I do not advocate using one’s equity in their home to finance spending sprees and living above one’s means. People do get in trouble and we can help them out, but I always council that if your credit situation has gotten such that you need to refinance your home to pay off accounts that were used for trips, clothes, eating out, etc then you need to change your spending habits and lifestyle to leave within your means.

Second, make sure you have a plan for the money you will be saving every month. Put it in savings, start an investment account, put the money in 529 college plan accounts for your children, increase your retirement contributions. Have a plan.

*If your loan amount will be over the Fannie Mae/Freddie Mac conforming loan limit of $484,350 then the difference in rate between a purchase/rate-term refinance and a cash-out refinance will be a lot more than the difference for loan amounts at or below $484,350. The “high-balance” conforming (loan limit of $726,525 in many Southern California areas) and jumbo loan programs have fairly significant price add-ons for cash-out refinances, especially those with higher LTV’s. Call me for details.

If you are interested in running “what-if” scenarios to see what your options are for consolidating a HELOC and/or other debt please give me a call and we can do the math for various options. You may be fine with how you are currently set up regarding debt and we can put together a plan to help you payoff some of your debt without having to tap into your equity.

Have a question? Ask me!

Over the last month or so I have gone on some mini-rants about the Fed lowering interest rates to boost an economy that I, and others, see as not needing a boost. The Fed got a little “told-you-so” this week at the Producer Price Index (prices wholesalers pay for goods and services) was up only 0.2% in July and 1.7% from July 2018. The “core” price index (food and energy costs are taken out of the calculation due to their volatility) declined in July by 0.1%. This news is moderately positive for rates, we will see next week when consumer price data is released, and supports those in the Fed who feel soft prices can drag down the economy. I remain unconvinced.

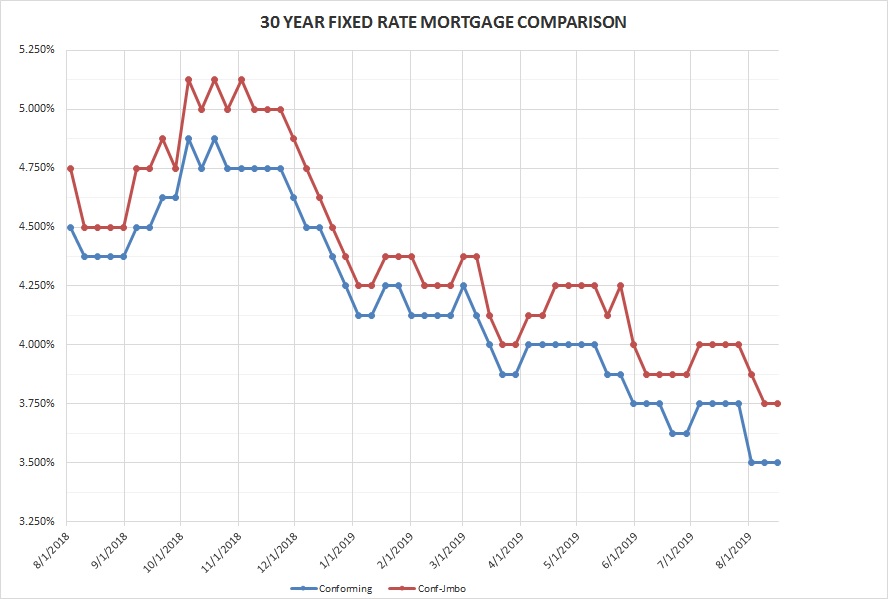
Rates for Friday August 9, 2019: After a price spike on Monday that pushed rates down a bit from last Friday rates bounced back to where we closed a week ago. It appears that we are at the bottom of the most recent range of rates, which means lower rates will be hard to come by—if at all—in the short term, or medium, or long.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.50%     Flat

30 year high-balance conforming                    3.75%    Flat      

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Well it was a lot easier writing the Weekly Rate & Market Update this week from a desk than it was from the passenger seat of a Hyundai Tuscon last week! Leslie and I had a great trip traveling to the Midwest and back and are glad to be home with both of our girls. At least for the next few weeks before the eldest heads back to her sophomore year in Boston.

I hope you summer is going well!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
What has the biggest impact on mortgage rates?

Question of the week:  What has the biggest impact on mortgage rates?

Answer:  News.

Political news, geo-political news and economic news impacts interest rates.

Mortgage rates are the result of investors either buying or selling fixed rate financial instruments—i.e. bonds and investments that behave like bonds such as long-term mortgages, which are bundled and sold as Mortgage Backed Securities (MBS). Interest rates move inversely to the price of the bond, or MBS. If more investors are selling MBS then prices will drop, which will push mortgage rates up; if more investors are purchasing MBS then prices will rise, which will push mortgage rates down.

What determines whether investors will be buying or selling? Extrapolation, anticipation, historical behavior, expectation and speculation. If you knew that a certain piece of news would benefit DCSmith Industries creating more sales and revenue, you would buy stock with the expectation the value of the stock would rise, increasing your investment. If after you own the stock there is some news expected to come out, or that has just come out, that would be detrimental to DCSmith Industries harming revenue you would sell the stock to retain your gains.

Investors do exactly that, except for fixed rate investments the information processed to anticipate whether prices should go up or down on bonds and MBS is different than the information processed to forecast future prices for individual companies. News is the currency of investors when it comes to fixed rate investment. And good news is bad and bad news is good when it comes to higher or lower rates.

Generally speaking, investors have two choices. They can trade equities (stocks in individual companies) or fixed rate instruments—bonds, mortgages. Historically, if equity markets are rising in price, fixed rate investments are dropping in price because investors sell their fixed rate investments to purchase the equities. The opposite is also true, if investors are selling equities they will generally take the sale proceeds and purchase fixed rate investments.

Good news creates a positive economic environment that boosts growth, and therefore sales and revenue of companies. With the expectations that the growth will create more value for private companies, with higher dividends and stock prices, investors will increase purchase of equities causing prices to increase.

This activity will reduce the demand for bond and MBS, causing prices to drop and rates to increase. Further influencing the lower demand for these investments is that strong economic growth historically has led to central banks, like the Federal Reserve, will increase their rates to slow growth and keep inflation in control. If they know this is the reaction of the central bank when economies are showing strong growth, investors will react by being even more reticent to buy or continue to hold bonds since their prices should drop, reducing their profits or creating losses. If they anticipate prices dropping further, why should they buy?

At some point the rates of return on the long-term fixed investments become high enough, therefore the prices low enough, that investors will start to return to these investments, slowing rate increases and potentially reversing the trend.

Bad news has the reverse effect. Individual company stocks and equity markets in generally are typically a lot more volatile than fixed rate investments. This creates a situation where prices in equity markets can swing wildly day-to-day, or even within one day, as we have seen several times in recent history. Extremely bad news, such as the outbreak of armed conflict, will create an environment known as “flight to quality.” “Quality” is synonymous with “fixed rate investments.” If you purchase an investment that will pay you 4% of the purchase price every year for ten, fifteen, thirty years, you know exactly what you will be receiving for your investment—there is almost no risk if it is backed by the United States Treasury. This is known as a quality investment. Conversely, purchasing stock in an individual company has risks, no matter the history or strength of the company. Think of major U.S. corporations that seemingly would never go out of business or see its value drop considerably, Blockbuster and Kodak did not adapt to technology and investors who held onto their stock lost a lot of money; Pan Am and Eastern were very strong world-wide brands that are no longer a brand of any kind except historical;  Woolworths, Arthur Anderson, Lehman Brothers…all these companies at one point, and for a long period of time, were leaders in their fields and industries but investors in these companies lost their investments—or most of them. Such is the risk to individual companies to bad economies, bad events and bad behavior by corporate leaders.

Because of the inherent risk in equities, when bad news occurs, or appears about to occur, we see the behavior of “flight to quality” with bond prices climbing and rates dropping.

Every week, in the section below this in the WR&MU I provide important news that impacts mortgage rates. If news is good, I comment the news is bad, or not good, for lower rates; if the news is not so good it should lead to lower rates. Historically, this has been the relationship between news and events and interest rates.

Historically is the key word as for the past several years our historical models and behavior have not always applied to the news, events and data that should put either upward or downward pressure on rates. As a result, despite the longest post-recession economic recovery in our nation’s history, rates are still significantly lower than they were pre-recession, and lower than several times during the recovery.

Just remember, if you are getting ready to borrow money for your new home, or to refinance your current one, bad news is good for you as it should lead to lower rates, and good news is bad. Selfishly, you are somewhat hopeful for some sort of bad news just before you lock your interest rate.

This explanation of what impacts mortgage rates and their rise or fall has been very general, there are many, many other issues, but I hope the generalization has been helpful.

Have a question? Ask me!

Good news or bad news? The first estimate of Gross Domestic Product growth for the second quarter of 2019 showed the economy grew at an annual pace of 2.1%. This growth was one-percent lower than the first quarter’s growth, but a bit higher than most economists predicted. Is the slowing growth good or bad news? On the one hand, it is good news as the quarter showed the spending by consumers in one quarter since 2017. On the other hand, it is not good news as holding down total economic growth was slowing in business growth as manufacturers and exporters invested less in fixed capital (buildings, tools, etc) as they took a wait-and-see approach to new investments as the trade talks and tension with China and other nations created uncertainty. Consumer spending is approximately 65-70% of our GDP, and the strong showing should have reflected growth of at least 3%; however the strong decline in business investment counter-acted the consumer—and appears to be the primary reason the Fed is looking to increase interest rates.

Rates for Friday July 26, 2019: The GDP news had little impact on rates today and we are flat for the third Friday in a row. If the Fed does raise interest rates next week, the increase is pretty much already priced into mortgage rates and the announcement should have little impact on rates.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.75%     Flat

30 year high-balance conforming                   4.00%     Flat     

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Our summer heat has finally arrived in Southern California, which means our pool is finally not too cold for me to take the occasional dip. I am no fan of cold water, which I consider to be anything below about 72-3 degrees. The “you’ll get used to it” line has never held true for me!

Stay cool, stay hydrated and make sure you have plentiful and fresh water for you pets.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
We are thinking of purchasing a home with solar panels, any concerns we should have?

Question of the week:  We are thinking of purchasing a home with solar panels, any concerns we should have?

Answer:  Concerns? Maybe. Awareness? Yes.

There are, to my knowledge, three different solar panel options for solar panels on a home in California: homeowner owns the panels, homeowner leases the panels, homeowner has panels and pays for the energy from a third party—a power purchase agreement (PPA).

Depending on the type option is on the home you are buying, or if you are selling, there are different concerns that a lender will have that will need to be satisfied for final loan approval.

Panels are purchased and owned by homeowner

If the solar panels are owned by the homeowner the lender has no concerns. Most solar panels are affixed to the property and their value can be included in the appraised value, if they are owned and not leased.

To be included in the value of the property, the appraiser needs to have comparable properties that have sold with solar panels and can show they have sold for a higher value than similar properties without solar panels. If you spend $20,000 on a solar system and put your home on the market, you should not expect the value of your home to be worth $20,000 more than a comparable home that has sold without the panels. Buying a home with solar panels that will have ownership transfer to you through the sale, i.e. they are not leased, you will very likely be purchasing the panels at a discount due to the limited value they add to the property compared the cost to purchase and install them.

Since they are owned by the homeowner and will be transferred to the new buyer, it is important that you check with your home owner’s insurance carrier to determine how the panels will be covered should they be damaged, and what type of damage is covered. As mentioned, it is likely the entire cost of the panels will not be added to the value of the home for sale, however if the need to be replaced due to severe damage how much of the replacement cost new is covered by your insurance? What is the impact on your deductible and premium?

Finally, when you own the solar power system you benefit from any tax breaks or other financial incentives available for installing the system.

Leased solar panels

When residential solar panels are leased from a third-party lenders concerns start to increase. With a leased solar energy contract the homeowner pays a fixed cost on a monthly basis and the provider guarantees the delivery of a certain amount of power on a monthly basis.

First, because they are not owned by the homeowner they are not considered in the value of the property by an appraiser. This policy is specifically mentioned in the Fannie Mae Seller’s Guide—the underwriting Bible followed by most loan programs. 

Second, because a third party owns, and therefore has significant control, over the panels, which are affixed to the lender’s collateral, there are several items in the lease concerning liability, damage and removal of the panels that must meet the lender’s guidelines. Essentially, the lease must state that the company that owns the panel is liable for any damage that occurs through maintenance or removal of panels.

Third, the buyer must qualify for the lease payment unless certain conditions are spelled out in the lease regarding fixed cost of the energy provided and guarantees as to how much power will be provided.

Fourth, the property must have access to an alternative source of electricity, i.e. the local provider for the community such as Southern California Edison or PG&E, etc.

Fifth, the company owning the solar panels is not named as a loss payee on the homeowner’s insurance policy. If the solar company requires the homeowner provide insurance it is generally on a separate policy from the master policy.

Regarding the sale of a home with leased solar panels, the home buyer will have to be approved by the company that holds the lease to assume the remaining terms of the contract. This approval process typically has a cost that can be negotiated between the buyer and seller to see who will pay the fee. The fee is paid upfront, before the approval is generated.

If there is time left on the lease and the buyer does not like the contract and wants it discontinued before purchasing the property there will be a cost to the owner to cancel the lease. Usually this cost is the remaining value of the contract, if the lease is three years into a fifteen year lease the buyout is twelve years of payments. The solar company will also need to remove the panels and before closing the buyer will need to ensure the panels were removed, any damage caused due to the removal has been properly repaired and the property has been connected to the local utility that is the source for electricity.

Since you do not own the solar power system and tax breaks or other financial incentives will go to the company that owns the system you are leasing.

Power Purchase Agreement (PPA)

A PPA is very similar to a solar lease agreement, with the exception of instead of paying “rent” for the system you are paying a fixed amount per kilowatt for the power generated by the system.

All the guidelines stated above for a leased solar power system apply to a PPA system. Including the company owning the solar panels receives any tax breaks and other financial incentives.

In California, Sacramento has mandated that power companies have 33% of their retail sales of energy to consumers be from renewable sources (solar, wind, geothermal, etc). There are other goals and objectives to increase this percentage beyond 33% in the future with the ultimate objective of 100% of electricity provided in the state be from renewable sources. The current mandate and objectives for the future, if fulfilled, will greatly increase the cost of energy to consumers. This is a primary factor for my consideration to purchase a solar panel system for our home, fix our costs for electricity to protect against future costs which will likely be significantly higher than today.

If you are considering putting panels on your home factors to consider should include how long you intend to be in the property, how much control you wish to have over the power system for your home, future impact on the ability to sell your home, and of course the total cost versus potential savings over what period of time.

Have a question? Ask me!

Still strong or getting weaker? That is the question after the Labor Department released it jobs report for April showing only 75,000 new jobs were added to the economy for the month. The speculation on the significantly lower number of job additions than prior months range from employers slowing growth as they are concerned about the impact of the trade tensions created by the Trump Administration, to scarcity of labor to fill many positions, to the hiring slowdown being a harbinger for economic slowing across the economy. All of these factors could be positive for mortgage rates.

Survey says….speculation is rampant that the Federal Reserve will ease rates at either its June meeting (a 30% chance per the speculators) or at its July meeting (70% chance per speculation) and today’s jobs report reinforces the speculation. The reasoning being that the Fed sees the economy slowing and wants to provide a boost by lowering rates. Counter-intuitively, such a move will likely have the impact on pushing mortgage rates up as it the move would fuel stock prices increasing, pulling funds from fixed rate investments to equities, which would increase the return bonds (and mortgages) would need to provide to attract investors.

Rates for Friday June 7, 2019: Markets are choppy as investors swing from fixed investments, such as bonds and mortgages, to stocks, day to day based on data, speculation and tweets. We are at our lowest rates in about 18 months and it feels like we are at or very near the bottom. Those waiting for lower rates may want to stop waiting

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.75%        Flat

30 year high-balance conforming                    3.875%      Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

On Tuesday, for the second year in a row I had the opportunity to present to two classes at Long Beach Poly High School. The class is AP Chemistry and is taught by Mr. Gillette. Once the AP test is completed there is not much to fill the class schedule for the remainder of the year so Mr. Gillette likes to bring in some “real world” education for his students. My topic is what it takes to purchase a home, but is actually financial literacy covering credit, debt, income, saving and long-term consequences—positive and negative. With many/most of the kids on the verge of taking on debt for the first time in the form of student loans it is a timely conversation with them about how debt works and how it has long term impact on their lives.

It has been my belief that financial literacy should be a mandatory class, or part of a class, for every high school student. Understanding how debt works, the power of putting money aside for savings and retirement and the relationship between income and education would increase the level of personal responsibility across communities and decrease the level of dependence.

From my experience interacting with high school seniors on the topic the last two years, they appreciate the information, ask great questions and will benefit, hopefully, moving forward into adulthood and being responsible for their own financial decisions. Expanding such education throughout school districts can only be a benefit for society.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
How can we help our children purchase their first home?

Question of the week:  How can we help our children purchase their first home?

Answer:  This question came up yesterday when I was having breakfast with Martin and Marc, two attorneys who between them have children between early to late 20’s. Concerned about the cost of residential real estate in California, they wondered how they could assist them get their foot in the door (haha, nice pun) of home ownership.

The concern Martin and Marc have is not unique, many parents with children entering the age they were when they were purchasing their first homes are concerned their children will either have to rent for a very long time, or move to another part of the country to purchase a home and raise their families—and grandma does not want to travel to Frisco, Texas or Nashville, Tennessee to visit her grandbabies!

There are three primary factors to loan qualifying: income, credit and cash to close. How a parent help a son or daughter with each of this areas of qualification, or can they?

Before we get into the different areas I will be addressing the two most common types of mortgages used by all home buyers and especially those purchasing their first homes, conventional mortgages, aka Fannie and/or Freddie, and FHA mortgages. Unless noted otherwise the guidelines will be pretty much the same.

INCOME

Conventional guidelines have loosened up on income assistance and now pretty much mirror the FHA guidelines. It is really hard to get your kid a raise, even if s/he works for you a sudden spike in income will have the underwriter arching eyebrows thinking, “this kid got a raise just to qualify,” which is why working for a family owned business typically requires a bit more history of earnings for qualifying.

A parent can assist with income qualifying by co-signing on the mortgage. When we have a co-signer combine all the borrowers’ income and all the borrowers’ debt obligations in the debt-to-income (DTI) calculation. When parents co-sign we must include their full housing payment, principal and interest on mortgage, property taxes, homeowner’s insurance and HOA dues if any. This inclusion of housing payment can sometimes be the barrier for a co-signer assisting as it throws off our DTI requirements.

It is important for anyone co-signing to know and acknowledge that they are 100% responsible for 100% of the payment. If the kids miss a payment it will reflect on your credit report. If the kids miss several payments and go into default, you are also in default. If the mortgage is foreclosed, you have a foreclosure on your record. Therefore, if you co-sign it is highly recommended you obtain on-line access to the lenders website so you can check in every month to make sure the payment has been made and all is well.

One concern many parents have when co-signing is how it will impact their ability to obtain credit in the future with another mortgage on their record. The current guidelines for mortgage qualification if an applicant has co-signed for another mortgage is if the applicant can show the primary borrower (a term I dislike using since all borrowers are equal) has made all the mortgage, tax, insurance and if applicable HOA payments over the past twelve months the housing payment will not be calculated in the qualifyinig for a new mortgage. For instance, you have co-signed for your kids and the total housing payment (PITI) is $3000 per month. You decide to purchase a vacation home in Palm Desert and are getting a mortgage, but with your current housing payment and your kid’s housing payment you do not qualify. You show proof that you kid has made all the payments for the house, mortgage, taxes, etc, for the past twelve months. Now the payment will not count in your qualifying and now you qualify for that 2500 square foot single-level in back of the golf course. “Proof” will entail obtaining bank statements from your children showing they have made all the payments required for the property, i.e. cancelled checks or direct payments to mortgage company, county tax collector, insurance agency. Note if there are systematic deposits into their account from you, this will be construed as assistance and therefore the payment will count. If there are even occasional deposits tracked to you for large sums there is a good chance this may disqualify the guideline as well.

CREDIT

The cliché in our business is, “you can’t co-sign bad credit.” This means if your credit scores are hovering around 800, and your kid’s credit score is mid-500’s, your 800 score is not relevant. For credit scores lenders use the lowest-middle score of all borrowers. Similarly if the situation is reversed and you have the low score and your kid has the high score, your score is the one that impacts the ability to qualify or the interest rate being higher.

The best way a parent can assist a child with the credit aspect of qualifying for a mortgage is to pay down or off some of the items on the credit report. In the short term paying an auto loan down to below 10 months of payments will have that payment not count in qualifying. If you son or daughter has an auto loan and the payment is preventing us from qualifying, if you are able to pay the account down to less than nine months that payment is not used in our DTI calculations and now they qualify.

The same can be done with other credit payments to lower total debt payments,  such as credit cards. As well, if your kid’s credit score is low, we can run an analysis to determine if there are any remedies to boost the score. Often times this can be done by paying off credit cards, or in many instances just paying them down below certain levels. Raising a score fifteen or twenty points can sometimes result in a lower interest rate and easier qualifying.

Before doing this make sure you consult with your mortgage professional (me!) to ensure it is done properly and does not create a situation that does not help in qualifying. Whenever there is “outside money” we have guidelines that must be followed. That leads us to….

CASH

This is the most common form of assistance that parents provide children looking to purchase their first home, a gift of cash for down payment, closing costs, credit relief, wherever needed.

Depending on when you make your cash gift to your children, there are specific guidelines that must be followed if there is a cash contribution to the borrowers to ensure the legitimacy of the funds are from a “acceptable donor,” essentially a relative or significant other (fiancé(e), domestic partner), and that the funds are not borrowed.

This entails a proof the donor had the funds to gift, proof the funds transferred from the verified donor account to the borrower’s account, a gift letter indicating there is no expectation of repayment.

Before making any cash contribution, or pay-off debt, or consider co-signing, please contact me so we can run through the specifics of the potential transaction and how you might help your children purchase their first home.

Have a question? Ask me!

Still strong. Early in the week the first revision to the 1st quarter Gross Domestic Product data lowered the estimate for growth in the quarter from 3.2% to 3.1%, not as strong as initially estimated but still a strong growth number for the nation’s economy. The news had no impact on mortgage rates.

Financially healthier households. That is the take-away from data released this morning by the government on personal income, consumer spending and inflation in April. Personal income grew at a very good rate of 0.5% for the month. While household revenue increased in the month, the additional funds were not being used for consumption, which grew at a rate of 0.3% from March—not a surprising number following March’s staggering 1.1% increase in consumer spending from the prior month. The Personal Consumption Expenditures index, a key gauge for inflation, increased only 0.3% for the month and is up 1.5% from last April, well below the Fed’s target inflation rate of 2.0%. With incomes up higher than spending it follows that the savings rate increased, from 6.1% in March to 6.2% in April. This is a bit of a mixed news data point, since consumer spending is 65-70% of our national economy, slowing growth in spending and higher rates of savings are great for long-term household finances but a bit of a damper on economic growth. Personally, I am fine with a bit of a slowdown in economic growth as a result of increased personal savings rates. Over all the news is neutral to rates.

Rates for Friday May 31, 2019: A great line this morning form an article on the MarketWatch.com (a Wall Street Journal subsidiary) website regarding the economy, “The U.S. economy is basically sitting in the middle lane of a highway. It’s unlikely to generate enough speed to justify a shift into the fast lane or slow down so much that it will be shunted to an off-ramp.” This middle-lane economy is a bit swervy as investors concerns over the Trump Administration combining trade strategy with foreign policy has them nervous for potential long-term impact on not only the domestic, but also the global, economy. While the domestic economic news keeps rates in the middle lane, domestic politics and international economics has investors in a “flight to quality” today, leaving stocks and buying bonds and mortgages—which puts downward pressure on rates. All the movement of funds has resulted in our 30 year conforming rate being the lowest it has been on a Friday since January 5, 2018.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.75%        Down 0.125%

30 year high-balance conforming                    4.00%         Down 0.125%        

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

It’s that time of year…near the end of school year but still not near enough for many kids. And parents. This morning as Leslie and I were walking the dog we crossed path with our neighbor who was returning to her home after loading a bunch of stuff into the minivan. “Almost there!” I greeted her. She turned to us with a smile, “I can’t wait. Lauryn (middle school) has a speech to give since she won a contest, a musical recital and then she’s in a play. All today!”

We wished her well and I told Leslie, “She embodies the Maycember song.”

What is Maycember? Click the link to the Holderness Family YouTube page for one of the most spot on, and funny, songs about the end of the school year that almost every parent—especially those with elementary and middle school kids–goes through.

For a great laugh for your Friday click here for “Maycember.” I’m thinking many of you will share this mom’s and dad’s you know can relate.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
What impact will the tariffs and trade with China have on mortgage rates?

Question of the week:  What impact will the tariffs and trade war with China have on mortgage rates?

Answer:  Great question, with a variety of possible answers, only three of which concern us: will the tariff tiff lead to higher rates, lower rates, or have no impact.

To recap for newer readers of the WR&MU, I have a degree in economics and political studies and have studied both since I walked on campus in August of 1980. There are plenty of jokes about economists not being able to give a complete answer to any question without a “but…” or “on the other hand…” which his some of what I will provide today, but also my personal opinion.

To recap the issue, in July 2018 President Trump imposed tariffs on China for what many consider unfair trade practices. There had been negotiations between China and the United States on trade issues since Trump and China’s President Xi Jinping visited the U.S. in April 2017 to meet with Trump, this was followed by Trump’s visit to China in November 2017. Following the visit negotiations on a broad range of trade issues were more circular than linear and the Trump Administration began implementing actions to pressure China into working to resolution of issues in the trade talks, and starting in March 2018 tariffs began to be imposed on certain goods entering the United States from China and other nations. China, in response, began imposing tariffs on certain goods imported from the United States.

Primary to the United States negotiations for a trade deal with China is the Chinese government doing nothing to stem, or preferably stop, the theft of intellectual property and the manufacturing of forged goods for sale into American and other international markets. The estimated costs of these actions by Chinese businesses, many of which are government controlled is from $250 to over $600 billion per year.

For more context, the trade imbalance with China in 2018 was $419.2 billion in China’s favor, in other words the United States imported $419.2 billion more from China than exported to China. From the numbers, the Chinese business and labor markets benefit more from trade between the nations than do American businesses and labor markets; on the other side American consumers benefit more from the imported goods from China than Chinese consumers from American imports.

Back to our question, what impact can this issue have on mortgage rates?

The issue can have the impact on increasing interest rates if the trade war is resolved in such a manner that results in loss of income to American businesses due to piracy and forgery of American intellectual property and products and a much wider opening to Chinese markets for United States goods. The result would be economic growth and expansion for the United States economy, which results in higher rates as strong economic expansion and growth tend to lead to inflation and higher rates. Rates or usually tied to stocks, if stock prices rise so do rates, besides higher prices and wages putting upward pressure, so will corporate earnings and profits sending stock prices higher pulling money out of fixed rate investments, like mortgages, creating more upward rate movement.

The issue can have the impact of lower interest rates if the trade wars continue beyond the United States and China to include other nations resulting in economic slowing in both nations and around the globe. This could create a recession, which is economic contraction instead of growth, which results in lower interest rates. Corporate earnings would drop, as would stock prices, which would have investors purchasing more fixed rate assets, leading to more downward rate movement.

The issue can have no impact on rates if either no new trade deal is put into place and the tariffs remain where they currently are or even increase some more.

Looking at the data, the last option is what I think will happen. It is important to separate the politics from the data of the trade between the United States and China. This is challenging since almost all of the information we receive is political in nature—just read all the adjectives, and the “could happen if…” “might happen if…” “may happen if…” in stories on any subject and in particular the trade issue, these statements color a story and ultimately inject politics. The impact of the issue so far has seen the stock market drop and climb and drop and climb, much of which I, and others, feel is unfounded as the impact of the tariffs on the overall economy and the amount of trade with China are both overstated.

Tariffs are taxes on imported goods that go to the federal government. From the beginning of our country until into the 20th Century, tariffs were the primary source of funding for our federal government. In 2018 Americans paid a total of $5.51 trillion in taxes (with a t-) to federal, state and local governments, of which $3.6 trillion when to Washington D.C. The most recent tariff hike on $200 billion in imports from China raised $30 billion a year in taxes for the United States, or about 0.8% (zero-point eight percent, or less than one percent) of total tax revenue last year. Certainly, a lot of money, but an additional $30 billion in tax revenue has zero impact on the government.

This also means that American consumers will pay $30 billion more for Chinese goods, absent inflation, due to the tariffs. In the first quarter of 2019 consumers in the United States spent $14.25 trillion, about 68% of our total Gross Domestic Product (GDP). If consumer spending drops 2% per quarter for the remainder of the year, a big if, total spending in the United States for the year would be over $55 trillion. The higher costs to consumers for the tariff costs are about one-half of one percent of their total spending (0.5%). Because iPhones and chargers are made in China, if we add 0.5% to the current cost of a high-end iPhone that is $1000, the price with tariff would be $1005.

Consumers are benefiting from the current situation in the grocery stores as food prices are down since China is importing less wheat, soybeans and other farm products. American farmers have crops ready to ship and while looking for other markets to take up the slack from the drop in exports to China an over-supply has led to lower prices at home. China importing less from the United States does not mean that China has stopped consuming wheat and soybeans, it means they are importing from other nations, which leads to higher prices in those countries, and also a vacancy in markets where they were exporting before selling to China.

In summation, the amount of trade between the United States and China is a very small percentage of our national economy, all exports to China amount to about 0.6% of our GDP so if all exports to China were to cease, while it would have a negative impact on some industries it would have a negligible impact across the whole economy. As well, the negative impact can, over time, be reversed with exports previously sent to China sent to other nations due to supply and demand in international markets.

Of greater impact to our domestic economy then the potential loss of trade is the historically higher tariffs on U.S. imports to China than Chinese imports to the United States, which has limited the Chinese markets to American companies while providing almost unlimited access to American markets by the Chinese. Combined with the loss of revenues due to theft of intellectual property and manufacture of forged goods, the trade situation with China is more costly to our GDP than the costs of the tariffs being imposed and loss of exports to China and higher prices for Chinese goods in the United States. Should an agreement be reached in which the Chinese government agrees to lower tariffs so they are somewhat in balance between the two nations and to crack down on forgeries and piracy the U.S. economy would see a very positive benefit due to an expanded marketplace for U.S. goods and retention of lost revenue.

Tariffs can be extremely harmful to both importers and exporters resulting in higher costs and/or lack of production. This is the case if the amount of trade and GDP impacted by the tariffs is a significant portion of either, or both, nation’s total trade and economy. While there is a lot of trade between the United States and China, the amount is not a significant portion of the American economy. Because of this the overall impact of the current tariffs, and potentially higher tariffs in the future, should not have a large impact on our economy nor interest rates.

Have a question? Ask me!

Speaking of American consumers, retail sales in April dropped 0.2% from March. Ordinarily this would be of some concern since consumer spending is 65-70% of our GDP, however since retail sales jumped 1.7% from February to March a slow down in April was expected following the torrid buying in March. Investors reacted to the news with a yawn and rates were not impacted.

Rates for Friday May 17, 2019: As stated, rather lengthily, above the perception of the impact of the trade dispute with China is worse than the actual economic impact. Perception however, is what moves markets and the markets will continue to be somewhat unstable until some sort of resolution occurs. After several weeks of rates being flat Friday-to-Friday we see a dip this week due to the instability in the markets and investors moving from stocks to bonds and mortgages.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.875%      Down 0.125%

30 year high-balance conforming                   4.125%       Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

If there are any fans of Boston teams reading this you may want to give me a call. The purpose of the call will be to ascertain your devotion to those teams and if it is enough to enable your Lucky Charm to remain in Boston for three more years. What Lucky Charm?

Last night the Boston Bruins advanced to the Stanley Cup Finals, where they will be the overwhelming favorite to beat either St. Louis or San Jose. If/when they do win the Stanley Cup, the Bruins will be the third team to win a championship for Boston since August 2018.

In August of last year our daughter showed up in Boston to begin her freshman year at Boston University. Her arrival was followed a few months later by the Red Sox winning the World Series and a few months after that the Patriots won the Super Bowl, and now the Bruins are four wins away from the Stanley Cup. Coincidence? Maybe. But if you are a Boston fan why take the chance? Why not make a donation to keep her in Boston as your Lucky Charm and bring more championships to your city?

For those who do not like Boston teams we may be able to negotiate what it would cost to get her to leave Boston and attend university where your favorite teams play. For your information, this Phillies, Eagles, Flyers, Sixers fan has struck out on her moving south….

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
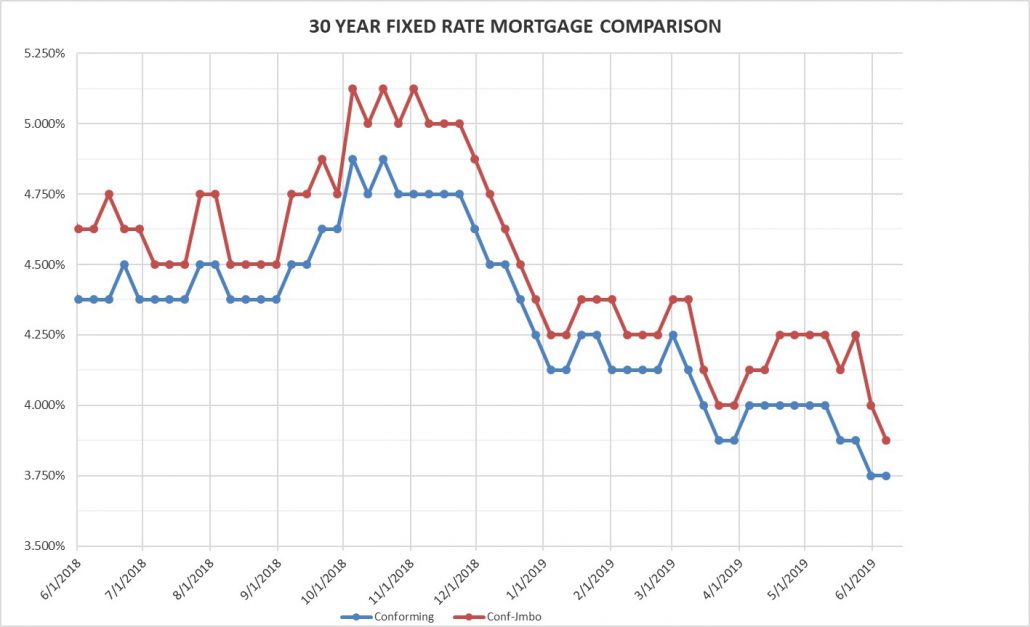
Why did my credit score drop?

Question of the week:  Why did my credit score drop?

Answer:  This question was posed to me by Bryan, with a Y, a young man who is starting his career, renting and already planning for his future which includes getting married and purchasing a home. He was concerned because he receives updates from his big Bank in America with whom he has a credit card about his credit score, and he received notification that his score had dropped about twenty points. Why?

Before I answered his question, I asked him another: why do you care?

My question was not meant to belittle Bryan, or to be sarcastic. I asked the question because I come across so many people who are very concerned about their credit score when they really do not need to be.

Bryan’s answer was typical, “because, I want to have a good score.” Well, even with the sudden decline in his credit score Bryan still has a really good score—the drop had no impact on his finances, credit or life in general. But still he was concerned.

In our conversation, I brought up when a credit score is important, when you are seeking credit.

By now everyone knows, or should know, that the cost you pay for credit depends to a large extent on your credit scores. The higher your scores the lower your costs for credit, the lower your scores the higher costs of credit.

When you are applying for a credit card, auto loan, a mortgage, your credit scores are important. When you are not applying for credit, or do not intend to for some time, your scores are not as important.

Does this mean you should not worry about your credit? As I told Bryan, live your life, buy what you need, use credit responsibly and you will have very good credit scores. If you use credit wisely and responsibly when it comes time for a large purchase you will have good scores.

Back to Bryan’s question: Why did his credit score suddenly drop?

  • Here are the primary factors that impact your credit score in order of importance:
  • What is your payment history—How you pay your credit obligations is the largest determinant of your credit score. The more serious any derogatory, i.e. late, payments are the more they hurt your score; a charge off or collection account is considerably more damaging than a 30 day late.
  • How much you owe and how much is available—While not as impactful on your score as your payment history, it is almost as important. Your debt utilization rate is more important than the total amount you owe. Debt utilization is the percentage of your available credit on an account that you have borrowed, the higher the percentage the higher the negative impact on your credit card. If you have a card that has a $10,000 limit and your balance is $9,350 the account will cost you points on your credit score; if on that same card you owe $4500 your score would be higher. For many clients we work with to improve credit scores this area is a primary focus as it is easier to lower credit balances than to get creditors to remove late payments.
  • How old is your credit—Having accounts that have been reporting for a longer period of time is better than having new accounts, especially revolving accounts such as credit and department store cards. If you are thinking of buying a home at the start of the year do not succumb to the department store discounts if you open a charge card with them during the Christmas season. As well, if you are considering purchasing a home do not close accounts until after you are in your new home.
  • What kind of credit do you have—Do you have a lot of installment debt or revolving debt or are you pretty balanced? The more broad the type of credit you have, mortgage, auto loan, student loan, credit cards, the better your score will be as long as they are within the parameters above. This factor is not a big impact on your credit score, but does have some influence.
  • Have you been shopping for credit—Multiple inquiries within a short period of time can hurt your credit score. That said some inquiries are worse than others. If you are purchasing a home or new car the scoring systems recognize you are shopping for installment debt, which if successful will most likely result in one auto loan or one home loan, and the impact of more than a few credit inquiries is not significant or perhaps have no impact. If there are multiple inquiries within a short period of time from credit card companies and department stores it is evident you are searching for credit which may signify some type of financial difficulty and the impact on your score could be several points.

Back to Bryan….It seems Bryan and his friends are going on a golf trip and Bryan fronted the funds for the reservations on his credit card. The total amount he charged to secure accommodations and tee times put his card balance over 80% of the card’s limit. Referring to factor two above, credit utilization, the high percentage of used to available credit on his card caused Bryan’s score to drop. When his friends repay their portion of the vacation expenses to Bryan and he uses those funds to pay down the credit card balance his score will increase to its prior level.

Credit scores are important as they are a very good indication of the risk a creditor takes when they lend money to someone. For individuals it is important to behave responsibly in credit use, but it is also important to not let concern about your credit score have too much influence on how you live your life.

Take Bryan, he is not buying a car or a home in the near future, so his credit score dropping twenty points for a short period of time is not very relevant. If he knew the credit score dip was going to occur would he have not made all the reservations for the guys’ golf trip? Probably not, Bryan’s a good guy and would make it easier for his friends, and himself, to secure the accommodations and tee times they needed so they can go ahead with their plans.  If Bryan was using a credit card that had “points” or other advantages, such a move was also very smart on his part.

In July of last year our Question of the Week was, “When should we have our credit report pulled when exploring the purchase of a new home.” If you missed this incredibly informative WR&MU you can read it here.

Have a question? Ask me!

Good timing award, goes to me for discussing personal debt and credit scores the same week the Federal Reserve released its monthly report on financial stability, in the report the Fed stated, “Household borrowing remains at a modest level relative to incomes, and the debt owed by borrowers with credit scores below prime has remained flat.” Consumer credit growth has slowed in recent months, while personal incomes have grown. It appears consumers are either increasing their purchases with cash and/or increasing their savings with their increased incomes.

Inflation remains tame. Both the Producer Price Index and Consumer Price Index increases in April were below expectations. Pushed higher by gas and energy prices the growth was only 0.2% for the PPI and 0.3% for the CPI (adjusted to 0.1% when food and energy stripped out of the data to obtain the “core” index). Year over year inflation for consumers edged up slightly from 1.9% to 2.0% in April, well within the Fed’s range of comfort. The news is rate neutral as it reinforces common sentiment that rates should remain stable for quite some time.

Rates for Friday May 10, 2019: This week was a good example of why watching financial data on an hour to hour, day to day, basis can be a bit maddening. As investors reacted to the comments by President Trump leading up to today’s trade negotiations with China and his then threat, now reality, to increase tariffs on Chinese goods by selling off in the stock markets, then buying back, then selling off we saw a similar see-saw in rate markets. Now that the words have become deeds, as I write this both credit and equity markets have rebounded. Over all the impact on rates from last Friday has been nil, we are flat for the fifth week in a row for conforming rates.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.00%        Flat

30 year high-balance conforming                   4.25 %       Flat

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

We are a culture of hyperbole, everything is the best this, the worst that, the most awesome thing ever. Social media, if anything, has exacerbated our tendency to hyperbole—enhanced with pictures and comments from friends validating our hyperbolic opinions J!!

Where the word “best” is not hyperbolic is when used like this, “I have the best Mom ever…” Because for the overwhelming majority of people this is true—our Moms are/were the best ever. The best at hugs, the best at turning tears into laughs, the best at being your personal chef to cut off the crusts or leave off the mustard. The first and best at unconditional love.

To all the Moms, you are the best! Thank you for being the best for all of us sons and daughters! (And from us husbands, thanks for being the best Moms for our children as well!)

One final note, a special happy birthday wish to my big sister who has spent many years filling some of Mom’s roles for my brother and I. We love you.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

What happens if the appraisal or home inspection present a problem?

Question of the week:  What happens if the appraisal or home inspection present a problem?

Answer:  In last week’s Weekly Rate & Market Update we covered the difference between an appraisal and a home inspection. To recap, an appraiser’s duty is to set the value of the property for the buyer, and the lender if a mortgage is funding part of the purchase price; the inspector’s duty is to inform the buyer as to the condition of the property and improvements.

Not all appraisal and inspection reports are green lights to continue with the transaction, some are yellow lights to proceed with caution and occasionally a bright red blinking light telling the buyer to Stop! What happens if you are not getting a green light from the appraiser’s or home inspector’s reports?

The standard purchase contract contains several very important clauses, at the top of the list are the time frames during with buyers can complete necessary investigations to determine if they wish to continue the transaction. These dates are known as contingency periods.

Within this period the buyer obtains an appraisal and completes any necessary inspections. If, after review of the reports, the buyer has concerns about the property and/or the price to purchase the property as agreed to with the seller, the buyer has the ability to cancel the transaction and receive a full refund of their good faith deposit, provided such notification is made during the contingency time frames in the purchase contract.

But is cancelling the only option?

Here are the options should your appraisal or home inspection report not support the sales price or reveal concerns regarding the condition of the property.

Appraisal

There are two primary issues in an appraisal report that could create an issue for a borrower. The most obvious issue is the value provided by the appraiser is lower than the sales price. The other issue is the appraiser notates issues with the property that need to be corrected.

We will cover the property condition issue first. In last week’s WR&MU when discussing the role of the appraiser we mentioned that the appraiser does not perform an in-depth inspection of the property, but will notate visible conditions that could impact the health and safety of the occupants or lead to future deterioration of condition; items such evidence of leaky roof, missing flooring, etc. If there are such conditions noted the underwriter will require that these conditions are corrected prior to final loan approval. Prior to issuing the approval the appraiser will need to return to the property and provide a written statement and pictorial evidence of the correction to the underwriter.

If this occurs then the loan is contingent on the repairs being made and the buyer can notify the seller that unless the conditions are correct they will cancel the transaction. The seller can then decide that they will make the corrections, or reply to the buyer no corrections will be made and they are fine with the transaction being cancelled. If the latter occurs the buyer has two options, first, move forward with cancelling the sale. Second, inquire if the seller will allow the borrower to make the corrections at their own cost after initial loan approval and before the close of escrow.

If the seller will not allow the borrower to make any repairs during escrow we move to another option to enable the sale to close. In some instances, the lender will allow the repairs to occur after close of escrow if there is a bid from a licensed professional to make the corrections and the funds plus contingency reserve (usually fifty to one hundred percent of the bid) is left in escrow to fund the cost of the repairs.

Quick recap: Appraisal report notates conditions on the property that need to be completed. Options are a) seller repairs noted conditions b) seller allows buyer to make the repairs before close of escrow c) lender allows buyer to make repairs after close of escrow d) neither party wishes to make the repairs and the transaction is terminated. Which option is decided upon between the buyer and seller depends on the market, seller’s motivation and ability, and the buyer’s motivation and ability.

The other issue that occurs with appraisals, and the one of greatest concern to all parties involved is what happens if the appraised value is lower than the sales price.

Before we get in to the options for the buyer and seller should an appraisal come in under sales price it should be noted that the first action when this happens is a very thorough review of the appraisal and the comps utilized. We then contact the agents for the buyer and seller notifying them of the low value and provide them with the comparables used and ask them to come up with other sales we can ask the appraiser to use that would support a higher value. Since I have access to the Multiple Listing Service, I research the properties used for the comparables in the appraisal report to see if any should not have been used. Perhaps one of the comps was a flip, or the previous owner died in one of the comps, a comp is on a very busy intersection and this was not accounted for, etc. I then research the area for better comps to see if we can find any that would enable the appraiser to increase the value. With the comps from the agents and my own research I write an appeal and submit it requesting the appraiser reconsider the value based on the new information provided. We have a fairly high success rate in having adjustments to the value on low appraisals. There are, however, some properties that are sold at values higher than the current market supports, or there is a lack of comparables available to justify the appraiser increasing the value on the report. In these instances, or if an appraiser rejects our appeal, we must go through the options for having a value lower than the sales price on the appraisal report.

Most home purchases involve the buyer getting a mortgage to enable the purchase to close. A major part of the rate and cost of the loan is the loan-to-value, or LTV, which is what percentage of the purchase price is the loan? If you are putting 10% down the LTV is 90%, If you are putting 25% down the LTV is 75%. The lender calculates the LTV based on the lower of the sales price or the appraised value. If you are putting 10% down on a $500,000 purchase obtaining a 90% loan for $450,000 and the appraised value is $490,000 you LTV has gone from 90% to 91.8% LTV. This move up from 90% LTV changes the rate and/or price of your loan and the premium on any mortgage insurance.

In this scenario, not only are you potentially paying more of your mortgage but you may be more concerned that you are over-paying for the property. So, what are your options. It should be noted that the impact on a low appraisal is of greater concern to those with lower down payments than those with higher down payments as the impact on the cost of the mortgage is less, or none, the lower the LTV; i.e in above scenario there will be a higher rate/cost moving above 90% loan to value with the low value, if the original LTV was 55%, the low appraisal moving the LTV to 56.1% will have no impact on the rate or terms of the mortgage.

There are four basic options when an appraised value is less than the sales price.

The first option is you notify the seller of the lower appraised value and you wish the sales price of the contract to be lowered to the appraised value. The seller agrees to lower the price and you continue with the transaction at $490,000 and you put 10% down for a new loan of $441,000 at 90% of the appraised value and purchase price.

The second option, which occurs if the seller refuses to lower the purchase price to $490,000 you can agree to retain the purchase price of $500,000. If you choose this option you can either put an additional $9,000 down and obtain a loan of $441,000 to retain the 90% LTV rate and terms; or you may decide to retain the $450,000 loan amount with the $50,000 down payment and accept the rate and terms that would be available at the 91.8% LTV. In this scenario, we often go with the lower down payment scenario and move forward with the higher LTV mortgage as the math works in the buyer’s favor; however it depends on the buyer’s cash situation and preference of cash in the bank or higher monthly payment.

The third option occurs if the seller does not want to come down to the appraised value and the buyer does not want to pay the original sales price. Buyer and seller find a price between the appraisal and contact sales price. Usually, but not always the amount is cut in half, in this case the buyer and seller agree to complete the transaction at a price of $495,000. The buyer can then decide to increase the down payment to $54,000 or obtain a low at 90.9% loan to value.

The fourth option is the buyer does not want to pay more than the appraised value and the seller does not want to sell for less than the original sales price and the sale is cancelled. We usually see this option when there is a very wide spread between the sales price and the appraised value, and/or there are significant conditions with the property that will need to be addressed per the appraiser and/or home inspector. If the spread between the appraised value and the sales price is not too wide we rarely see neither side willing to move of their perceived value of the property. From the seller’s side, even if they had multiple offers they may not want go back to a previous buyer and chance another appraisal or worse go back on the open market. For the buyer, long term a few thousand dollars, while a lot of money, will likely make little to no difference in the long run of owning the home.

Of the four options when an appraisal value is lower than sales price in order from most often to least option outcomes we see Options 3 (meet in the middle), Option 2 (buyer pays sales price), Option 1 (seller lowers price to appraised value, Option 4 (transaction is cancelled). Most buyers and sellers want to complete the transaction.

Inspection

Not every home is perfect. Correction, no home is perfect. How unperfect are you willing to accept when you purchase your new home?

In the WR&MU update we discussed how a home inspector will go through, above and under a home and complete a report detailing the condition of the property, notating what is in working condition, what is not, what needs to be corrected now, soon or later, and what is in good condition and will not need to be replaced for quite some time.

Too often buyers are overwhelmed by the report and the list of items that are noted as, let’s say flawed. Cracked or broken switch plates? No home is perfect, move on. Cabinet under the sink damp and pipes rusted? No home is perfect, but this may cost quite a bit to fix and cure.

Upon receipt of the inspection report the buyer should go through the report to determine what falls under routine maintenance and are minor issues, such as the cracked switch plates and walls that need painting, and what issues are somewhat major and need to be addressed fairly soon to prevent further damage to the home or create a health and safety issue, like out of date electrical or plumbing.

After receiving the report and within the contingency period the buyer can provide the seller a list of items that they would like corrected before the close of escrow. In this instance we are discussing repairs that have come up from the inspectors report, we dealt with options for items on the appraisal that underwriting would require to be fixed above.

When this happens we typically see three replies from the seller: a) okay we will do the repairs b) sorry, we will not do the repairs c) we will not do the repairs but we will give you a credit of X thousand dollars so you can make the repairs after escrow closes.

If Option A is the reply to the repair request, woo-hoo! you are saving money on repairs. If Option B is the reply you have a decision to make, cancel the transaction, get your deposit back and start looking again for you new home, or stay in escrow and make the needed repairs yourself after escrow closes.

Which brings us to Option C, the seller offers to provide a credit so the buyer can correct the items themselves after escrow closes. When these credits arise we typically do not lower the sales price, but rather have the credit go through escrow to pay for closing costs for the borrower. This is usually because our clients are leveraging their purchase with a relatively high loan to value mortgage, 75% or more, and a credit for closing costs puts the funds into their pocket dollar for dollar as opposed to lowering the sales price. Huh?

In the above example with a $500,000 sale and the borrower putting down $50,000, or 10%, total cash to close can approach $70,000 when the cost of the loan, escrow, title, recording fees, funds for pro-rated interest and to establish an impound account for taxes and insurance. Let’s assume that the inspection report showed the electrical and plumbing systems needed to be upgraded or replace and the buyer received and estimate of $10,000 for the work to be completed. The seller does not want to live through the work being done while they are working, sending kids to school and packing for moving to their new home so they have agreed to pay for the $10,000 through the sale.

If the buyer agrees to lower the sales price by $10,000 for the credit the amount of cash they will need to close will be close to $70,000 still as the only real cash they are saving is the 10% on the $10,000 reduction (10% of original $500,000 sales price is $50,000; 10% of the reduced sales price of $490,000 is $49,000). There are incremental savings on the other fees but the total will likely be $500 or less. So the buyer saves $1000 in cash to close but will need $10,000 to make the repairs.

If the seller credits the buyer $10,000 in closing costs the buyer needs $60,000 to close the transaction instead of $70,000, a savings of $10,000—the amount to make the repairs.

If the credit is listed in escrow as “$10,000 credit to buyer for repairs listed on home inspection report” the underwriter will ask to see the report and may decide more items need to be fixed, as well the $10,000 plus a cost overrun contingency of 50-100% will need to be left in escrow and released only when proof is provided that the repairs were completed.

It is important to note that very rarely (very rarely) does an underwriter see the report from the home inspector. This enables the buyer and seller to negotiate regarding any repairs the buyer would like to see completed without having the lender mandate any corrections not notated on the appraisal report.

No home is perfect. A low appraisal or discoveries of flaws by a home inspector need not kill your purchase transaction if both parties are committed to closing. If one party is more intent on getting “a deal” than purchasing or selling a home then the opportunity increases for the transaction to no move forward, however if both parties are willing to negotiate and be open to a solution more often than not the buyer will be getting the keys to their new home and the seller will be receiving their net proceeds to move onto their next home or bank account.

Following last week’s update Cathy, real estate agent extraordinaire in the Central Coast, sent me this message, “The biggest difference between an appraiser and an inspector…if you get a stupid appraiser, it is not your fault. If you get a stupid inspector, it is.”  Which is why we have an appeal process.

Have a question? Ask me!

Positive news keeps coming. This week we had some important economic data released and all of it was positive. Monday we learned that consumer spending in March had its biggest one month increase, 0.9%, in nearly a decade, and 2.9% increase in spending over the past twelve months. Perhaps fueled by continued increases in personal incomes continuing to rise and having gained 3.8% from last March to this. This data suggests another strong quarter of growth in the second quarter. Strong growth in spending and wages is traditionally mortgage rate unfriendly it supports economic growth which leads to inflation which leads to higher rates. However the core inflation rate released with spending and wage reports showed no increase in prices in March and a dip in the annual rate to 1.6%, just above the Federal Reserve’s floor for what it considers acceptable inflation of 1.5%.

The week started and ended with positive news, as today the Labor Department released employment data for April showing 263,000 new jobs in the economy for the month and a drop in the unemployment rate to 3.6%, the lowest rate since the month my 58 year old brother turned 9 (December 1969). In a separate measure of income from the report on Monday, the Labor Department reported hourly wages increased in April for annual increase of 3.2% from the prior year. Over all the news is also negative for mortgage rates.

Rates for Friday May 3, 2019: Based on the economic data, or most of it, rates should be higher this week. However the tame inflation numbers have investors backing off expectation for higher rates, and this sentiment was supported by the Fed which this week announced…nothing. No movement expected for the rest of 2019 by the Federal Reserve which has investors sitting tight on fixed rate investments. Week over week we are flat for the fourth week in a row for conforming rates.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.00%        Flat

30 year high-balance conforming                      4.25 %       Flat    

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

I guess this Marvel Avengers movie thing is a pretty big deal. Who knew? My daughter did and does. Like many others she saw the latest, and last, of the series on opening night and then again, a few nights later. Reading the receipts for the movie domestically and internationally it seems I might be missing out on something. Can’t wait for it to be on Netflix so I can pause it several times during its three hour run time for some refreshments and subsequently needed bathroom breaks.

I’m pretty old fashioned when it comes to movies, and other things. I like the old Westerns, dramas, mysteries and musicals and have never been a big fan of the Star Wars, comic book genres.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog