Should we wait until we have a 20% down payment to purchase our new home?
Question of the week: Should we wait until we have 20% down payment to purchase our new home?
Answer: No.
I have covered this topic throughout the years answering various questions that invariably lead to down payment, be it my thoughts on mortgage insurance (I like it, I will reprise reasons in coming WR&MU), cost of waiting to buy (covered last November), or borrowing from your 401(k) to help with your purchase, and many other questions of the week. We will cover it again today.
In a survey conducted by the California Association of Realtors the number answer to the question “Why didn’t you purchase a home sooner?” was “Needed to save for a down payment.”
Anecdotally, within my own and my co-workers’ experience the past several years, this is also a prime barrier we see with many of our clients who wish to purchase homes. The want to save more money for a down payment.
A bigger down payment.
It takes a lot of money to purchase a home in California, especially Southern California. Combine that with the prevailing sentiment of avoiding mortgage insurance and we have many families who could purchase a home today but are delaying doing so in order to save more money for a larger down payment.
It has always been my opinion that if you are able to purchase a home with the funds you currently have available you should do so. As I covered last November with a very detailed comparison of two families purchasing homes in September 2017 versus 2018 the cost of waiting for accumulating a higher down payment to avoid mortgage insurance can, and usually does, costs you more in the long run.
The counter-argument is that he housing market is slowing. Last week the WR&MU had the home sales statistics for California showing the number of sales declining and prices, while flat year to year, were down from the prior month. If the market is slowing and prices may come down, does it not make sense to wait to purchase and let prices fall further and while waiting save more money for a down payment?
Only if your crystal ball is correct, if interest rates stay near their current levels and do not increase, if you are able to correctly predict the market, if you are certain the home in the neighborhood you want will still be available when you determine the timing is right.
Perhaps the biggest shift in homebuyers’ attitudes from the pre-2008 real estate bubble burst to the post-20008 real estate bubble burst has been their reason for purchasing a house. Many in the period of the real estate price balloon expansion prior to 2008 were purchasing houses, they were looking to make money on a real estate investment, they were using the value increase to obtain equity to finance consumer consumption. They were not buying homes so much as investments, as such price was what mattered most.
I have found that the homebuyers we have been speaking to and working with the past decade have been more interested in purchasing a home. They are looking for a place to raise their families, spend their retirement and hold for a long term rather than hoping for prices to climb so they can cash in.
This shift in mentality negates, somewhat, market conditions. If you are in a home for a long period of time, ten, fifteen, twenty years, minor market corrections are not of as much importance as if you were looking to purchase and then sell in the next three or five years.
If you have three, five, ten percent of the purchase price of the home you want to purchase available, and you can afford the mortgage payment buy the home. Buy the home today with the funds you have available and begin creating the home for your family. Yes, there may be a dip in the future of your home’s value, but does it matter if you will not be selling?
Our nature is to get what we want for the lowest price possible, but often while looking for the lowest price we are missing out on the best quality, best service or best product for ourselves and our family. Have you ever been shopping different airlines for ticket prices for your family vacation and see a good price but then take five or ten minutes more to see if there is a better price, then gone back to the site with the lower price and find there are no more seats available? You lost out on a potential bargain by looking for a better one. This happens to homebuyers as well, even in a soft market.
If you have funds available for a down payment, but are wanting to save more, please call me so we can discuss all your options for today and tomorrow when you have the funds saved you feel you will need. Those who know me know that I am not a “hard-sell,” I merely present options for you to make the decision you feel is best for you and your family, I cannot make you purchase a home, but I would like to show you the options of how you can—or if you are not able to show you what you need to do so you will be able to purchase your new home.
Find out your home buying options today, even if you want to wait until tomorrow.
Next week I will again answer the why I like mortgage insurance question, the week after I will cover the second reason families give for delay their home purchase as it coincides with work we do with our clients.
Have a question? Ask me!
Due to the partial government shutdown several economic reports for December are being released along with January data. One of these is personal income and consumer spending for December. December was an interesting month, personal incomes rose a very strong 1% for the month, but consumer spending dropped 0.5%, the largest drop since 2009. As a result of the increase in income and decline in spending personal savings jumped to 7.6%. Overall the news is mixed for its impact on mortgage rates, higher incomes should lead to higher spending and inflation, but the decline in spending and increase in savings should lead to a slowing in the economy.
Despite the drop-off in spending in December the 4th quarter Gross Domestic Product still grew by 2.6%. The rate of increase was slower than the 2nd (4.2%) and 3rd (3.4%) quarters but not enough to prevent 2018 to be the fastest growing economy since 2005. Holding back 4th quarter growth were a myriad of factors including housing and the trade deficit—and late in the quarter spending by consumers. Inflation for the quarter was 1.7% and year over year right at the Fed’s target inflation rate of 2.0%. Overall the news is negative for mortgage rates, a strong economy usually portends higher interest rates. However despite the strong growth in the year we have seen rates from recent highs in the fall of 2018.
Looking ahead, consumer confidence surveys released this week saw a surge, increasing for the first time in four months as most surveyed see better conditions ahead for themselves and their families. Will this confidence lead to increased spending and continued GDP growth above 2% and possible 3%?
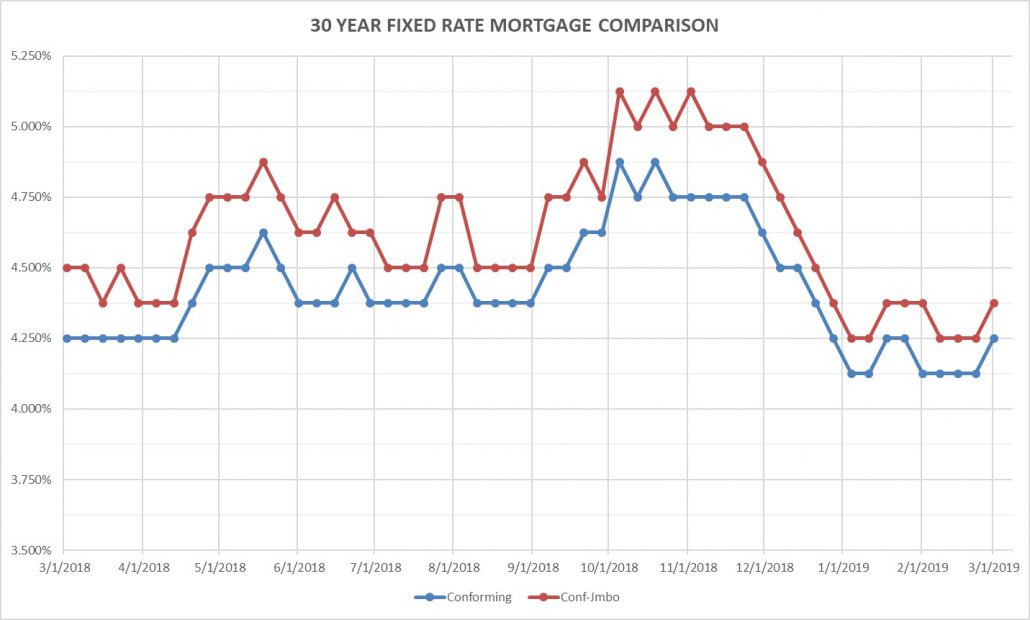
Rates for Friday March 1, 2019: After three weeks of steady rates we see a slight bump in interest rates from last Friday. There are many small reasons why this has occurred, mostly investors chasing higher yields elsewhere which puts a damper on prices and therefore higher returns, i.e. rates, in the market. I do not see this as a trend.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 4.25 Up 0.125%
30 year high-balance conforming 4.375% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Sometime during our first year of marriage I got a bad head cold and Leslie said, “My dad has always said it takes three days to get a cold, three days to have it and three days to get rid of it.” Over the years I have noticed Don is right about this. Today is day one of the three part series for me, which means the last three days have been the wonderful, sneezy, snuffling, achy, sleepy portion of the cycle. Blech. Despite Don’s wisdom that this too shall pass, I am one of those who takes everything available, DayQuil, Mucinex, Emergen-C, Afrin, NyQuil, Ibuprofen, water, soup, whiskey…some day I’ll learn that I should just stick to one and ride it out.
I hope your week was spent in better health and that you are able to have the three-three day cycle avoid you and your household this year!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog