

Weekly Rate & Market Update 3-10-17
Question of the week: What price should we offer?
Answer: Ask any real estate agent what is the hardest question they are asked and this will be the answer. You have looked at several homes and found the one you want to buy, how much do you offer the seller?
My quick answer, what it will take to get the home within your ability to qualify.
We are conditioned to want to find a bargain, to get something for less than its value or what a seller is asking for their product or service. Our first big purchase is usually a car—who has every paid sticker price for a new car? We expect to get “a deal” and negotiate for a lower price. Buying an appliance? How often has the salesperson said, “if you buy today we can knock down the price….”
We go to CostCo, Target, Walmart, Marshall’s to save a few bucks. We purchase three packs of chicken thighs because they are on sale for 30% less than they were the week before.
Planning a vacation we go on-line to websites that offer lower airfares, hotels and rental cars. We purchase books, clothes, laptops, shoes, on-line for the convenience and to save a few more bucks. We want to see our favorite sports team and go to a site that sells tickets in the secondary market looking for a discount.
We shop, we look for what we feel are bargains. We love to tell people how much we paid for something—less than market value or what they paid for the same thing.
When we look at purchasing the most expensive product we have ever purchased, our home, we have ingrained in us to get the best deal.
Back to our question, how much should you offer for the home you want to buy?
On the one hand you would like to get a bargain, why pay the seller what they are asking?
On the other hand you want to get the home, it is what you have been looking for, but how much is “too much.”
This question is easier for an agent to answer in a buyers’ market—the seller does not have many offers and is probably willing to negotiate. It is a little harder to answer when the market is balanced with a decent amount of inventory and active buyers in the market. The question becomes harder in a sellers’ market when many (most?) listings have multiple offers. Which is the market in Southern California for the past year or so.
It seems if you offer list price you may be over-bid by another buyer and you are back looking again. If you over-bid and the seller takes your offer you feel as if you could have purchased it for less—or you worry that the home will not appraise for the sales price you and the seller have agreed upon. More to the point, it is psychologically very difficult for us to pay more for something than the asking sales price.
Back to my answer: pay what will get you the home you desire within your ability to qualify.
I have seen clients lose homes that they felt was perfect for them because they wanted to try to save three, four, five thousand dollars on a sales price. That home today is probably worth 30-40% of what it sold for several years ago. I have clients still in the market after having starting to look last year because they want “a deal.” With prices climbing over 5-6% over much of Southern California their “deal” was buying a home last year.
There rarely a correct answer as to what your initial offer can be. If you do not offer enough and do not get the home you want then you are upset because you missed the opportunity. If you make an offer and it is accepted you may feel like you left “dollars on the table.”
Don’t. Don’t think you left anything on the table. Be glad that you were able to reach an agreement with the seller so you can purchase a home for you and your family to enjoy for years and years to come. Ask any happy homeowner if they feel they overpaid for their home, and most will tell you they did not—even if they felt like they did at the time.
You are buying a home. Not a plane ticket, not headphones, not five pounds of onions, not a car. A home. So buy it.
Remember, with Dennis it’s not just a mortgage, it’s your complete financial picture.
Plenty of positive economic news this week, which means negative news for lower interest rates. The week started with the Gallup US Spending measure in which consumers self-report their daily spending. February’s daily spending, $101 per day, was the highest for February since 2008. A sign of positive consumer sentiment, since consumer spending is 65-70% of our Gross Domestic Product, the news was interest rate negative.
Even more negative and causing a big drop in Mortgage Backed Securities prices (lower MBS prices means higher rates) Wednesday morning as the ADP payroll report showed an increase of 298,000 private jobs in February. This was the largest single month increase since October 2015 and one of the largest gains for this report since the recession ended in June 2009. The news solidified the Fed raising rates next week and started some speculation that perhaps instead of the standard 0.25% increase the Fed Discount rate may be increased 0.50%. The bond markets (which includes mortgages) opened significantly lower on Wednesday following the report.
It is not uncommon for the Department of Labor monthly report to be at odds with the ADP report, it does not happen all the time but often enough so that when it does it is not a surprise. The DOL report this morning however reinforced the ADP report showing an increase of 235,000 jobs throughout the economy and a drop in the unemployment rate to 4.7%. Within the good news of the report for job seekers was more good news. The decrease in unemployment was not directly related to a decrease in those seeking work, the participation rate increased and hourly wages showed an increase as well. All the news double-solidified the Fed rate increase next week.
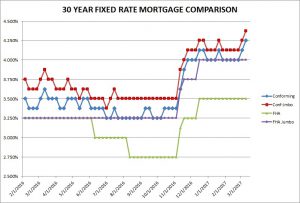
Rates for Friday March 10, 2017: After several weeks of stable rates we see them increase for the second week in a row. Is this trend that will continue or is the market finished pricing in next week’s Fed rate increase and starting to price in the next one? There is upward pressure on rates and unless they hit some resistance at the current level we can see a bit more upward drift. Those who have been floating waiting for lower rates are getting further behind. I maintain my advice: lock your rate when you are able through your escrow period.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 4.25% Up 0.125%
30 year high-balance conforming 4.375% Up 0.125%
30 year FHA 3.50% Flat
30 year FHA high-balance 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down (3.5% for FHA) with 740 FICO score for purchase mortgages.
Regular readers of the Weekly Rate & Market Update know that I always include a personal note to conclude the report. This morning I was intending to comment on our split family weekend as Leslie takes off to the desert with her friends from high school—a very well deserved few days away from me and the girls to relax and have fun with her friends getting some much needed Leslie-time. I guess I just commented on that.
I thought about leaving it at that but we had a sudden event last night that has made our day rather rough. Around midnight we were awoken by our dog having some issues and we heard him fall in the bathroom. Leslie and I got up and found him lying on the floor in distress. As we patted and loved on him he quickly passed away. We suspect a heart attack or stroke that may have been a result of his lupus that we thought was in remission.
Harrison was a wonderful dog. All who had met him always commented on his handsome looks, which we know he heard and relished, his calm demeanor and how sweet he was. Our home our hearts are emptier without our big dog. It was a perfect relationship between dog and family—we were so lucky to have him and he was lucky to have us.
Back to our question of the week, this is our home, I don’t care that several people told us we probably overpaid for it almost twenty years ago, our children, pets, family, friends, visitors do not care what price we paid they, and us, are just grateful we have this home to fill with love and wonderful memories.
If you have a dog take an extra walk with him or her this weekend for me and Harrison.
This one is for Harry,
Dennis

