What is the difference between an appraisal and a home inspection?

Question of the week:  What is the difference between an appraisal and a home inspection?

Answer:  This is a great question that comes up frequently with first time buyers, and some experienced homeowners purchasing for the first time in a long time.

The first difference is one is usually required and the other is optional.

Appraisal

If you are getting a mortgage to purchase the property the chances are very high the lender will require an appraisal. (In some instances, Fannie Mae or Freddie Mac may allow a “waiver” for the appraisal, this could happen for transactions with a low loan to value. Waivers are not rare, but are not common either.) The primary purpose of the appraisal is for an uninterested, licensed, professional to ascertain the value the property used as collateral for the mortgage on the date the offer from the buyer was accepted by the seller. The secondary purpose of the appraisal report is to notify the lender if there are any noticeable defects that could impact the value and/or salability of the property or present health and safety concerns for occupants.

Many people are surprised at how little time most appraisers spend at the actual property. They spend so little time because most of the work to prepare the appraisal report is done before the appraiser goes to the property for his/her inspection.

An appraiser will receive a copy of the purchase contract and any counter-offers for the transaction at the time the order is made. Before heading out to the property the appraiser, using the Multiple Listing Service and public records, will research the area looking for comparable properties. A comparable property is one that is similar to the subject property in type of dwelling, size, number of bedrooms and bathrooms and other amenities that impact value such as a pool. The appraiser will look at recent sales to determine prices for the closed sales, how long the properties were on the market, and the condition of the properties at time of sale. Properties that have been recently sold but have not yet closed escrow (called “pending sales”) will also be noted to determine if there is current activity for comparable properties to the subject. Finally, the appraiser will look at active listings on the market to determine what other options did the buyers have at the time they purchased the subject property and at what price and condition.

Once the appraiser knows the terms of the transaction and has an idea of the comparable properties in close proximity, s/he will inspect the subject property. The appraiser will measure the property’s interior room by room to make a sketch showing the overall size of the property and rooms. While measuring the appraiser will visually inspect the property to ascertain the overall condition, and not any noticeable issues that may impact value or the health and safety of inhabitants. Any noticeable water stains in the ceilings will be noted as they indicate a leak in the roof at some point, if there are missing window panes, flooring that is missing or has holes, missing sinks or toilets, anything that deters from the property being fully habitable or that could be evidence of a bigger issue is photographed and noted. In California the appraiser will also photograph and take note that the property meets state law by having smoke and carbon monoxide detectors properly installed and that the water heater has earthquake straps and is on a stand or platform so it is off the ground.

The appraiser will not test the plumbing or electrical systems, test windows for their ability to open, or otherwise perform a very close and detailed inspection.

The appraiser will drive by the comparable properties that are being used to establish value and take photos for them from the street.

After all the data is collected the appraiser will prepare the report. The report will compare the comparable properties and make adjustments to the sales price of those properties for size, condition of property, amenities, location (such as on a busy street), etc to arrive at an opinion of value.

Inspection

When you and the seller agree to a sales price one of the clauses you will likely agree upon is the opportunity for you, at your cost, to engage a professional to inspect the property, what the industry calls a “home inspection.” You may choose whomever you desire to perform the inspection, it is recommended that you choose someone certified by the California Real Estate Inspection Association (CREIA). In California there is not state licensing or regulations for real estate inspectors, CREIA a professional organization that has requirements for its members that include continuing education and following codes of ethics.

It is important to note that the inspector works for you. Not the seller or the real estate agents, but for you. The objective of the inspector is to perform as thorough and examination of the subject property as possible, the result of which will be a very detailed report.

The inspector will grade everything examined from needs replacing to estimated longevity to in fair-good-excellent condition. It is not the inspectors concern if the report “blows the sale” or “makes the sale” but to provide an objective, honest report of the property’s condition.

A thorough inspection will include inspecting the roof, and if possible the attic and/or crawl space below the roof. If on a raised foundation, crawling under the property. Inspecting the electrical panel and testing outlets and switches. Testing the plumbing by flushing toilets and turning on taps to gauge water pressure. Appliances that use gas  will be tested to determine if they are functioning properly with appropriate hook-ups and safety features. These are the major areas of concern and cost to repair or replace, but all aspects of the property will be inspected and put into the report for the buyer.

Not included in the report will be the cost to correct any defects noted, and it is not ethical for an inspector to quote, bid on or complete any repairs noted as needed on the report.

Once completed the report will provide the buyer with a very good indication as to the condition of the property. It should be noted that there is not “perfect” home in regard to condition; even brand-new homes can have faults and issues that need to be corrected. The important issues to consider on a home inspection report are the major, “big ticket” items that may need to be replaced or repaired in a short period of time. If there are any such items listed, say the electrical needs to be updated, it is encouraged for the buyer to obtain a bid from a licensed contractor for the cost to correct, and then make a decision how to move forward.

It is highly recommended that you accompany the inspector when s/he visits the property for the inspection. Note that this inspection is much more thorough, and therefore time consuming, than the visit from the appraiser, in some cases a few hours. By attending the inspection you can learn a lot about your new home, where is the gas shut off valve, education on the electrical panel, where are the clear-outs for plumbing, and most importantly get a verbal report and detail form the inspector that will shed more light on the condition than just reading a formatted report.

The primary difference between an appraisal and an inspection is their purpose. While the appraiser will note some condition items the primary purpose is to let the lender know if the sales price is supported by the market in the area, the purpose of the inspection is to inform the buyer of the condition of the property and its components. Both are very important because of their purpose.

Next week what happens when appraisal is low or inspection shows major issues?

Have a question? Ask me!

“Well, that’s surprising.”  This was the thought of many investors, analysts and watchers of the economy this morning when the government released the data for the Gross Domestic Product for the 1st quarter of 2019. Expectations at the end of the 4th quarter in 2018 was for growth this past quarter and as the quarter progressed and economic data was received for January, February and March the consensus expectation rose to 2.3%. Today, the first report for GDP growth in the 1st quarter was 3.2% growth, well above expectations. Besides strong economic growth in the quarter inflation eased from the prior quarter’s annualized rate of 1.9% to 1.4%. Of concern in the data was a slowing in consumer spending to 1.9% growth, the lowest in a year. The report should have no impact on the Federal Reserve’s decision to change its current policy to hold firm on rates through the year. Overall the report should be negative for rates as a growing economy leads to higher rates, however the tame inflation segment of the report and consumer spending data is positive for steady or lower rates.

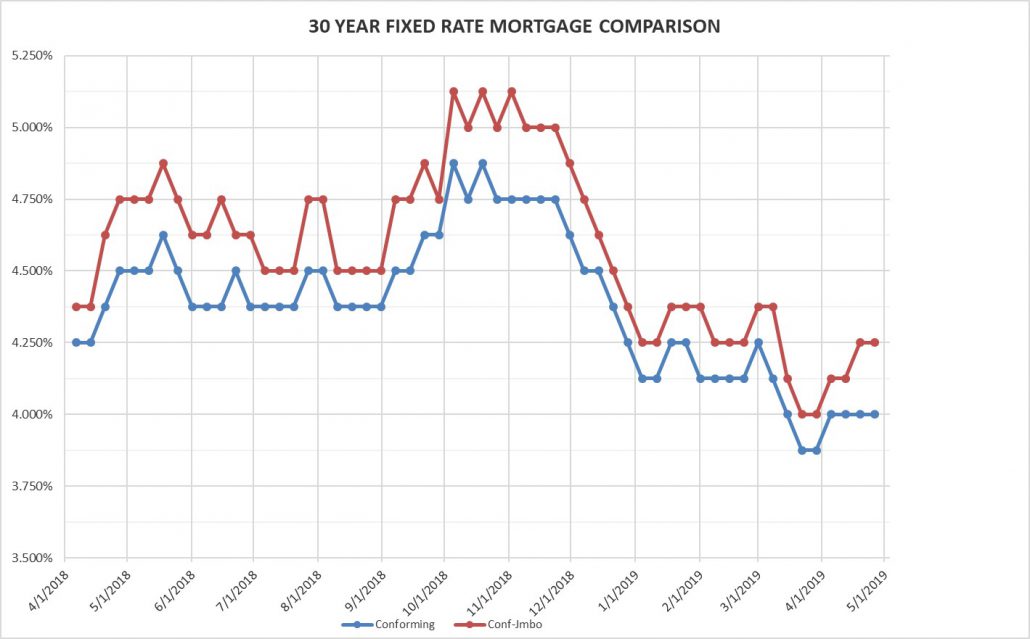
Rates for Friday April 19, 2019: Will the GDP report cool the speculation about a recession later in 2019? That is the major question investors will be analyzing moving forward as investors react on what they feel may happen, or what others may feel will happen directing their actions. For now rates remain flat from last week.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.00%        Flat

30 year high-balance conforming                     4.25 %       Flat    

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Earlier this week we began the Great College Search II with our youngest daughter. We spent a few days in Seattle seeing the sites with the primary site being University of Washington as a possible landing spot. A very successful trip on all accounts. I like Seattle a lot, similar in many respects to San Francisco, but a nicer, cleaner, seemingly safer place to visit the last several years, in my opinion.

Next week is back to regular schedule in the house as spring break ends and the grind to the last day of school begins. I like regular schedules…

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Good Friday Short Update

Question of the week:  No Question of the Week due to Good Friday

Answer:  With many readers of the WR&MU having short day for Good Friday today and weekend Easter activities we have an abbreviated communication this week.

Tune in next week as we delve into appraisers and inspectors and the roles they play.

Have a question? Ask me!

Markets are closed today, but we have some important economic data this week that impacts rates. Retail sales for March had a very strong jump from February. With a 1.6% increase in retail sales, the highest monthly jump in 18 months, prospects for a potential recession later this year dim. The large increase in sales was pushed by new auto sales, which climbed 3.1% for the month and gas prices which were up 10% nationwide in March. Stripping autos and gas from the data and sales still recorded a very strong 0.9% increase for the month. Overall the news is interest rate unfriendly as consumer spending is 65-70% of our economy, stronger retail sales indicates a strong or strengthening economy which puts upward pressure on rates.

The California Association of Realtors released home sale data for March, and the data shows an apparent early start to the buying season locally. Statewide the median price for a single-family home was $565,880, which was up 5.9% from February and up 0.2% from March 2018. Total sales in the state were down 0.2% for the month and off 6.3% from 2018. In Los Angeles County the median price was down 2.9% for the month and 0.7% for the year at $525,520. The dip in prices and drop in rates created a large jump in sales as the number of units sold was up 36.3% from February, though down 6.3% of the number of sales in March 2018. Next door in Orange County the $809,500 median price was up 2.1% from February and down 1.8% from a year ago. Sales volume in the county was up 52% (not a typo fifty-two percent) from February and down 12.5% year over year. Overall, we see buyers coming to the Southern California market in a big way in March, and based on our activity in our office April and May numbers should be positive as well—though given the very strong increases in sales in March it will be challenging to match those numbers.

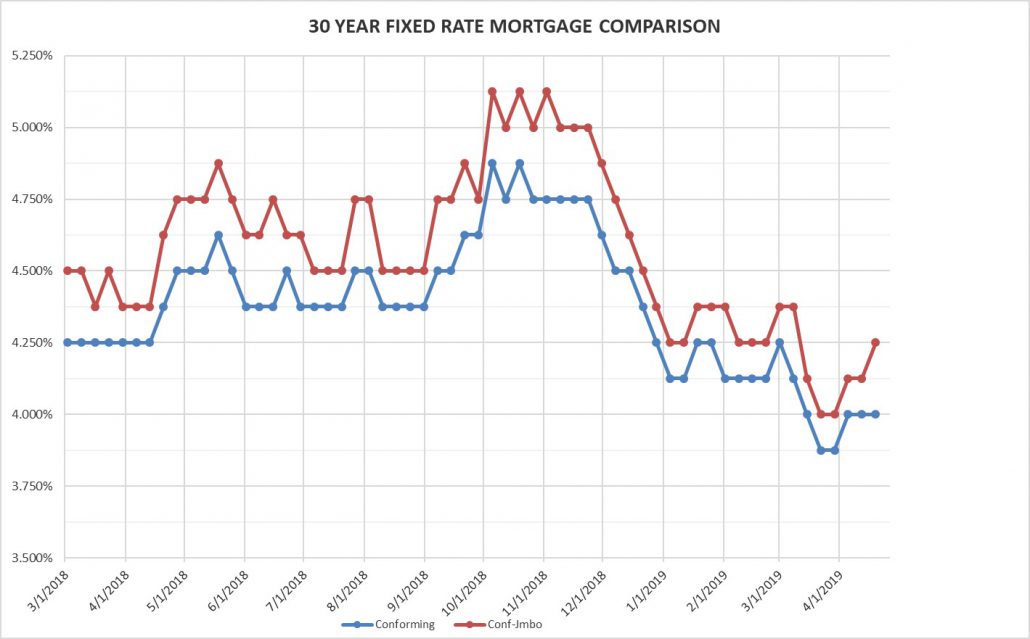
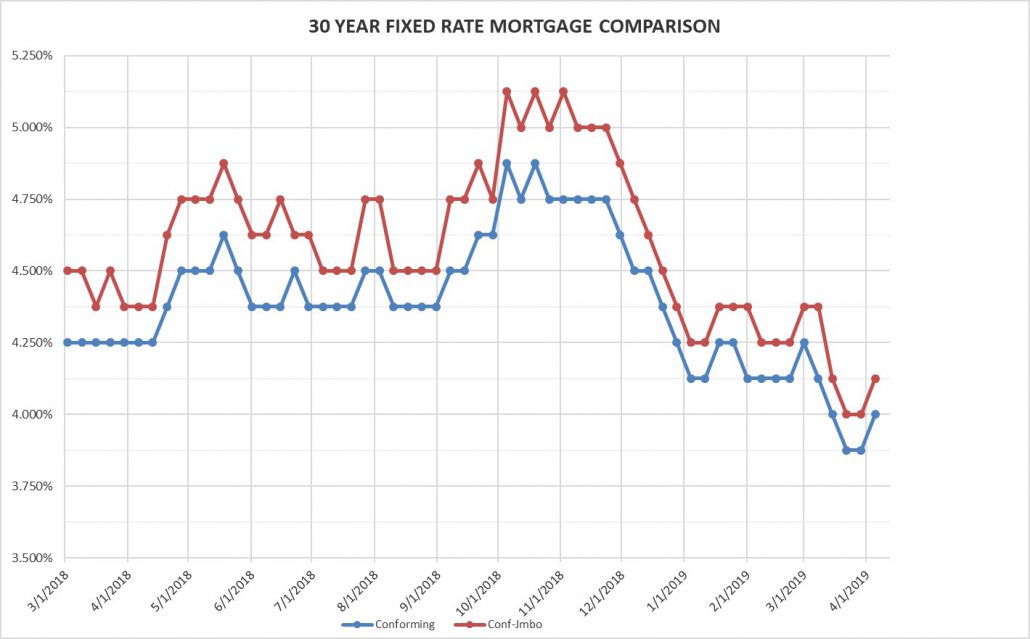
Rates for Friday April 19, 2019: The 30 year conforming rate is flat from last Friday and the high-balance rate (loans over $484,350) are up 0.125% from last week. The high-balance products have been interesting this year as they have changed independent of the conforming products due to market and regulatory forces. Fannie Mae and Freddie Mac have restrictions on what percentage of high-balance loans they sell in their pools, without going into the weeds it is generally around 10% of any given pool. If lenders are funding a large amount of high-balance loans they will push the high balance rates higher to slow the number of applications they get. In the past few weeks we have seen some odd pricing on high-balance mortgages, lenders have been getting more high-balance mortgages than they would like so they are trying to slow the flow. This week was one of those weeks, and since most pools are national in structure, a spike in sales in Southern California can skew the pool balance and an effort by lenders to slow their California high-balance volume.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.00%        Flat

30 year high-balance conforming                   4.25 %       Up 0.125%     

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Last week in this section I wrote about how much I love the Masters, Sunday morning watching Tiger Woods’ comeback reinforced that feeling. Watching extremely high-level athletes compete under pressure has always fascinated me. Their ability to execute under extreme pressure within the contest, compounded by the large audience in the arena of play and television cameras all around them is wonderful to watch. Some say, “well they are just playing a game and get paid very well to play it.” True, both those games support hundreds of thousands of families around the country. Their own managers, coaches and agents, those who work at the venues, if a team sport the hundreds who work for the organization, local establishments that depend on fans buying food, drink, souvenirs and lodging, television and radio personnel from the voices we hear to those who spool out the cables and hook them up.

Sports in America are about a $100 billion industry. The value of franchises depends on the performance in thousands of split second moments by individuals. Who are just playing a game. Tiger was just playing a game last week that generated tens of millions of dollars circulating in the economy. So were the other players in the tournament, but he was the one who executed the shots that did not go in a pond, or rolled into the cup.

I for one am glad I do not have to perform my job with several cameras recording me every move and slow-motion replay allowing commentators to inform millions how I missed a decimal point or forgot a guideline I needed to go back and double check. But then again, when I make the phone and get to say, “Congratulations! We funded your loan and you are now homeowners!” it would be great to have it broadcast with in-depth analysis!

We start Spring Break in the Smith household this week with the thousands of other Long Beach Unified families. That means the end of the school year is about six weeks away!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

Should we co-sign for our son or daughter’s home purchase?

Question of the week:  Should we co-sign for our son or daughter’s home purchase?

Answer:  Yes. No. Maybe.

As we have seen in the news lately, many parents will do anything they can to help their children get a leg up, to get a strong start, to ensure a more comfortable life. Some parents do it by trying to help their kids get into certain colleges, some parents do it by helping their children with the purchase of their first home. We all want the best for our children, the question is how far are we willing to go, or for many parents how far can we go?

It is hard for most families to purchase their first home, especially in Southern California. Our question this week is courtesy of long-time friend Andy who was inquiring, not for California real estate but in Central Pennsylvania—where home prices are also challenging for first time buyers given the average incomes and real estate prices. Andy’s daughter and son in-law want to purchase a home, but need a bit of help to do so sooner rather than later. I received an email from Andy with the question above, which after speaking about the situation boiled down to not should he help, but what is the best way to help.

There are several ways parents can help their children purchase a home. Each has different consequences, short and/or long term. A primary factor I have parents consider when we are having these conversations is what will be the impact on their lives today, and in retirement, or if they are retired their future.

Let’s explore the different ways parents can help their children obtain their own home.

SCENARIO ONE: One way some parents help is by purchasing the house themselves. They provide the down payment, they qualify for the mortgage, and they are the only ones on the title and mortgage. Their child moves in and the agreement is that at some point the parents will give the house to their son or daughter.

Typically, under this type of arrangement the child will make all, or some, of the payments for mortgage, taxes and insurance, either directly to lender, tax collector and insurance company. However, we have seen this situation where they do make the payments but pay their parents directly . If the latter the parents can then claim the payments as rent and then, if eligible, write off certain expenses. In this set-up, the parents essentially purchased an income property and rented to their child.

If the agreement is that the child will make the payments for the mortgage, taxes and insurance it is advisable for the parents to add the children to the title of the property. If it can be shown they have made those payments then they should be able to deduct the mortgage interest and property taxes (checking with tax professional first). In this scenario, the parents purchase the home, but essentially turn the home over to their child. In the future, by showing they have been making the payments and living in the property it will be easier for them to refinance in the future, should it be beneficial, and remove the parents from a mortgage obligation and obtain full title.

In this scenario, the consequences for the parents are that they are obligated on a mortgage and the tax liability of owning property. If there is some issue between the parents and kids and the children move out then the parents have to determine what to do with the house, sell it, rent it, make amends so the child moves back in. Having the children participate by making the housing payments to those owed directly creates more of an ownership mentality for them and makes it easier to transition the home later on. The risk here for the children is the parents still control the property and can sell it without the children’s consent—unless the children are on title.

In my opinion, this is the least desirable way to help your children obtain home ownership.

SCENARIO TWO: A more desirable way to assist your children in the purchase of their own home is to co-sign for them on their mortgage application. Most loan programs will allow family members to co-sign for mortgages for owner occupied purposes—what we call “non-occupant co-borrowers.” In this scenario, the child cannot qualify for the mortgage, usually because their debt-to-income ratio is too high. Depending on the parent’s total income and debt obligations, including their own housing payment, they may be able to co-sign for their child and enable loan qualifying. The parents would be on the mortgage and on title to the property.

The parents are still liable for the loan payment, as they are in Scenario One above, however the child is also responsible and have a lot more control over the situation than they do in Scenario One. Some parents are concerned, rightfully, how their being on the loan may impact their ability to get a loan in the future; most loan programs have a guideline for such a situation, known as “contingent liability.” If the parents can show the child has made the last twelve payments in a timely fashion then most mortgage programs will not count the payment for their qualifying.

In the future if it makes sense for the child to refinance then it is easier in this scenario than Scenario One as they are on title and on the loan so there is less to verify for the lender.

SCENARIO THREE: Show me the money! Or in this scenario, show your kids the money. As mentioned in the Weekly Rate & Market Update on March 1st, lack of funds for down payment is the primary reason most families wait to purchase a home. Many parents help their children purchase their homes by giving them the funds needed for down payment and/or closing costs. Many families have the income to qualify for a mortgage, but are short in the amount of cash they need. Enter Mom and Dad who can provide a gift for the funds required.

The process is simple, we only need three items for this scenario: proof of funds to gift, proof funds have transferred to the child, a gift letter signed by donor and recipient.

There are loan programs that allow for gift funds for all of the down payment and closing costs, some programs as low as 3.5% down, other five or ten percent.

If the resources are available this is the easiest scenario to enable parental assistance, and the one that has no long-term consequences other than not having those funds available for the parents own use in the future.

After some conversation, this was the route that Andy and his wife have taken to help their daughter and son in-law purchase their new home in Pennsylvania.

If you are considering helping your children with the purchase of their home in the future, or you are wanting to purchase a home but may need parental assistance, please call me so we can develop a strategy that works the best for everyone in the family and results in that homeownership.

Have a question? Ask me!

Fed says what? After spending part of 2017 and all of 2018 broadcasting they would very likely, extremely likely, raise their Federal Funds Rate three times in 2019. Over the past few months three rate increases became less likely based on the minutes from the Fed’s meetings and this week three increases become not likely at all and even one may not happen. This news was very interest rate friendly.

Existing home sales had their biggest one month increase nationally since 2015 in February. The National Association of Realtors reported today that nationwide sales of existing homes were up 11.8% from January, a huge jump for one month. Total sales were down 1.8% from last February per the report and the nationwide median price of $249,500 was up 3.8% from a year ago. The market is still being held back by lack of first time buyers, in recent history first timers have been about 40% of the market and last month only 32% of homes closed were first time buyers. Over all the news is slightly negative for mortgage rates as higher sales puts more demand on mortgages and shows signs of positive economic news.

Closer to home for most readers, data for California and Southern California was a bit mixed. Statewide total sales also eclipsed 11% for the month, with sales 11.3% higher than January, but down 5.6% from last February. The median price across the state dropped 0.6% for the month and showed a 2.2% increase over the past twelve months with a price of $534,140. The two biggest counties in Southern California showed no consistency between them. Median prices were down in both counties from January, with LA County down 4.3% and Orange County down 0.5%. LA’s median price of $541,390 was up 2.7% from last February, while Orange County’s $792,500 price was down 1.6% for the year. Total sales in Los Angeles Country dropped 2.5% from the prior month and 10.9% from 2018, while the OC saw total sales increase for the month by 1.0% but a sharp drop of 16.5% from last February.

What does this mean?  Year over year sales being down sharply in the region are obviously a concern for long term real estate activity, however prices are holding fairly well against the declining sales. With rates looking to stay low for some time the housing market, in my opinion, should move sideways with slight ups and downs neighborhood by neighborhood, city by city, county by county, for the year. Again, in my opinion.

Rates for Friday March 22, 2019: With the Federal Reserve news this week showing a lack of interest to raise interest rates in 2019 rates improved this week and we see the conforming rate drop for the third week in a row and the 30 year conforming rate dipping below 4% for the first time since the second week of January last year when it climbed to 4%. Time for a rate check? Call me.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year high-balance conforming                      4.00 %         Down 0.125%       

30 year conforming                                            3.875%        Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

College athletes in major sports are provided a scholarship that includes tuition, room, board and stipends for books and incidentals. The NCAA Men’s Basketball Tournament tipped off this week with teams from 68 colleges competing in a one-and-done contest to determine the national champion, also known as March Madness for the many games that are decided on the final shot and small schools knocking big schools out of the contest.

In 2016 the NCAA signed an eight year contract with some networks that will be worth $1.1 billion per year.

This year it is estimate that one-in-five Americans will participate in some type of pool or bracket challenge for the tournament. According to the American Gaming Association these pools will have about $4.6 billion in wagers on the line. Since the Supreme Court ruled that the it was unconstitutional for Congress to prohibit sports betting several states have passed laws allowing sports betting, as a result of all the new legal betting opportunities in around 25 states it is estimated that almost $4 billion will be bet on the games—40% more than on the Super Bowl in February.

Excluding ticket sales, merchandising and other revenue, the gambling and television revenues total almost $10 billion for the tournament which is held in ten days over three weeks.

But at least the players get a chance to go to college for free.

I have Duke beating North Carolina in the final game. Surprisingly, given the great history of both these teams and their intense rivalry, they have never met in the tournament.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Are we ready to buy?

Question of the week:  Are we ready to buy?

Answer:  In the March 1st Weekly Rate & Market Update I covered the number one reason to the question, “Why didn’t you purchase a home sooner?” from the California Association of Realtors 2018 Home Buyer Survey. That reason was “Needed to save for a down payment,” and it came up as I answered the question, should potential home buyers wait to purchase their new home until they have a 20% down payment. Sidebar, I failed to put in the 3/1/19 WR&MU that that most home buyers save for 5 years for their purchase.

The number two reason respondents did not purchase their home sooner was “waiting for our financial situation to improve.” In other words, are ready, or in many cases feel ready, to buy.

My knee hurts. It has been hurting for a little while and I am finally tired of the pain so I make an appointment. I call the orthopedic doctor’s office and make an appointment for next Thursday at 8:00 so he can operate on my knee and fix it.

Wait. What?

That is how many families go about purchasing a home, they try to go right to surgery.

When they think they are ready the go to an open house, or meet with a real estate agent, find a home they like and write an offer. Are they able to qualify for their mortgage? Could they be looking at homes that are higher priced, bigger, in better neighborhoods? Should they be purchasing a home right now, or should they spend more time working on different factors that impact their ability to qualify for the home they want to buy?

 Working with families purchasing new homes my experience has shown three types of buyers:

  • Buyers who write offers, get an offer accepted, go look for a loan, discover if they can qualify for the purchase of the home or not
  • Buyers who meet with me, determine the sales price, loan amount and loan type for which they qualify, go write offers and purchase a home they can afford
  • Buyers who meet with me, have some issues that prevent them from qualifying for the home they would like to buy, work with me to resolve those issues, become able to qualify for the mortgage they need to purchase the home they would like to purchase, go write offers and purchase a home they can afford

The vast majority of clients we work with fall into the second category. We meet, determine qualifying home price and terms and they work with their real estate agent to purchase a home they like and can afford. Often these clients have spent time on their own getting ready to purchase a home, and we find that many of them could have purchased a home sooner, but they did not know they would be able to do so.

Many of our clients fall into the third category. They know they want to purchase a home in the future, but are not sure how long in the future or what they need to do so they can purchase a home in the future.

The first category of buyers we see from time to time, thankfully most real estate agents will require their clients get pre-qualified, or better yet pre-approved, before writing offers and certainly before accepting them if they are representing the seller.

When we pre-qualify a family for a home purchase, we are answering their question, “are we ready to buy.” For some the answer is, yes immediately. For others it is either yes but not for as high a price as you would like or not yet; if this is the case we show where they are deficient in the qualifying guidelines and put together a plan so they will be ready to buy.

What deficiencies might potential home buyers have?

Not surprisingly, while there are many factors that going into a loan approval the primary ones are about you and money; how much do you make, how much do you have, how much do you owe and how well you pay what you owe. For most home buyers one of these determines their maximum purchase price and loan amount. You make great income and have little to no debt, but the funds you have for down payment determine your price. You have a nice savings account and little to no debt but your income limits the amount of a mortgage you can qualify for to purchase. You have good income, nice savings but a lot of debt and high monthly payments on your credit cards which impacts your qualifying. Or, good income, nice savings, not a lot of debt but in the past you had some serious delinquencies that could impact your ability to obtain a mortgage.

Some of these issues are easier to solve than others depending on your financial situation. By working with a mortgage professional as soon as you decide you want to purchase a home in the not too distant future you can work on the area(s) that you need to improve to increase your ability to qualify. My definition of “not too distant future” is up to 24 months, and it is routine for us to work with clients for up to that amount of time before they purchase their new home.

My knee has been hurting. I go to my chiropractor and after a few sessions she tells me I need to see a physical therapist. I see the therapist and he says it appears it is something structural that therapy will not cure and tells me I need to see an orthopedist. I see the orthopedist, he orders and X-ray and an MRI which shows some damage. I can either continue to live with the paid or have a surgery that will fix the issue.

Am I ready for surgery? I know more about my situation now that I have met with professionals who have guided me through the process—a much better scenario than just scheduling a surgery and letting the doctor figure it out once I am on the table.  

Before you have surgery, or buy a home, get the proper advice and take the proper steps to ensure you are ready when the time is right.

Are you ready to buy? Maybe, maybe not but the only way to know is to call me to make an appointment so we can see where you stand today for qualifying to purchase a new home, and if necessary what you need to do so you are qualified sooner rather than later.

Have a question? Ask me!

Economic data slow to reach the public due to the government shutdown is being published as the analysts play catch up. One of these reports was retail sales for January, which increased 0.2% in January after the largest drop in monthly sales in decade to end 2018. Removing auto and gasoline sales and the increase was a somewhat robust increase of 1.2% for the month. The news was neutral for mortgage rates, higher consumer activity is generally negative for rates since that is 65-70% of our economy.

Inflation is not a concern. Both the core Consumer Price Index and core Producer Price Index saw very modest increases in February, both up 0.1% for the month and CPI up 2.1% year over year and PPI up 2.3% annually (the “core” index removes food and energy from the basket of goods used to calculate the price indices as they tend to be very volatile and can skew data). The target rate of inflation for the Federal Reserve, and therefore an indication of whether rates should go up or down for investors, is 2.0% and the economy is pretty much on the target. The news is slightly positive for mortgage rates as it removes a reason for the Fed to increase rates, or for investors to behave with the expectation of higher rates and therefore cause rates to increase.

Rates for Friday March 15, 2019: Rates hit a fourteen month low this week due to economic stability and no major news that could create market turbulence. The analysts and forecasters are reading the data, technical factors that include chart shapes, ranges and other factors and it appears we should be in a period somewhat stable rates for a few weeks, “should” being key word. Now is the time to take advantage of the lowest rates we have seen since last January when they started to rise.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.00        Down 0.125%

30 year high-balance conforming                    4.375%   Down 0.25%  

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Everyone is Irish this week, because how many people do not like the opportunity to gather with friends and (or?) family and sip beer, eat good food, tell corny jokes and laugh? We’ll be spending part of the weekend with Leslie’s family for the annual gathering as March 17th happens to be our niece’s birthday, and as her maiden name is McCormick a gathering to tip a toast to St. Patrick in gratitude for ridding the homeland from snakes is appropriate. As well, her sister makes wonderful corn beef and husband Dave is a serviceable home bartender! Since my mother was a Kennedy and the “C” in my name is for Cleary after my great-grandfather I am partial to celebrations of the Irish bent I look forward to the annual birthday and St. Patrick’s festivities.

Wherever your St. Patrick’s Day weekend may take you I hope you spend it with those you love, those you like and those who make you laugh and that everyone returns to their homes safely.

Slainte!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Should we wait until we have a 20% down payment to purchase our new home?

Question of the week:  Should we wait until we have 20% down payment to purchase our new home?

Answer:  No. 

I have covered this topic throughout the years answering various questions that invariably lead to down payment, be it my thoughts on mortgage insurance (I like it, I will reprise reasons in coming WR&MU), cost of waiting to buy (covered last November), or borrowing from your 401(k) to help with your purchase, and many other questions of the week. We will cover it again today.

In a survey conducted by the California Association of Realtors the number answer to the question “Why didn’t you purchase a home sooner?” was “Needed to save for a down payment.”

Anecdotally, within my own and my co-workers’ experience the past several years, this is also a prime barrier we see with many of our clients who wish to purchase homes. The want to save more money for a down payment.

A bigger down payment.

It takes a lot of money to purchase a home in California, especially Southern California. Combine that with the prevailing sentiment of avoiding mortgage insurance and we have many families who could purchase a home today but are delaying doing so in order to save more money for a larger down payment.

It has always been my opinion that if you are able to purchase a home with the funds you currently have available you should do so. As I covered last November  with a very detailed comparison of two families purchasing homes in September 2017 versus 2018 the cost of waiting for accumulating a higher down payment to avoid mortgage insurance can, and usually does, costs you more in the long run.

The counter-argument is that he housing market is slowing. Last week the WR&MU had the home sales statistics for California showing the number of sales declining and prices, while flat year to year, were down from the prior month. If the market is slowing and prices may come down, does it not make sense to wait to purchase and let prices fall further and while waiting save more money for a down payment?

Only if your crystal ball is correct, if interest rates stay near their current levels and do not increase, if you are able to correctly predict the market, if you are certain the home in the neighborhood you want will still be available when you determine the timing is right.

Perhaps the biggest shift in homebuyers’ attitudes from the pre-2008 real estate bubble burst to the post-20008 real estate bubble burst has been their reason for purchasing a house. Many in the period of the real estate price balloon expansion prior to 2008 were purchasing houses, they were looking to make money on a real estate investment, they were using the value increase to obtain equity to finance consumer consumption. They were not buying homes so much as investments, as such price was what mattered most.

I have found that the homebuyers we have been speaking to and working with the past decade have been more interested in purchasing a home. They are looking for a place to raise their families, spend their retirement and hold for a long term rather than hoping for prices to climb so they can cash in.

This shift in mentality negates, somewhat, market conditions. If you are in a home for a long period of time, ten, fifteen, twenty years, minor market corrections are not of as much importance as if you were looking to purchase and then sell in the next three or five years.

If you have three, five, ten percent of the purchase price of the home you want to purchase available, and you can afford the mortgage payment buy the home. Buy the home today with the funds you have available and begin creating the home for your family. Yes, there may be a dip in the future of your home’s value, but does it matter if you will not be selling?

Our nature is to get what we want for the lowest price possible, but often while looking for the lowest price we are missing out on the best quality, best service or best product for ourselves and our family. Have you ever been shopping different airlines for ticket prices for your family vacation and see a good price but then take five or ten minutes more to see if there is a better price, then gone back to the site with the lower price and find there are no more seats available? You lost out on a potential bargain by looking for a better one. This happens to homebuyers as well, even in a soft market.

If you have funds available for a down payment, but are wanting to save more, please call me so we can discuss all your options for today and tomorrow when you have the funds saved you feel you will need. Those who know me know that I am not a “hard-sell,” I merely present options for you to make the decision you feel is best for you and your family, I cannot make you purchase a home, but I would like to show you the options of how you can—or if you are not able to show you what you need to do so you will be able to purchase your new home.

Find out your home buying options today, even if you want to wait until tomorrow.

Next week I will again answer the why I like mortgage insurance question, the week after I will cover the second reason families give for delay their home purchase as it coincides with work we do with our clients.

Have a question? Ask me!

Due to the partial government shutdown several economic reports for December are being released along with January data. One of these is personal income and consumer spending for December. December was an interesting month, personal incomes rose a very strong 1% for the month, but consumer spending dropped 0.5%, the largest drop since 2009. As a result of the increase in income and decline in spending personal savings jumped to 7.6%. Overall the news is mixed for its impact on mortgage rates, higher incomes should lead to higher spending and inflation, but the decline in spending and increase in savings should lead to a slowing in the economy.

Despite the drop-off in spending in December the 4th quarter Gross Domestic Product still grew by 2.6%. The rate of increase was slower than the 2nd (4.2%) and 3rd (3.4%) quarters but not enough to prevent 2018 to be the fastest growing economy since 2005. Holding back 4th quarter growth were a myriad of factors including housing and the trade deficit—and late in the quarter spending by consumers. Inflation for the quarter was 1.7% and year over year right at the Fed’s target inflation rate of 2.0%. Overall the news is negative for mortgage rates, a strong economy usually portends higher interest rates. However despite the strong growth in the year we have seen rates from recent highs in the fall of 2018.

Looking ahead, consumer confidence surveys released this week saw a surge, increasing for the first time in four months as most surveyed see better conditions ahead for themselves and their families. Will this confidence lead to increased spending and continued GDP growth above 2% and possible 3%?

Rates for Friday March 1, 2019: After three weeks of steady rates we see a slight bump in interest rates from last Friday. There are many small reasons why this has occurred, mostly investors chasing higher yields elsewhere which puts a damper on prices and therefore higher returns, i.e. rates, in the market. I do not see this as a trend.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.25        Up 0.125%

30 year high-balance conforming                   4.375%   Up 0.125%       

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Sometime during our first year of marriage I got a bad head cold and Leslie said, “My dad has always said it takes three days to get a cold, three days to have it and three days to get rid of it.” Over the years I have noticed Don is right about this. Today is day one of the three part series for me, which means the last three days have been the wonderful, sneezy, snuffling, achy, sleepy portion of the cycle. Blech. Despite Don’s wisdom that this too shall pass, I am one of those who takes everything available, DayQuil, Mucinex, Emergen-C, Afrin, NyQuil, Ibuprofen, water, soup, whiskey…some day I’ll learn that I should just stick to one and ride it out.

I hope your week was spent in better health and that you are able to have the three-three day cycle avoid you and your household this year!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
Why should we shop for our new home in the rain?

Question of the week:  Why should we shop for our new home in the rain?

Answer:  Unlike most of the country, Southern California—most of California, has rain only a few months of the year, usually between late October and early to mid-March. Rain can be extremely destructive to property over the long-term and the opportunity to see how a property is impacted by rain should be a major factor in your home buying decision.

Consider the home owner who looks at homes in early April and finds one they really like. The last substantial rain in the area was in late January and early February. The property had some issues in the prior rainy season. Some small leaks from the roof and a skylight resulted in water spots on the ceilings. Windows on the south side of the family room leaked and resulted in some damage to part of the molding. In the rear of the house the run-off from the gutters pools around the exterior walls as high as three to four inches and drains by seeping below the foundation.

The seller of the property painted the interior of the home, including the ceilings with the water spots. Took some putty and paint and patched the moldings on the windows. Washed the exterior walls and planted some flowers and large plants where the water pooled and showed evidence of water creep.

The couple purchases the home and after a very hot spring, summer and early fall an El Nino arrives and there is significant rain and wind from early January through February—not dissimilar to our weather this year. Early on they discover water dripping through the ceiling in the kitchen and dining room, water was coming in through the south side of the family room and the water was getting very high where the gutters drained so that they had to carve a trench into their back yard to release the pond that was developing.

In this case the seller knew about the issues and did not disclose them to their real estate agent nor the buyers. Their defense could be that it had not rained for some time as the prior winter was fairly dry so they are not liable for the problems with the rain and water damage.

Since the trouble spots were covered up the physical inspector hired by the buyers could not detect the issues as everything appeared normal and there is no way to adequately test for how a property will react when several inches of rain falls over a short period of time.

The buyers incur expenses to replace their roof, replace windows and install hardscape and drainage systems to ensure water is kept away from their home and drains properly. The good news is their home is in tip-top shape and ready for foul weather; the bad news of course is thousands, tens of thousands, of dollars needed to be spent right after they used their savings to purchase their new home.

Imagine if the buyers had been able to inspect that same home this weekend after the storms we have had come through in the past several weeks? Any water issues a home may have would be evident and potential buyers would have a very good idea of what corrective measures would need to be taken and have professionals estimate costs to cure the issues. Buyers could then have these costs in mind as they determine whether to make an offer or not and if they do so how the price may be impacted in consideration of future costs.

It is important for me to note that the scenario where a seller purposefully hides known defects is not the normal case of real estate transactions. The same couple could have purchased the same home and the home had no noticeable issues with rain water and weather, however after a long summer and possibly eight or nine months before the next rain the same issues could present themselves. Southern California weather takes its toll on buildings with the constant sun and dry weather.

While summer is the hot season for temperatures and also housing markets, looking at homes to purchase during the summer can be a detriment in the long term. I have always felt that in Southern California it is the wet and windy winters that are the best time to house hunt in order to see how your potential new home handles our worst weather.

If you are considering purchasing a new home please contact me so we can develop a strategy for your purchase and the best mortgage options and purchase price to acquire your new home.

Have a question? Ask me!

The economic data presented this week suggests rates should go lower. Long time readers of the WR&MU know that good economic news pushes rates up and not good news pushes rates down. News that puts upward pressure on rates are inflation over about 2%, strong retail sales, strong GDP growth and strong job market; the opposite of those actions on those factors generally leads to lower rates.

Prices were flat for consumers in January, literally with 0.0% increase in the Consumer Price Index. Held down by a drop in gasoline prices. Stripping out energy and food prices, called the core price index, prices increases 0.2% for the month and was up 2.2% year-over-year. The Producer Price Index did not fare as well, dropping 0.1% in January after a 0.2% drop in December. The news is positive for lower rates as higher inflation is healthier for the economy and growth.

Wages bucked the price trend, with “real” wages (adjusted for inflation) rose 0.2% in January and year over year are up 1.7%. Good news for the rank and file (excludes executives) whose wages are up over the past year by 2.1% . The stronger wage gains are not positive for rates as higher labor costs theoretically are passed on to consumers creating higher prices, known as wage inflation. Strong wage inflation puts upward pressure on rates.

With the government shutdown concluded we finally get retail sales data for December, and it is not positive. In fact, sales in December dropped 1.2%, the biggest decline since September 2009. There were numerous factors that could have contributed to the large decline, poor weather, the start of the shutdown, mummers of recession and a huge drop in gas station receipts (down 5.1%) due to lower prices. It appears, however, that the drop was attributed to other factors as well and it puts into question the strength of the economy in the 4th quarter. The biggest surprise in the report was a 3.9% drop in internet sales, but also dropping were sales across the board at restaurants, bars, apparel, home furnishings, virtually every consumer category. The news is very friendly for lower rates as consumer spending is 65-70% of our economy, a slow down in consumer spending opens the door for those mummers about recession.

Rates for Friday February 15, 2019: There is a lot of information influencing markets, and while rates have been stable week to week they are ready to break out higher or lower. The ongoing trade negotiations with China, political fighting continuing in Washington over budgets and expenditures and the not great economic news all are influencing investors. Looking ahead rates should go lower based on data, but as we have seen over the past six to twelve months, data is not the primary driver in investor decisions that influence rates and markets.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.125    Flat

30 year high-balance conforming                     4.25%      Flat     

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Continuing weather talk from above, I like the stormy winter (for California) weather. I can say that because I do not live in an area negatively impacted by mud-slides or blocked highways. It can interfere with weekend activities, but spending a Saturday or Sunday inside cozied up with sweatshirts, hot beverages and a good movie or book definitely has appeal.

Unfortunately, the rains are part of the California Trilogy of Tragedy which occurs when we have years of deluge and not drought. The rains cause tremendous abundance of undergrowth and grasses that die off in the summer dry weather and become tinder for the fall to start and spread wildfires which burn off all the ground cover and create barren landscapes that become mudslides the next rainy season. Rain, fire, mud, repeat.

Fires and mudslides in the middle of the wilderness are not tragedies, they are part of nature over the eons and millennia; when homes and developments are permitted in and immediately adjacent to wilderness areas the trilogy results in tragedy for towns and families. We will continue to see the cycles occur with loss of homes to fires or slides as long as local and state government issue permits for development collecting tax dollars in return.

Off my soap box.

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

Are we headed to another collapse in real estate?

Question of the week:  Are we headed to another collapse in real estate?

Answer:  In last week’s Weekly rate & Market Update I wrote that this week I would compare the real estate market prior to the collapse in the industry that led to the Great Recession with the current market. The impetus for the comparison is the slowdown in real estate sales in number of units sold and in some areas decline in prices, this has many wondering if we are heading to another major market “correction,” i.e. large drop in values for homeowners.

It is a valid question for many who experienced the market collapse that started in 2007 and continued for more than a year. The anxiety and fear of the future and other negative emotions many experienced are easily brought forth when it appears that a similar lead up may be occurring in our current economy and real estate markets.

For those who do not wish to read through my reasoning (which in typical fashion is a bit extensive) I will give you my answer to the question of the week: No.

No, we are not headed to another collapse in real estate.

There are several reasons why I do not see a significant decline in real estate on the horizon, defining “significant” as a decline in prices of more than 10% year over year.

The California Association of Realtors report on December 2018 sales notes that units sold declined for the eighth straight month, while active listings increased statewide for the ninth straight month. Statewide there was drop from December in the median price, but the median price was higher from the prior year. The data statewide and regionally throughout the state certainly shows a slowing real estate market. The question is how long and severe will such a slowing be?

Prior to the market collapse a decade ago the market went from hot and steamy to slowing, similar to what we have experienced over the past several years statewide and in Southern California, with prices increases up to 10% or more year over year in most regional markets and increasing total sales. The difference as to why the next steps will not mirror the collapse a decade ago is the basis of the run up in prices—the expanding of the balloon that eventually popped. No, not popped. Exploded.

Most real estate market slowdowns occur when price increases outpace the ability for consumers to afford to purchase homes in the markets they desire, which led to decreased demand. Eventually demand decreases to the point that sellers must lower their prices if they want to sell their homes. The amount of decline in the overall market depends on how many sellers need to sell and how far they are willing to drop the price of their homes to attract buyers.

Factored into the demand feature is not only the cost of the product, a home, but also the costs to obtain the home in terms of financing. If there were not thirty-year fixed rate mortgages with low down payment requirements available to finance homes our prices would be up to 90% less than they are today. Because of the increase in rates over the past year to cost to finance a new home purchase has exacerbated the increase in home prices putting a bigger damper on ability to purchase, which decreases demand. So not only are rising prices dampening demand, but increasing rates also kept buyers out of the market.

Having to pay more to finance an asset that also costs more reduces the amount of qualified buyers. Fewer buyers leads to less demand leads to softening prices. Simple economics.

If this is similar to what occurred starting in 2007, why should the result not be the same?

Three major reasons: Ability to finance, purpose of purchase and refinances.

The first reason, ability to finance, is by far the primary factor in the market collapse and the biggest reason our current market slowdown is in no way similar to the collapse. Last week in the WR&MU I discussed QM and non-QM mortgages, a distinction created by the Consumer Financial Protection Bureau in reaction to the part the mortgage industry played in the creation of the housing bubble and ultimate explosion.

Starting around 2000 Fannie Mae and Freddie Mac developed and continually refined Automated Underwriting Systems for loan approvals. As more and more data was available to Fannie and Freddie their AUS became looser and looser—meaning it became easier and easier to obtain loan approval for residential mortgages. By around 2003 lenders were guaranteed to have their conventional mortgages purchased by Fannie or Freddie is there was an AUS approval in the mortgage application file as long as the required documentation as listed by the AUS approval was in the file. After around 2003 the required documentation became less and less. Eventually, Fannie Mae and Freddie Mac were enabling mortgage fundings on the vast majority of loans funded in the country that today would be labelled as “Alternative,” or non-QM mortgages.

Example of less and less. In 2001 Susan and James purchase a $350,000 home with 10% down and a 90% conventional fixed rate mortgage. We run their information, credit report, monthly income, employment history, liquid assets and the sales price through the AUS for Fannie Mae. We receive a result of “approve-eligible,” meaning the loan is approved and eligible for purchase from Fannie Mae provided the conditions listed in the approval are met. The conditions in 2001 would call for proof of income as exhibited by most recent two years’ W2s and recent paystubs covering 30 days showing year to date income. Proof of down payment showing at least two months bank statements with any deposits that are significant and not from employers sourced and explained. Debt obligations and history as shown on a tri-merge credit report (Equifax, TransUnion and Experian). Value of property supported by a licensed appraiser providing a complete report including inspection of the property.

In 2006 Susan and James what to purchase a $550,000 home with no money down, obtaining a loan covering 80% of the price with a Fannie Mae loan and 20% with a Home Equity Line of Credit from the same lender. The lender guidelines for the HELOC are that they will accept whatever documentation is required by Fannie Mae’s AUS system. We interview the clients and obtain their income and assets, pull a credit report and have the purchase price. We upload the information to the AUS and receive and “approve-eligible.” The approval conditions require we perform a verbal verification of employment to ensure the borrowers are employed. Require that the funds required for closing are brought to escrow. Since the purchase price of the property is consistent with the values in Fannie Mae’s property valuation software for the zip code no appraisal is required.

In 2001 Susan and James with 10% down had to prove their income, funds for closing and their source and the value of the property is market value with an appraisal.

In 2006 Susan and James with no money down did not have to verify their income, funds for closing or that the purchase price was market value.

By 2006, Susan and James were a declining part of the market, they wanted a 30-year fixed rate mortgage. By 2006 a large portion of the market consisted of borrowers looking for adjustable rate mortgages so they could buy very expensive homes with very low mortgage payments—in the first year(s) of ownership. In the years of the bubble expansion more and more borrowers were purchasing and refinancing using adjustable rate mortgages.

In the run-up to the housing bubble explosion most borrowers did not go through any type of even quasi-rigorous approval process. Fannie and Freddie, and therefore lenders, were funding stated income, stated asset, stated value loans. Anyone with decent credit could buy a home. Many purchased homes with adjustable rate mortgages ignoring that in the future their payments would be higher.

The CFPB’s Quality Residential Mortgage (or QM) guidelines created the primary reason a future major real estate collapse is less likely because in the past ten years borrowers have had to prove income, verify assets and have the value confirmed by a licensed appraiser.* As well, many adjustable rate products are no longer available, and those that are available are very rarely used by home buyers. When you have a real estate market where the buyers are fully qualified to show they have the ability to make their mortgage payments your incidence of foreclosure will decline astronomically compared to a market where a significant portion of buyers were not adequately qualified to show they could make monthly mortgage payments.

*In recent years “property valuation waivers” have once again been issued by Fannie and Freddie through their AUS approvals. As well, as discussed last week, alternative mortgages are a growing sector of the market which depend more on assets than verifiable income for approvals. While growing, this segment of the market is a very small percentage of the total market.

Reason number one the current market is not mirroring the exploded market: Almost everyone who has purchased a home in the last ten years has the ability to make the mortgage payments as long as they are employed.

A not insignificant portion of the market were not buying “homes,” they were buying investments and doing so with very little or no down payments.

Because financing was easy the market became crowded with home buyers. More demand leads to higher prices. As prices climbed and qualifying became easier, and cost to enter the market dropped, more buyers entered the market and many began chasing home purchases so they could cash in, buying a home then reselling in a short period of time and purchasing a more expensive home, and repeating the process.

Then the perfect storm hit. With prices rising demand began to slow. On Wall Street, investors discovered that the mortgages they were buying were not as high a quality as they were told; the mortgages were not underwritten to high standards to show borrowers’ ability to repay, but rather were very risky. Investors stopped buying mortgages. Lenders started going out of business. Inventory climbed. As inventory climbed prices started to decline and homeowners found themselves with property in which they owed more than the property was worth. They could barely make their mortgage payments. Why struggle to pay a loan for a property that is worth less than you owe? Homeowners walked away from their properties, creating a flood of foreclosures and banks putting homes on the market at lower and lower prices.

Boom.

Reason number two our current market will not continue to mirror the collapsed market, there is a strong emotional connection to the property, it is a home not an investment. If there is a decline in value, while concerning, it will not create a reason to sell because the homeowner has a long term plan and still have equity in their property.

The third reason, refinances, were no small contributor to the market collapse. As prices rose many homeowners took advantage of their increased equity by refinancing, under the same easy qualifying guidelines, to pull out their equity either with cash-out refinances with fixed or adjustable rate mortgages, and/or with Home Equity Lines of Credit. Some homeowners engaged in multiple cash-out transactions from the early 2000’s into 2007, pulling hundreds of thousands of dollars in cash from their properties. What happened when prices dropped and they owed a lot more than the value of their property? Yet more inventory on the market pushing prices down more and more.

The real estate market that has grown over the past decade has done so due to very solid fundamentals. Buyers have had down payments, a stake in the property. They have financed their purchases with mainly 30-year fixed rate mortgages that they have shown are within their ability to pay based on their income, debt obligations and history of making credit payments. They have purchased homes for their families for the long term, not short term investments intended to create profit.

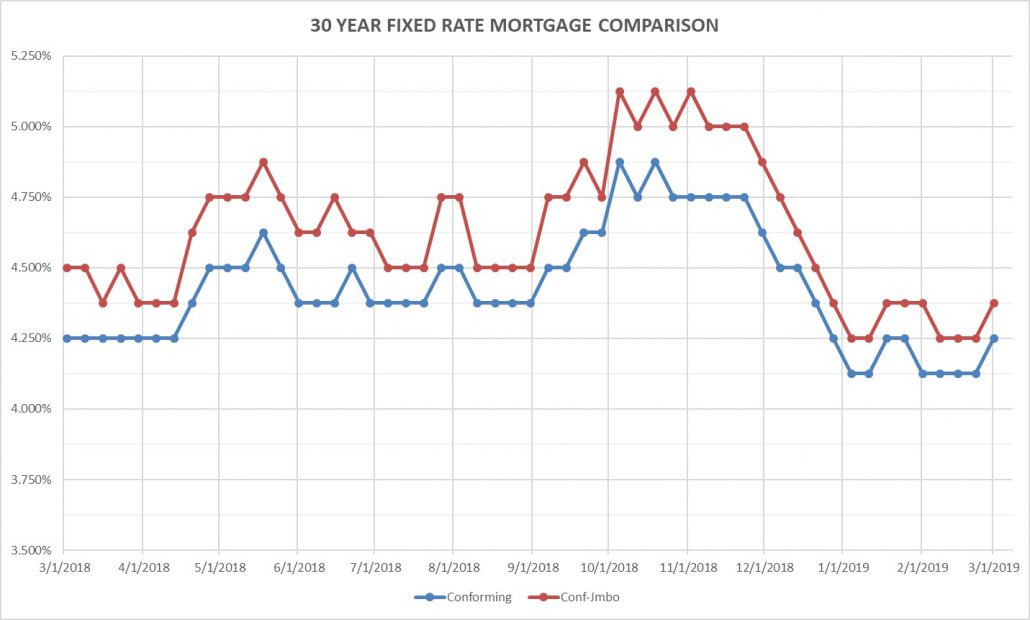
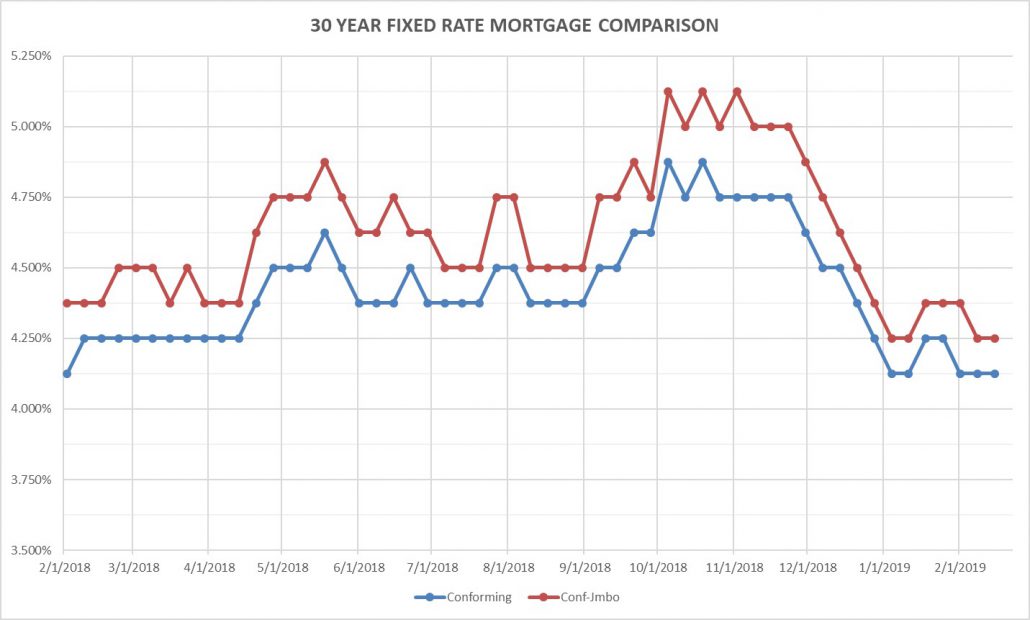
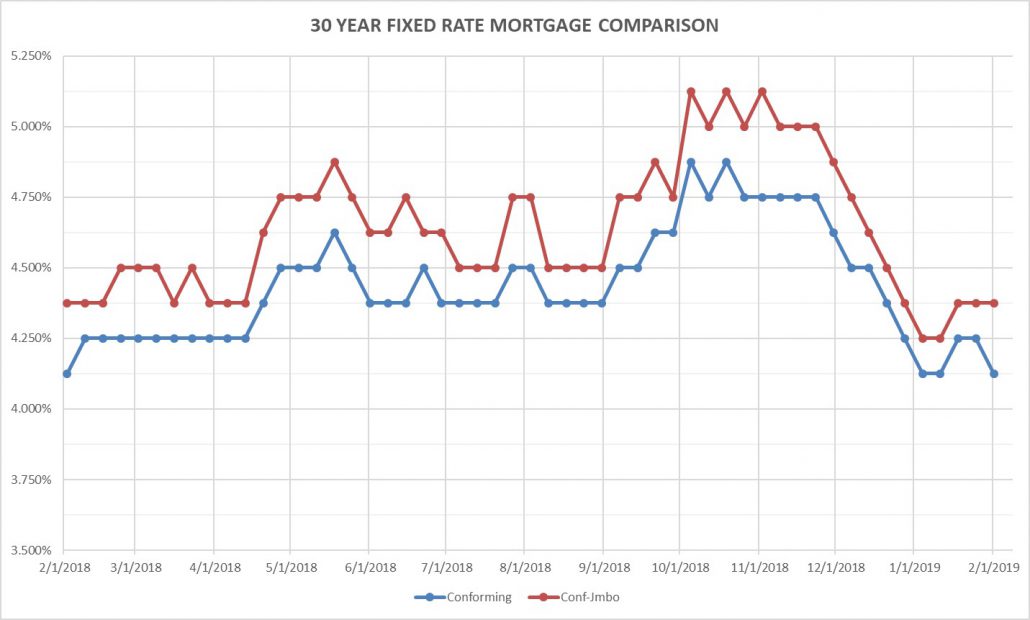
As well, the underlying interest rates for most homeowners are very low. From 2005 to 2006 conventional fixed rates climbed as high as 6.5%. Since 2010 the highest the conforming fixed rate has been is 5.125% in the first week of January 2010, dropping to 3.125% in the last quarter of 2012 and reaching a high of 4.875% for two weeks in October 2018.

Our housing stock is owned by homeowners who can qualify for their mortgage payments, have mortgages with very low fixed rates, have equity in their property—in most cases significant equity, and are staying in their homes for the most part until a life changing event like having children, kids graduating from high school, change in jobs or retirement.

After price run-ups all markets will have periods of no to negative growth, i.e. prices flatten or drop. We are experiencing this in the current market. Will it lead to another collapse? Because of the very strong fundamentals of homeowners the answer is “No.”

The greatest risk to the real estate market is the overall economy and job and income loss. Should we experience very high amount of unemployment in the region, state and country that can, and will, impact the real estate markets. But even then I cannot foresee any type of collapse in prices near what we experienced a decade ago.

Have a question? Ask me!

No bump now or maybe later. This week the Federal Reserve Open Market Committee had a meeting, this is the group that raises and lowers the Fed’s rate charged to member banks to borrow money. It was not a big surprise that the FOMC did not raise rates. What did catch everyone off guard were statements by Fed Chair Jerome Powell at a press conference. Powell’s comments indicated that the Fed may not increase rates two or three times in 2019 as previously intimated. This alone would be enough have investors believe low/er rates are in store for 2019, add in his comments about the Fed’s balance sheets and belief becomes reality.

Looking to help stimulate economic growth after the Great Recession, the Fed purchased over three trillion dollars of fixed rate assets comprised of U.S. Treasury bonds and conventional mortgages from Fannie Mae and Freddie Mac. In 2018 the Fed announced that it would be selling these assets from its balance sheet in systematic, “automatic” as described by the Fed, way. This news, and subsequent going to market with billions of dollars of fixed rate assets to sell put upward pressure on rates. The news from the Fed that it would be looking to curtail sales in the future was welcomed by investors and resulted in stocks climbing and rates decreasing.

The direction was reversed on labor news released today. As reported by the Department of Labor payrolls increased by 304,000 workers in January and job growth continues to be very strong. The headline unemployment rate edged up to 4.0%, mainly due to filings by some federal workers during the shutdown, aided by more individuals entering the market looking for work. Wages and salaries continue to increase as well, not surprising as employers seek more employees—supply and demand works for wages as it does for home prices. Overall the news is mortgage rate unfriendly as higher labor costs should lead to higher inflation, which should lead to higher rates. For the time being inflation is within the range of 2%, the Fed’s target.

Rates for Friday February 1, 2019: Even with a bit of an uptick today following the jobs data the conforming rate is down slightly from last Friday with high balance rates remaining flat for the week.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.125%     Down 0.125%

30 year high-balance conforming                     4.375%      Flat    

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Anyone send any selfies playing golf, strolling on the beach or enjoying a beautiful sunset earlier this week to friends and family in the Midwest or East Coast? It is weeks like this that make the “weather tax” to live in Southern California worth the cost.

Once again, the New England Patriots are in the Super Bowl, entrenching themselves in the most reviled professional team in the country for those not living north of Connecticut. Love them or hate them an objective view must be that they are perhaps the greatest spots dynasty in American history during the Belichick-Brady era. Unlike the Yankees or Celtics of yore who controlled their players throughout their careers and contracts, the Patriots like other teams in the NFL must create a new team every year due to players leaving through free agency and looking for replacements through free agency and the draft. Despite all the roster change over, like many teams face, owner Robert Kraft has provided outstanding leadership to enable the team to be by far the most successful over the past seventeen plus years.

Perhaps the Rams can duplicate what my favorite team, the Eagles, did last year and beat the Patriots. I am of the opinion that they will not but that is why they play the game. Brady is 5-3 in Super Bowls, his only three losses coming to NFC East teams, the Giants twice and the Eagles last year. One thing about Patriot Super Bowl games, they are always close. Of their nine games with Brady at QB the largest point spread is eight points, last year and three games have been decided by only three.

Enjoy the game and have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
1-11-19: What are our mortgage options for remodeling our home?

Question of the week:  What are our mortgage options for remodeling our home?

Answer:  There are several options for paying for major home improvements or remodeling. Most commonly used for paying for major home projects are cash, a home equity line of credit or fixed rate second trust deed, new primary loan with cash out, new renovation loan, or possibly tap other resources. Here are some basic guidelines for the various financing options.

Cash: Depending on the scope of your project you may have enough money saved to pay for your construction project. The obvious advantage is lack of any interest costs and monthly payments. Keep in mind that many remodel/renovation projects can end up costing more in time and money so make sure you have enough to cover cost over-runs as well as whatever post-project expenses you may have—such as new furniture, floor coverings, etc. If you are using cash for your remodel you may want to obtain a home equity line of credit for a small amount to cover over runs to ensure you do not run out of funds during the project and then may be unable to obtain financing because part of your house is torn apart and not yet put back together. If you do not need to access the available funds that is great, but if you do you will be prepared and seamlessly be able to continue and finish your project.

Home Equity Line of Credit (HELOC): A HELOC is like a credit card, you are approved for a maximum amount of credit and then you can access as much of the funds as you need up to the credit limit, you make payments based on the amount of the outstanding balance. A big advantage of HELOCs and remodeling is you only pay for the amount of money you need when you need it. For instance, your project is estimated to be $50,000 with 20% paid upfront to get started and then other funds paid to the contractor at certain points of completion with the final amount due when all is complete. You sign the contract and access $10,000 and pay the contractor, you bill comes the next month and you owe the payment due based on $10,000. The next month you pay another $15,000 to the contractor and not having paid any principal on the first payment, you made an interest only payment, your next bill will be based on the $25,000 balance. This gives you flexibility based on how you use the funds available.

Another advantage of HELOCs is many lenders will provide lines of credit at a higher loan-to-value (LTV) than you may be able to obtain with a fixed rate loan or traditional mortgage. This enables you access to more funds than you would otherwise be able to obtain.

The disadvantages to HELOCs are the rates are variable, tied to the prime rate so over time it is hard to budget total costs; for example, since December 2016 the rate has increased 2%, while during this period the 30 year fixed conventional rate is only up 0.25% (after being higher by 0.75% a few months ago). The other disadvantage is self-imposed by the borrower—interest only. The minimum payment due on most HELOCs is an interest only payment, many borrowers fall into the habit of paying interest only which results in a large balance remaining on the loan which has to be paid at some point in the future either through a refinance or sale of the home.

Fixed rate Second Trust Deed: This financing instrument operates like a traditional fixed rate mortgage, however because it is in second position the rate is higher than available primary mortgages at the time of the transaction. The advantages of the fixed rate second are the ability to budget exactly what the payment will be for the period of the loan (generally available in fifteen or twenty year options) and if your current mortgage has a rate that is significantly lower than your current rate you can retain that rate and payment.

The disadvantages of the fixed rate second are many lenders restrict the LTV to 80% (same as most primary mortgages) and the higher interest rate.

Cash-out Refinance: This option is pretty straightforward, you refinance your existing mortgage and increase the amount borrowed to cover the funds you need up to the LTV allowed by the loan program. Most cash-out programs limit the loan balance to 80% of the appraised value of the home so if you are going with this option it is a good idea to have a good estimate of the value of the property.

The advantages of the cash-out refinance option are that you have a 30 year fixed rate mortgage. This provides you the lowest possible payment due to the long amortization, a fixed rate throughout the term of the mortgage which enables you to budget your monthly housing payment with certainty. Another benefit for many homeowners is depending on how long you have had your current mortgage and the increase in monthly payment may not be as high as you would expect; for instance we are closing a loan with a borrower accessing $75,000 and their payment is going up only about $275 per month, whereas their option on a fixed second increased their payment by almost $700.

Disadvantages of the fixed rate option are you are provided all the funds at closing and begin making payments on funds that may be sitting in the bank waiting for your project to begin and through the finish. Another is your interest rate may increase from your current mortgage rate.

It needs to be noted that when pricing mortgages a cash-out refinance are costlier than a rate and term refinance and a purchase transaction. The higher the LTV the more expensive the loan, conversely if you have a lot of equity in the property your costs would be lower if you LTV falls below certain price points based on the appraised value and how much your are borrowing.

Renovation Loan: This option is a combination of a traditional fixed rate mortgage and a HELOC and can be used to purchase a home you wish to remodel or as a refinance of your existing home for major renovations. We will use as an example a refinance.

Your current home is worth $550,000 and you owe $325,000. You wish to add a bedroom, a full bathroom and remodel the kitchen. The total costs are $125,000 and after the work is completed the value of the property will be $645,000. We complete the loan application for a mortgage of $450,000, $325,000 to pay-off your existing mortgage and $125,000 for costs to remodel. With our loan package besides the standard information we would need to show you qualify we will also need plans and estimates of costs from your contractor. During the loan processing we will make sure your contractor is approved by the lender and have an appraisal completed that includes the current value and the value of the home after the project is complete.

All goes well and the loan is approved and we fund the mortgage, your existing mortgage is paid off and the excess funds are placed in an escrow account controlled by the lender. After certain parts of the project are completed you request a draw from the account, the completion of that part of the project is verified and funds are transferred and you can pay the contractor. At the end of the project you have used all the money on the mortgage and your contractor is paid.

Advantages of this option are that you have a 30-year fixed rate mortgage upon completion of the project and the rate is competitive with a traditional mortgage or cash-out transaction. Another advantage is your contractor is vetted by the lender—which in our experience has resulted in some borrowers needing to change contractors after issues arose regarding insurance, licensing or past issues with the contractor that the lender discovered the borrowers were unaware of when they selected the contractor. This may sound like a negative, however should something occur with the contractor during the project it is a nightmare; knowing a contractor had issues in the past decreases the opportunity for such nightmares to occur.

 A disadvantage for many borrowers is the process to get to loan approval, which is longer and significantly more thorough than the traditional approval process—it is a bit more time and effort but understandable due to the nature of the project. Another disadvantage for some is the draw process where the contractor is not paid until certain completion points in the construction. Many contractors want funds before they start the process, using the renovation process they may not get the funds until after the process; some borrowers mitigate this issue by fronting the funds to the contractor and then getting reimbursed through the draw process.

Piggy-back: Some homeowners do their own version of the renovation loan by maximizing their funds available with a traditional 30 year fixed rate mortgage and then add a HELOC onto the property for additional funds. For instance you need $80,000 for your project and a cash-out refinance will enable you to obtain $65,000, you obtain the additional $15,000 needed on a HELOC—what we call a piggy-back transaction as your HELOC piggy-backs on your first mortgage. The advantage of the fixed rate 30 year loan for the bulk of the funds needed combined with the higher LTV of the HELOC lets you complete your project with the best of both options.

Reverse mortgage: Yes, reverse mortgages can be used for home improvements if the borrower qualifies and enough equity is in the property.

Other options can include borrowing from the bank of mom and dad, possibly borrowing against your 401(k) or a margin account on an investment account.

One of my favorite books we used to read to the kids was If You Give A Pig A Pancake. I usually encourage any family looking to do an extensive remodel to read the book as it is a good metaphor for many such projects. A major pitfall for most homeowners is underestimating the amount of work and costs that will need to be done to accomplish their goal of another bedroom and bath and a remodeled kitchen. Once walls are open what will the contractor find? Out of date and code electrical? Inadequate framing? Foundation issues? A rotted out floor under the shower? The original choices for cabinets or fixtures are not available adding time, and/or costs, to the process? You forgot that with the newly remodeled home that you now need furnishing?

A high percentage of the time when I have clients undergoing a remodel they let me know that even though they thought they were being somewhat liberal in the costs they still were short of what was needed. Read the book and imaging instead of a pig going through your home in search of a pancake it is your remodeling project needing more and more done to ensure completion.

Be very thorough in your plans, go deep into your interviews with contractors as to typical issues that come up, and possible issues given the age of your home, location (for instance we are on expansive clay soil which causes foundation issues—not all contractors are aware of this) and scope of your project.

All that said, I usually counsel clients that are considering extensive home improvements that before they commit to explore the options of what homes are on the market that would achieve the same objective. If you are looking to add a bedroom, bathroom, modernize your kitchen or other work that entails a lot of time and money, evaluate the current value of your home, what your net proceeds would be if you were to sell, what loan amount and sales price you will be able to qualify for and feel comfortable paying and then look at the local market to see if it makes sense for you to purchase what you want.

You may find that you prefer to remain in your current home and endure the remodel process, or you may find that you would benefit by purchasing a home that meets your needs.

Whichever route you choose to take please contact me to go through all your options and the advantages and disadvantages of each.

Have a question? Ask me!

Words matter, especially when they are the words of the Federal Reserve Open Market Committee (FOMC)—the group that sets the Federal Reserve borrowing rates which impact other rates such as the prime rate. The minutes from the last FOMC meeting were released this week and they showed that while all the voting members say “yes” to increasing rates at the last meeting there was some discussion by some to not raise rates. As well the minutes showed that future rate increases are not guaranteed. This is positive news for mortgage rates.

More positive rate news today as the Consumer Price Index dropped in December for the first time in nine months, primarily due to lower gasoline prices. Also declining was the year over year cost of living, dropping to 1.9% growth from the annualized growth of 2.2% in November. The 1.9% price increase was the first time since August 2017 the important data point was below 2%. The news is very mortgage rate friendly as the Fed uses the data for their gauge of inflation and the desired price increase for the Fed is 2% per year. If the price decrease remains below 2% moving forward it puts pressure on the Fed to not increase rates.

Rates for Friday January 11, 2019: For the first time in six weeks rates have not declined, and prior to today’s CPI data we might have seen them bump up a little bit. Upward pressure on rates this week was caused by gains in stock markets as investors felt confident about the on-going trade talks with China. At this point the government shutdown is not have much, if any, impact on financial markets.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.125%      Flat

30 year high-balance conforming                    4.25%        Flat    

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

Since the end of the last football season my ring tone has been the Philadelphia Eagles fight song, “Fly Eagles Fly.” Starting in March of last year our youngest has asked me, “how long are you going to have that as your ring tone?”

“As long as they are the reigning champions.”

On Sunday I thought I would have to change my ringtone, thankfully the left-hand of the Eagles defensive tackle deflected the Bears’ kicker’s field goal attempt just enough to cause it to hit the upright and the cross bar so I retain the ringtone at least for one more week.

Not overly positive with this week’s game against Drew Brees and the Saints, but hopeful that next week at this time when you call I will still hear, “Fly Eagles fly, on the road to victory….”

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

1-4-19: What is 2019 looking like for Stratis Financial?

Question of the week:  What is 2019 looking like for Stratis Financial?


Answer:  Exciting! We spent the last quarter of 2018 adding some new lender partners to expand our portfolio of mortgage products well beyond our foundational products of conventional and jumbo 30-year fixed rate mortgages. Our new lenders bring alternative products that can benefit self-employed borrowers, borrowers with extremely high-net worth and borrowers looking to secure housing through retirement. With our growth in lending options we can cover pretty much any mortgage need for residential homeowners or home buyers in the state of California.


Personally, I am excited to add a new relationship referral source that will enable me to be assist more families with their mortgage needs as well as strengthen my connections with past clients and referral sources.


From you I am looking for inquiries for your mortgage needs and plenty of questions to answer for you in 2019, please ask and I will answer and help you with solutions and options!


Have a question? Ask me!


Job growth and economic growth seem to be going in different directions. In the last revision for 3rd quarter 2018 Gross Domestic Product output the rate of growth was 3.4%, down from the prior quarter’s growth of 4.2%, current forecasts for the 1st quarter of 2019 are economic growth in the U.S. economy growing less than 3%. The data shows economic growth is slowing. In a seeming anomaly, during this slowing growth period employers have not been slowing their hiring practices, as evidence by today’s report on December employment from the Department of Labor. Blowing away forecasts, employers added 312,000 new jobs in December, the consensus forecast of economists surveyed by MarketWatch was an addition of 182,000 jobs. Also included in the report were upward revisions to the job growth data for October and November. The most reported employment number is always the unemployment rate, in December it rose from 3.7% to 3.9%, not due to layoffs but due to more people entering the job market seeking work.


This is very positive data, but the most important data in the report was that average hourly earnings for workers increased 0.4% for the month and year over year the increase was 3.2% in wages, matching the post-recession high of earlier this year. With wages growing over 3% and inflation growing right around 2% workers have more residual income to either spend on goods and services or put into savings, or both.


Today’s data has created confusion amongst the “experts” as to the short and long-term future for rates and the economy. Will the increase in hiring and wages spur economic growth? Will it push back, or push off, an expected recession in late 2019 to early 2020 or not at all? Will the job markets create inflation that will cause the Fed to react with more rate increases? Or is the labor market surge, a final movement before international markets seep into domestic markets causing economic slowing to accelerate to the point that the economy shrinks into recession? The economic data the past several months has been inconsistent with the employment showing growing strength while growth has been losing strength.


What does it all mean for interest rates? The hundred-billion-dollar question, literally. Quick recap: good economic news means higher interest rates; bad economic news means lower interest rates. What we see from our economic data is a combination. Good news: more workers working earning more income allowing them to spend more and sustain economic growth. Bad, or less than good, news: Economic growth has been slowing, international markets are slowing and in turmoil due to the ongoing tensions due to tariffs and negotiations between major trade partners, home sales slowing down nationwide. Rates have been dropping consistently for six weeks and are well down from their seven-year high in October. Last month the Fed indicated instead of three rate hikes in 2019 it would probably initiate two rates hikes, and the common wisdom has become that the Fed may not raise rates at all in 2019. What it means for rates in the short-term is likely continued volatility in equity markets, i.e. stock markets, which typically results in investors putting their money in the “safe havens” of fixed rate assets, such as bonds and mortgages. More money invested in fixed rate assets leads to lower returns on those assets, in other words lower rates, or lack of rising rates.


Rates for Friday January 4, 2019: Interest rates and stock markets continue their intra- and inter-day surges and falls, with the trend being lower rates through the volatility. Should there be resolution to the tariff/trade disputes, an agreement to open the closed portions of the federal government and positive news for the 4th quarter GDP the turmoil will subside and rates will rebound higher. If the confusion continues and the GDP news shows continued decline in growth rates will stabilize at current or lower levels. Take advantage of the current rate market while you are able to do so. Rates are down again this Friday from last.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.125%      Down 0.125%

30 year high-balance conforming                     4.25%        Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


The Smith family is on its annual post-Christmas/pre-back-to-school trip to a desert, this year returning to our favorite p-C/p-b-t-s location of Scottsdale, Arizona where the temperatures have been very cool, the skies clear and the relaxing fantastic.


We return to our familial abode tomorrow and back to mostly normal schedules on Monday (exception being our college freshman who is wondering what to do for the two more weeks before she returns).


Looking forward to a wonderful 2019 and helping you, your family, friends, neighbors and co-workers with your mortgage needs!


Have a great week,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog