


Are mortgage rates going to go up?
Question of the week: Are mortgage rates going to go up?
Answer: I shook my Magic 8-Ball and its answer matched my own, signs point to yes.
Mortgage rates operate independently of the Federal Reserve. That said, investors who determine mortgage rates take their cues from the Fed. That said…the primary cues investors take are essentially the same cues the Fed uses when deciding whether to raise, lower, or keep the same their benchmark interest rate.
The cues come from economic data provided by different federal agencies and departments. Jobs, consumer spending, prices, imports and exports, manufacturing output, are all insights into how our national economy is doing. The basic rule of thumb is the better the economy is doing the more likely rates will go up, the worse the economy is doing the more likely rates will go down.
As you are aware, rates jumped considerably in 2022 following inflation spiking in 2021 and continuing to increase. Rates went from below 3% in January 2022 to 7% in October. Using the conforming rate every Friday that is used for the WR&MU to track rates, since the conforming rate passe 6% in September 2022, the rate has been below 6% only ten times since. That is ten times in one hundred twenty-five weeks, the last time in early October 2024.
Since October the economic data has shown the economy is strong, growing at a good pace, growing employment and wages, and inflation stubbornly sticky. The inflation target for the Fed is 2%, since inflation spiked in 2021 when the CPI rose from 2.6% to 4.2% from March to April, the closest the index has come to 2% was in September 2024 at 2.4%.
This week Bureau of Labor Statistics released the Consumer Price Index for January. Expectations on Wall Street were prices to increase 0.3% from December to January. When the report showed a 0.5% increase for the month, the largest increase since August 2023, it was met with great surprise. Year over year, prices increased 3% from last January, the highest level since June 2024.
After two rate cuts last year, the expectation was for the Federal Reserve to cut its benchmark rate two, possible three, times in 2025. Data in January and last week pretty much assured that the Fed would not undergo a rate cut at it meeting in March.
This week’s inflation data has many investors expecting no Fed rate cut this year.
Going into that expectation is not just inflation data. Approximately 11% of our consumer goods are imported. Over $40 billion of appliances were imported in 2025. President Trump is following through on his campaign speeches and increasing tariffs on imported goods. This past week he imposed a 25% tariff on imported steel and 15% on aluminum.
Increasing tariffs on all of our trading partners, and on raw materials and finished goods, will lead to higher prices for manufacturers and consumers.
Consumer spending is 65-70% of our economy. Driving consumer spending is employment and wages. If wages and employment lag behind inflation, spending slows and so does our economy. If wages and employment are ahead of inflation, spending increases and so does our economy. Employers have expanded payrolls and are paying workers more money. This increases their expenses, which leads to price increases, and leads to more money in wallets and pocketbooks of consumers to spend.
Looking at the political and economic trends, there is very little support for rates to go lower. As well, very little for rates to stagnate into the future.
Signs point to yes. Yes, rates should be going up this year. Absent some major event that will slow the economy, there is little information available that leads to rates not climbing in the near or medium term.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Two big factors in the jump in CPI are it is January and chickens. January is when a lot of retailers, service providers, hospitality vendors, raise their prices. This past year a lot of goods and service providers held prices firm against higher costs they pay for labor and supplies, and with the turn of the calendar page increase their prices to offset their own higher costs. This leads to a bump in CPI, as seen by most of the gains in the index were from goods and services that have seen slower increases in their prices over the past year.
Accounting for two-thirds of the increase in grocery prices in January was the 15% increase in egg prices since December, the highest one month increase since 2015. This led to many restaurants adding an additional cost to prices on their menus for egg dishes.
Some good news for rates came today with the data for retail sales in January, which dropped 0.9%, the largest month-to-month decline in almost two years. Large holiday shopping in December, a severe cold snap in much of nation, wildfires in California, all contributed to shoppers staying home in January. A major reason for the big slowdown was a fall off in sales of cars and trucks—taking that sector out of the data and retail sales fell 0.4%. Rising in sales for the month were gasoline and restaurant sales, both up 1% for the month. Slower sales can lead to slowing economy can lead to lower rates.
Rates for Friday February 14, 2024: Despite the reaction to the inflation data, rates are flat from last Friday, thanks to a rebound with today’s retail sales data, as well traders moving into bonds for the long Presidents Day weekend.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.625% Flat
30-year high-balance conforming 6.75% Flat
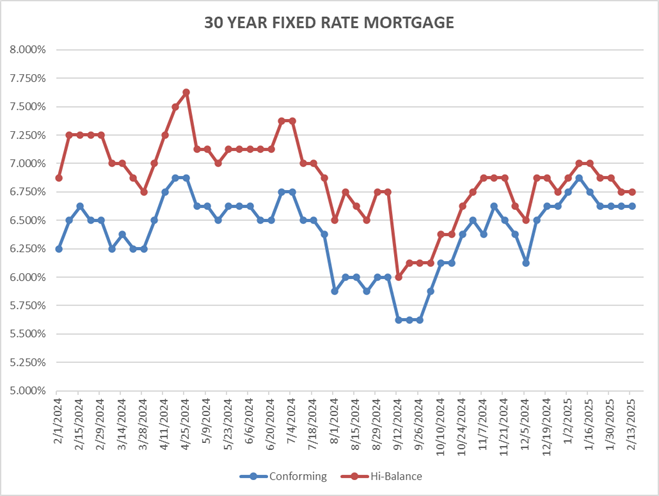
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
One of the biggest joys in life is going through it with your Valentine, I know this is true for me and hope it is for you as well.


