

What should we look at for year-end tax planning?
Question of the week: What should we look at for year-end tax planning?
Answer: Tax preparers for clients in Los Angeles County are sleeping in for a few days after the October 15th filing deadline, that traditionally has been used for clients with complicated tax filings after filing extensions for their April 15th tax return submissions. This year the state and federal governments granted automatic extensions to filers in Los Angeles County due to the fires in the Palisades and Alta Dena at the start of the year. Human nature for most of us enables us to put off until October what could be done in April if there is no penalty for doing so.
Hence, a flood of filings for the tax preppers the past few weeks.
Looking forward, how can your 2025 tax filing be made easier?
Looking at a real estate and mortgage perspective, there are a few easy steps you can take.
If you have purchased, or refinanced, any property, make sure you have a copy of the final closing statement from escrow, or title. This will show pre-paid items that may be deductible, such as pro-rated interest and property taxes; as well as any origination costs you may have paid for th e mortgage.
If you sold any property, make sure you have the final closing statement as it will also show prorated taxes and interest. As well, it will show the total closing costs you paid for the sale, which may be a factor in whether you have to pay capital gains on the sale of the property.
Regarding property taxes, have verification of the amount of taxes you actually pay in 2025, not just the tax bill from the county. Because our taxes are due in November (later in December) and February (late in June) most property owners pay for one tax year in February, and the next tax year in November. Because of this the taxes paid are not the same as the second payment in the year is for the next fiscal year. Depending on how you bank and your organization, you may need to dig out the payment you made in the beginning of 2025 for the second half taxes for the tax bill you received in 2024.
If you sold and bought, or refinanced, you paid mortgage interest to more than one lender. Make sure you have the last statement from the prior lender as it will have the total amount of interest you paid for the year, until the loan was paid off. Some lenders are less than excellent at getting IRS form 1098 (mortgage interest paid) to past borrowers, this ensures you have some record of the interest paid.
If you moved make sure your prior lender has your new address to send your IRS form 1098.
If you have a HELOC that was used for home improvements, or business purposes, collect evidence of the funds being used for such purposes.
Speaking of improvements, collect the receipts for labor, material, permits, etc and record the totals somewhere. If the improvements were made on investment property the costs may be deductible for the year made. If made on your primary residence, having evidence of the costs may come in handy in future years to off-set capital gains.
If you have inherited property, or obtained property in a divorce, make sure you have a reasonable estimate of value at the time of the transfer to be used as a cost-basis for the acquisition of the property. This need not be a formal appraisal, an estimate without detailed analysis may be made by an appraiser, or a local real estate agent with knowledge of the area may prepare a Comparative Market Analysis (CMA) estimating the value.
As always, consult with your tax preparer for any additional information s/he may need to ensure a smooth process in tax prep and filing.
Have a question? Ask me!
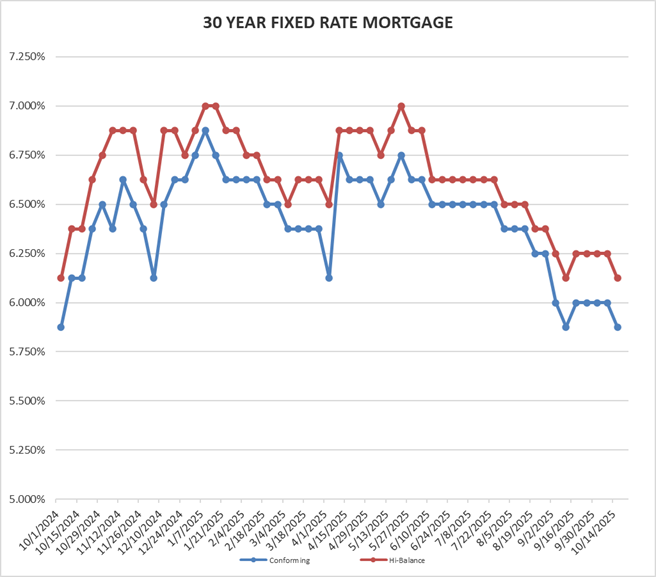
Rates for Friday October 17, 2025: With no economic data being released due to the government shutdown, investors are reacting to other news—such as the spat between China and the United States (and many other nations) on rare earth minerals. The reaction is downward pressure on rates, which have dropped from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 5.875% Down 0.125%
30 year high-balance conforming 6.125% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
This is being composed and sent from Frederick, Maryland as I enter the final days of my East Coast Road trip.
It has been a great trip, seeing my daughter who lives in Brooklyn, uncle, aunt and cousins in New York City, cousin and high school friend in Connecticut, elementary and junior high school friend outside Philadelphia (his dad had Eagles season tickets!).
Trips to visit Valley Forge, Gettysburg, Harper’s Ferry, Monocacy Battlefield (Maryland). Today I head to Baltimore for the weekend for a long visit with our oldest daughter who moved there from Boston in August.
The fall colors are out creating beautiful drives through the hills and farmlands of the region.
The only downside has been the absence of my co-pilot who stayed home with the dog and encouraged me to take the trip to scratch my itch for a drive around.


