

What are some changes in the industry for 2025?
Question of the week: What are some changes in the industry for 2025?
Answer: Perhaps the most significant change is an annual event, the change in the maximum loan limits for conventional and FHA mortgages. The Federal Housing Finance Authority (FHFA) sets the maximum conforming (Fannie Mae and Freddie Mac loan limits based on the House Price Index which tracks the average increase in home values nationally. Adjusted for incomes and inflation, the HPI usually increases from year to year, but there have been some years in the past when it declined, and as a result so do the maximum loan limits. While Fannie and Freddie are under the direction of the FAHA, FHA is under the Department of Housing and Urban development but uses the FHFA limits.
In the past, pre-2008 Great Recession and housing market melt-down, FHA set their own loan limits—generally lower than the conforming limits. Besides the conforming loan limit, FHFA also sets the ”high-balance” limit for homes in high-cost areas; originally for Alaska and Hawaii, the high-balance limit also applies to high-cost counties such as Los Angeles and Orange. Prior to the Great Recession and restructuring of home financing with the Dodd-Frank Act, there was no separate high-balance limits for counties and loans above the conforming limit had to use “jumbo” or non-traditional mortgage products.
For 2025 the loan limits have increased a bit over 5.2% to $806.500 for conforming and $1,209,750 for high-cost areas (high-balance loan limit is 150% of the conforming loan limit).
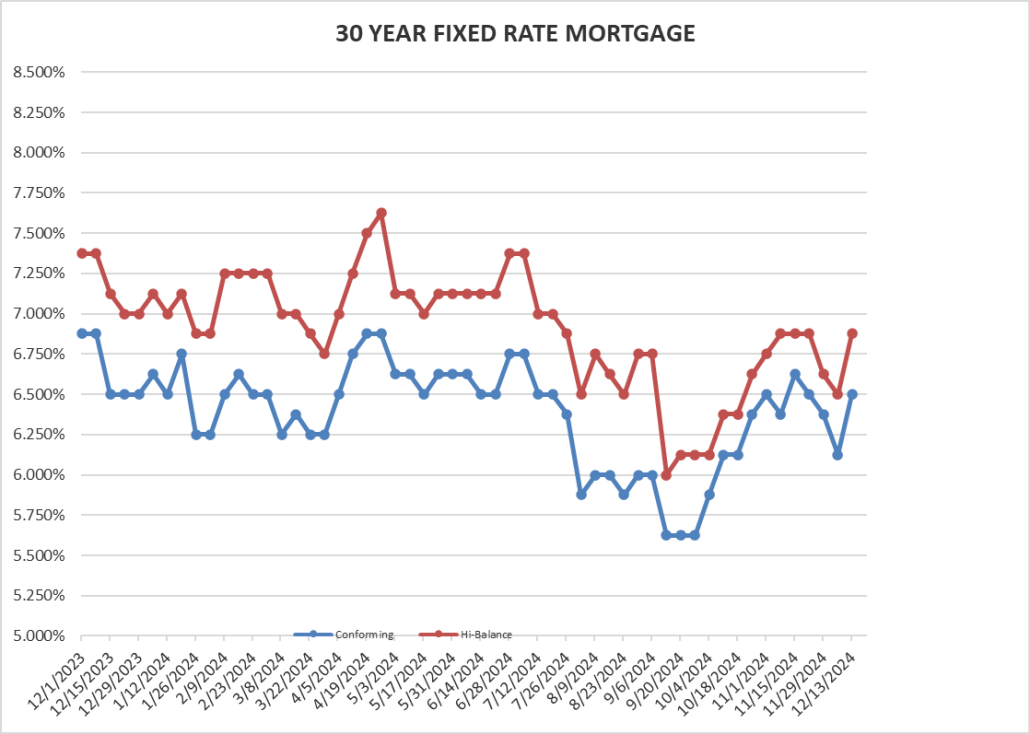
Today to qualify for a $806,500 loan with a payment of $5098 you will need income of approximately $14,500 per month with a rate of 6.5%; last year for the same loan amount, because it was “high-balance” limit, the rate was 7.125%, the payment $5434 and qualifying income of approximately $15,525, about 7% more than needed this year due to higher loan limit. Note the rate is based upon parameters below, 20% down and 740 FICO score, a higher credit score, or lower loan-to-value will result in a lower rate and payment.
Insurance is changing for 2025. After seeing major changes in home coverage policies, from none available to higher premiums, 2025 should show more friendly changes. Farmers Insurance recently announced they see the state’s insurance market improving and as a result is increasing the number of homeowners insurance policies they will issue in the state and expand coverage to condos and other types of housing.
This is good news as chances are other insurers should follow Farmers, thus expanding more affordable insurance options for homebuyers. That said, State Farm is still the biggest insurer in the state and no news has come from them regarding their plans for 2025.
For the “non-admitted” insurance market (from insurers no licensed by the state but allowed to write policies to cover risks admitted carriers will not cover) more competition has entered the market which has softened some premium options for those forced into this higher-priced market.
Condo sales as a whole will continue to be challenging in 2025, mainly due to insurance coverage. Fannie Mae, Freddie Mac and FHA have been reducing the number of approved condominium homeowners’ associations where they will lend, primarily because of what they determine to be inadequate insurance coverage. Due to the significantly higher costs to replace and rebuild damaged properties, many HOAs insurance policies have not kept up with the higher costs. As a result, they have been dropped off eligible condo lists due to the risk posed to lenders, and ultimately Fannie, Freddie and FHA, should there be a major event and property loss.
For condo sellers, and listing agents, it is highly recommended before putting units on the market to determine if the complex is on or off eligibility lists for lenders. If they are off the list determine why and if the reason is correctable; is it a need to re-apply with updated information, or are there other factors that may require significant action by the HOA to regain eligibility.
For condo buyers it is highly advisable when you make your offer to have your lender check to see if the unit is eligible for the type of financing you are using. If not, determine why and is it something that can be corrected during escrow—such as updating HOA information for the lender.
Finally, 2025 will be the first full year with the new broker compensation regulations that went into effect earlier in 2024. Will sellers be willing to include compensation for the buyer’s agent in their sales price? Will buyer(s) need to compensate their agent out of their own pocket? Will more, or fewer, agents be willing to sign one-time-show contracts with buyers? Will more or fewer homebuyers, and sellers, contract for reduced services from agents to assist with transactions?
The market is still sorting many of these issues out, and with continued slow sales there has not been a significant number of transactions to establish market “norms” between agents and clients it may take a while for there to be an established set, or sets, of what is expected in terms of service, compensation, and who pays who what.
With rates continuing to be at, or above 5.5% for most of 2025 we should see a slow down in the increase in home prices for the year—note “slow down in the increase” not “decline.”
Schedule an appointment to discuss your options if you are considering purchasing a new home or property or refinancing an existing one and want to know the mortgage options available to you.
Have a question? Ask me!
A bit hotter than expected. That sums up inflation data this week. November’s Consumer Price Index increased at the highest rate in seven months, up 0.3%. While what was expected from Wall Street forecasters, that it was the highest since the Spring brought some concern. Year over year inflation increased from 2.6% in October to 2.7% in November. For the fourth month in a row the “core” (volatile food and energy costs stripped from index) rose 0.3%, with the core rate unchanged at 3.3%. A big part of the increase was vehicle prices, likely due to increased demand from those needing to replace cars and trucks that were lost during October’s hurricanes. One positive note for November is that housing price increases cooled off for the month. Not as good was a 0.4% jump in medical costs for the second month in a row.
Pundits opined (pundited?) that expectations for the Fed should not change based on the inflation data—it will lower its benchmark rate next week. However, the markets did not seem in sync with the pundits. Fixed rates markets dropped throughout the week (lower prices mean higher rates) with no news other than inflation data that should be market moving. One reason could be that while the expectation is that the Fed will lower rates next week, rate cuts in 2025 are less certain. Will the Fed stick to a plan of two to three cuts? Or will there be a long pause to see how inflation and job markets moving.
Rates for Friday December 13, 2024: Rates have their biggest week-to-week increase since last October when they hit their highs for the current cycle (7.875%). Up 0.375% for the week, rates are at their highest since July. Long-term rates have been drifting down, and this could be a short-term spike, but as we close out the year volatility is my expectation.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Up 0.375%
30-year high-balance conforming 6.875% Up 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
When is too soon? When is it too soon, and when have you waited too long to get a Christmas tree? Go too soon and it starts to dry out before New Year’s. Wait too long and your choice of trees has been reduced dramatically and you risk your choices being somewhat Charlie Brownish.
This is the internal debate as to get a tree over the weekend, or wait until sometime next week.
Have a great week,
Dennis


