

What are the tax advantage of home ownership*?
Question of the week: What are the tax advantage of home ownership*?
Answer: *I am not a tax professional, please contact your tax preparer to determine what deductions you can or cannot claim.
With the tax filing deadline approaching, the question of the week may have you looking through your records to see if you have additional savings available for your 2025 tax returns.
The tax advantages of home ownership in high-cost/tax states are not as beneficial as they were before the Tax Cut and Jobs Act (TCJA) of 2017 was passed; that said, there are still benefits for home owners.
Here is a rundown of some of the deductions available to those who will have more itemized deductions (those shown below) than the standard deduction (for 2025, $15,750 for individual filers and $31,500 for married filing jointly):
Mortgage interest:
Federal: can deduct the interest up to $750,000 of acquisition debt. If you have $800,000 loan with a rate of 5% and paid $40,000 in interest in 2025, on your federal return you can deduct $750,000 x 5% = $37,500
California: interest on up to $1 million of acquisition debt; you can deduct the full $40,000 you paid in interest in 2025
HELOC: provided the Home Equity Line of Credit is used to buy, build, or substantially improve the home, the interest is deductible depending on the loan amounts. The $750,000 cap on mortgage interest deduction (or $1,000,000 for California) is total of all loans on property used to buy, build or improve the property. For federal filing, if your primary loan is $700,000 and you have a balance on our HELOC of $75,000, there is interest on $25,000 of principal that cannot be deducted. This is where your tax professional can help calculating a pro-rata amount of interest on both loans to use to take partial advantage of the higher rate on the HELOC.
Property tax:
Federal: a major negotiating point in the TCJA was the SALT deduction, State And Local Taxes. Prior to the TCJA all state and local income taxes, and all property taxes were deductible. The TCJA limited the total of these deductions to $10,000. A California couple who pay $8500 in state income taxes and have property taxes of $7,500 per year, for a total of $16,000 in SALT paid, can only deduct $10,000.
California: the full amount of income and property taxes are deductible; the $6,000 “lost” on the federal return is included for a $16,000 deduction.
Medical home improvements: ramps, wider doorways, walk-in showers, elevator*…
Federal and state guidelines are the same for these improvements as medical expenses. If the cost of the improvements exceeds the value they add to the home, and your total medical expenses exceed 7.5% of your income.
You are ADA-proofing your home so you can prolong how long you can live in it for your Golden Years. You spend $50,000 on the improvements and the local realtor indicates your value has increased by about $30,000. You have another $25,000 in other medical expenses, and your income is $200,000. The cost of improvements above increased home value is $20,000, that puts your total medical costs at $45,000, well above 7.5% of your income.
*Must be medically necessary for you, spouse or dependent; a note from doctor indicating the necessity would be very helpful.
Points paid on mortgage: Points paid for purchase or refinance mortgages are deductible on federal and state tax filings.
Home Office (self-employed):
State and federal guidelines also follow suit on deduction space for home office “used exclusively for business.”
If your deductions based on homeownership total more than the standard amount given by the taxing authorities, you should consider itemizing deductions, which may include additional deductions from other payments, costs, or fees you have paid.
Again, I advise you consult with a tax expert before assuming any of the above deductions are 100% accurate, or even 10%…
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Consumer prices increased as expected in February, 0.3%, slightly more than January’s 0.2% increase. Year over year, the Consumer Price Index was up 2.4%, matching the annual increase in January. Core prices (gas and food removed from the calculation) matched January’s 2.5% increase for the year, and were down slightly, 0.2% compared to 0.3%, from the month before. The index is expected to rise significantly this month due to the spike in oil prices due to the Iran conflict and the choke-point in the Gulf of Hormuz.
What to do? This morning economic data supported a Fed rate cut, a Fed rate increase, and the Fed leaving its benchmark rate alone. Supporting a rate cut was the first revision to 2025’s 4th quarter GDP cutting economic growth from 1.4% to 0.7%. Less than one-percent growth is just below anemic, and trending towards negative growth.
Supporting a rate increase was inflation data that has rate hawks want to focus on for determining rates; the Personal Consumption Expenditures index remains very sticky. The numbers are for January (delayed two weeks due to catching up after government shutdown), and show prices increased 0.3% in January from December, and 2.8% year-over-year; down from December’s 2.9% rate, but higher than desired by the Fed. Stripping out energy and food, the core rate year-over-year rose 3.1%.
Supporting no action, personal income rose slightly more than inflation, up 0.4% for the month, with personal spending increasing the same as wages; consumers are not dipping, or dipping less, into savings to keep up with their expenditures.
Uncertainty is causing some turmoil in the markets, today’s data is not helping as none of the data has been impacted by the Iran conflict and the jump in oil prices to over $100 per barrel, the highest since 2022 when Russia invaded Ukraine. Expectations are overwhelming that inflation for March will go up, how much and for how long? That is the primary question for Fed watchers. And consumers.
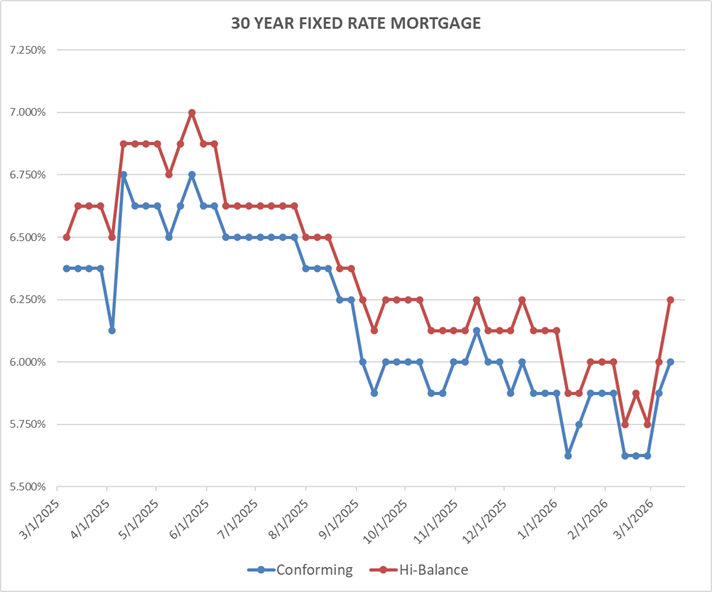
Rates for Friday March 13, 2026: Rates continue to rise this Friday to their highest so far in 2026, and highest since the end of November.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.00% Up 0.125%
30-year high-balance conforming 6.25% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The Oscar’s are Sunday, which I am less interested in that I was many years ago. Primarily because it was fairly easy to see the five movies nominated for best picture. With the increase in the number of nominees to ten I feel it watered down the category and I lost interest in wanting to see the nominees.
That said, I have seen four of the nominees, Marty Supreme, Hamnet, Frankenstein, F1—which is the order I enjoyed them from most to least, though they were all somewhat good.
Based on those movies, my best actress would be the wife in Hamnet and the Marty in Marty Supreme (I’m not great at knowing actors’ and actresses’ names).
If you are a fan of the Oscars, I hope you enjoy the show.


