

Does it make sense to refinance to consolidate other debts?
Question of the week: Does it make sense to refinance to consolidate other debts?
Answer: As with many mortgage questions, the answer depends on the math.
During the pandemic many families ran up debt on credit cards, auto loans, Home Equity Lines of Credit (HELOC), as they improved their homes to adapt to study and work at home, or just to upgrade kitchens, baths and exteriors. Following the rescission of stay-at-home regulations and the opening up of travel across the country and around the globe, many families incurred more credit card debt to release their pent-up travel bugs.
Now looking at very high balances on their credit statements, and the corresponding payments, with perhaps minimal increases in income compared to inflation and the new monthly obligations, the question arises, “should we consolidate our debt?”
Before we look at the math on a hypothetical example, let’s look at some of the factors to be considered as you weigh the decision as to whether it makes sense to refinance to consolidate your debt.
First and foremost, the concern about increasing the interest rate on your mortgage. Most homeowners refinanced during the historically low rates we experienced in the past few years to a very low rate, and greatly reduced monthly mortgage payment. With rates having spiked since the beginning of the year, does it make sense to refinance and pay a much higher mortgage rate?
Another factor is utilizing a HELOC to consolidate the debt, or you already have a HELOC to which you have transferred a lot of consumer debt. Is that a better option?
Against these factors are what are the rates on the debt you are paying off, how long will it take you to pay off the debt and experience those rates, and very importantly what are the monthly payments and how are they impacting your household cash-flow against rising prices and costs for daily life?
The math.
The assumptions we will use are that you have a $500,000 mortgage with 30-year fixed rate loan with an interest rate of 2.75% from refinancing last summer. Your monthly mortgage payment is around $2500 per month.
You obtained a HELOC for home improvements at the start of the pandemic and have a balance of $85,000. The rate on the HELOC is the prime rate plus 0.50%, today your rate is 6.00%. Your minimum payment this month is interest only, $425 per month.
From travel, major appliance purchases, clothes for growing kids, and more nights out for dinner, your credit card balances are $55,000, with a minimum payment of $1100 per month. Because you have excellent credit the average rate on the cards is 15%.
Your minimum payments on mortgage, HELOC, and credit cards total $4025 per month.
Now consider that your HELOC rate will increase by 0.75% (to 6.75%) later this month after the Federal Reserve increases its benchmark interest rate, and likely another 0.75% later this year, and up to 2% more into 2023. The immediate increases your minimum payment another $50.
With the increase in the prime rate, the rates on your credit cards will very likely increase as well.
Ignoring the future for the moment, let’s see the math on a mortgage of $640,000 to consolidate your debt. Assuming your property value has increased to $900,000 so your loan-to-value is 71%.
The refinance transaction is considered “cashout,” which has a higher rate than if the transaction were a purchase or “rate and term” refinance (no cash out, just lowering rate and payment). The rate today for a cashout refinance is 6.25%* with no points, or 3.5% higher than your current rate. If you wish to pay one-point ($6400), the rate would be 5.875%*.
The payment for $640,000 30-year fixed rate mortgage with a rate of 6.25% is $3940 per month, for 5.875% $3825. Essentially the same payment as your total payments today. So, does this make sense?
Reasons it may make sense for some families.
Primarily, the payments calculated for the debt being paid off are for minimum payments; interest only on the equity line, and 2% of the balances on the credit cards. This means your HELOC balance is staying the same, and your credit card balances, assuming you are not charging more, decline by about $400 per month.
Without an increase in income, or a windfall from a bonus, sale of an asset, inheritance, or other source, how will you pay down/off these balances? Does it bother you that you will have these debts for a prolonged period of time with the balances declining slightly during that time?
The counter-argument to the time frame issue is that you are obtaining a 30-year mortgage should you keep your home for that long. Surely you will be able to pay off the debts within that time frame.
To pay the debts off within a certain time frame, 2-, 5-, 10-years, how much will you need to pay per month and how does that affect your household cash-flow? With a current blended rate of about 10% for your credit card and HELOC accounts, to pay off the balances in 10-years (assuming no change in rate or adding to balances) the payment is $1850 per month. To pay off in 5-years the payment is almost $3000 per month.
In determining if consolidating your debt into a new mortgage is right for you, do the math on your own particular situation. Consider the overall cash-flow of your home today with your current debts. Is there an ability to pay off the debts in a relatively short time frame vis-à-vis a new 30-year mortgage?
Looking forward, will rates come down in the future? If so, can you benefit from refinancing again to lower your rate and payment? How long are you planning on owning the home? If a short time you can use equity from the sale to pay off the debt, how sure are you of this time frame.
I see and hear marketing messages from some lenders quoting adjustable-rate-mortgages for consolidating debt for a lower rate and payment. But for how long? The thing about ARMS is the rates aren’t fixed—isn’t that part of the uncertainty with your current credit obligations?
Current and future income, ability to make large payments to pay off current outstanding debt, current rates and payments on mortgage and debt you are paying off, and most importantly your comfort level with your current debt situation versus consolidation and fixing the monthly payments removing uncertainty. These are the factors we will discuss if you call to go through your current situation and options to obtain debt relief.
*Rates are based on credit score of 740, balance of new mortgage being $647,200 or lower, and a loan-to-value between 75-79.99% for a detached single family residence. Rates and terms vary daily and based on other factors, as well as those above.
Have a question? Ask me!
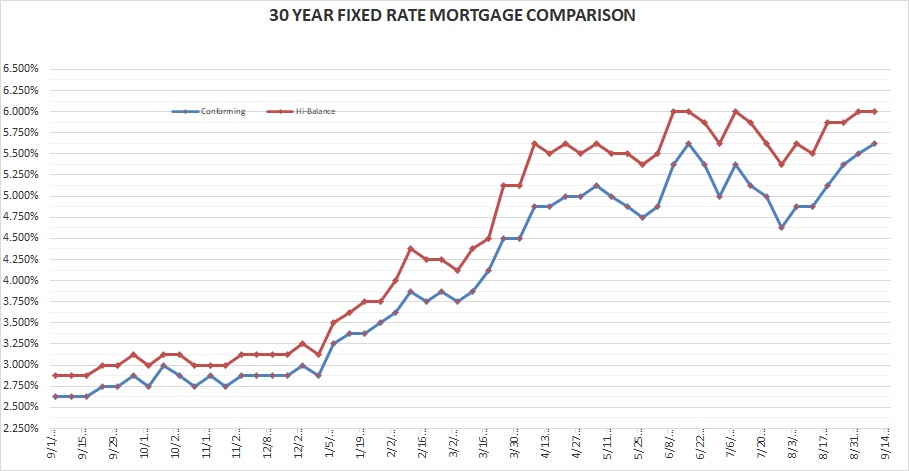
Rates for Friday September 9, 2022: No economic data this week that impacted rates. Federal Reserve Governors, and Chair Powell, were giving speeches and interviews, all of which said, without actual saying, that the Fed would raise its benchmark rate by 0.75% during its September 20-21 meeting. A bump in the conforming rate to match the most recent high from June.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 5.625% Up 0.125%
30-year high-balance conforming 6.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
We had a great trip to New York City. An interesting aspect was the U.S. Open tennis championship going on while we were there. Arriving Wednesday evening, the bars and restaurants that evening and again on Friday all had Serena Williams’ matches on. Everyone, it seemed, was talking about Serena. As well they should.
Perhaps one of the top five athletes of my lifetime, Serena’s accomplishments in an era where more and more women entered professional tennis with better training, coaching, and conditions that greatly increased the competition and reduced the margin of ability between the top and middle players, are truly historic. I am glad her final matches were at the U.S. Open and that even non-tennis fans were made aware of how incredibly unique she is with a career that may not ever be matched.
Heat breaks this weekend? Coming home to a house with no air conditioning did not bring a lot of joy, but every degree lower we can get will make the Smith’s, and Sammy our dog, very happy!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


