

Should we write a backup offer?
Question of the week: Should we write a backup offer?
Answer: Yes, especially in this market.
With inventory scarce, multiple offers on properties, and most importantly, a market that has seen an above normal escrow fallout rate.
The last phrase is a primary reason you should write a backup offer on a home you would like to purchase, but your offer was not accepted in favor of another one.
What is a backup offer? It is pretty self-explanatory, after a seller has entered escrow with another buyer, you present an offer to the seller indicating the price and terms you will purchase the home if the current buyer they are in escrow with cancels the sale.
There are many reasons why a buyer may cancel a sales contract, among them:
- Buyer does not qualify for their mortgage, either because rates have increase, insurance premium is too high, lender did not do a proper job pre-qualifying the client, or a multitude of other reasons
- Are not able to get an insurance policy, or the premium is too high for them
- The physical inspection presented issues with the structure and property they were unwilling to take on if they close the purchase
- Appraisal value is less than sales value and negotiation to amend sales price with seller fails
- Funds for the purchase are no longer available
- Buyer’s purchase contingent on sale of their home fell out of escrow, buyer no longer has funds nor qualifies for purchase
- Buyer changed their mind for whatever reason and used one of the contingencies in the contract to cancel
The advantage of the backup offer to a seller is that if their current escrow does fallout, they do not have to go back to the market, but can pivot and move forward with the backup buyer.
Writing a backup offer does not cost you any additional money, though some sellers will request a deposit that is refunded if your backup offer is not activated and you become the buyer of the home. This enables you to look at other homes, and if you find one you like negotiate to purchase the home. If you have an accepted offer on another home, you cancel the backup offer.
This is important to note, if you have a backup offer accepted it does not preclude you from purchasing another home.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Rates roller-coastered while we were on our vacation in Italy, and currently climbing again. A lot has happened in the last three weeks:
- The jobs report for September showed a gain of 336,000 jobs, almost double expectations, not good for rates
- Retail sales in September were up 0.8%, significantly higher than expectations. The news was rate unfriendly as it shows consumers are shrugging off inflation and still buying goods and services
- The Fed sent some mixed signals, on the one hand implying that more strong economic news will put the Fed back into rate-increasing mode; on the other hand, saying the bond markets (10-year Treasury at/near 5%) are putting a damper on inflation and will pause on any rate hikes
By far the biggest impact on markets is the Israeli-Hamas war. Wars create a “flight to safety” for investors, fleeing stocks for the safety of fixed returns found in bonds. That the war is in the Middle East, and could impact oil and gas production and distribution, and therefore push energy costs higher, can damage the world economy with even higher prices.
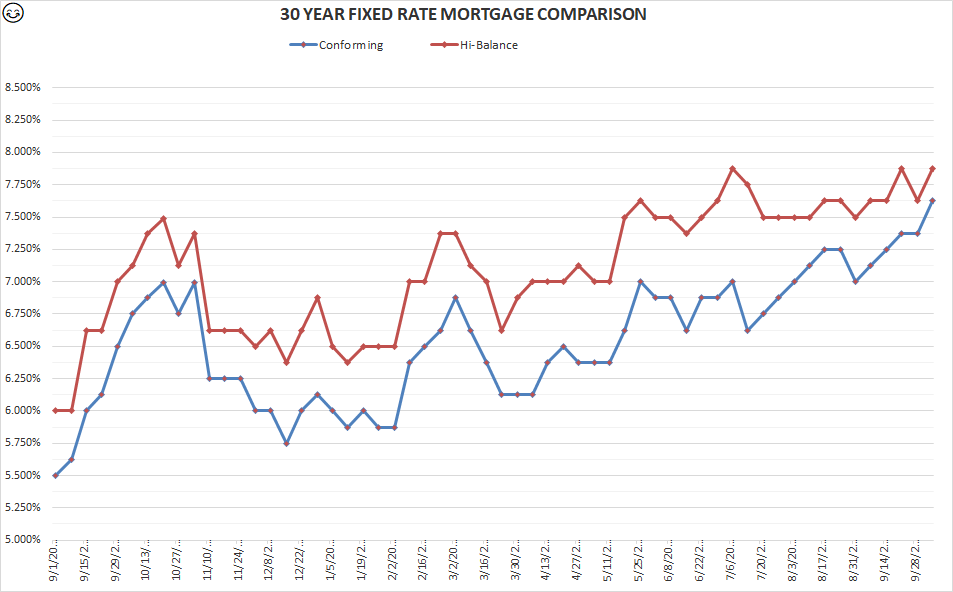
Rates for Friday October 20, 2023: Rates spike this week from last, pushing them to their highest levels of the century—not since 2000 have we seen rates this high. The markets are like a turbulent sea, rising and falling as winds and tides shift. Normally this would create downward pressure on rates, but with consumers, who are approximately 65-70% of our economy, still buying goods and services, and employers hiring more workers, both expanding economic growth, investors are more pushing rates higher.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 7.875% Up 0.375%
30-year high-balance conforming 8.125% Up 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
After taking the most time we have ever taken from home and work, Leslie and I have returned, adjusted to jet-lag, and missing our time in Italy.
We had a wonderful time on our trip, sharing it with our good friends Shannon and Greg. Our trip was five nights in Rome, four nights in Florence (staying at Airbnb’s in both cities), two nights in Santa Margherita Ligure, and for Leslie and I two nights in Milan with our travel buddies headed to Switzerland before returning home.
Besides the amazing historical treasures we saw, the standout surprise for me was how inexpensive it was to eat. We ate at some very good, make that excellent, restaurants and our bills were considerably less than similar meals would be in Southern California—at times half or more less.
I come back inspired for new experiments in the kitchen to try to re-create some of the fabulous dishes and flavors we enjoyed.
If you are planning a trip to Italy and want some tips and ideas please do not hesitate to contact me.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


