If we move out of state should we retain our current home?
Question of the week: If me move out of state, should we keep our current home?
Answer: Maybe.
We have written around this subject before, most recently in June 2023. Over the past several years we have had a lot of clients who have moved out of California for a variety of reasons, primary economic.
One common refrain we have all heard from those who have moved out of state is, “we got so much more home for a lot less than we sold our home for…”
This is not surprising as the median home price in California is almost $900,000, second highest in the nation (behind Hawaii) and some of the most popular states for relocation from the state have median prices of $307,000 (Texas), $406,000 (Tennessee), $433,000 (Florida), and $445,000 (Arizona).
Factor in income tax rates and cost of living, and economically and the result is close to 1.5 million people relocating from California to other states from 2020 through 2024.
Many relocators are homeowners. While many adjust to their new environments, more than quite a few return to California for various reasons from culture to weather to missing family and friends.
Reverse migration shock is a real thing. You sell your home in Long Beach in July 2022 for $800,000, netting $400,000 after your mortgage with a $1600 payment is paid off, and purchase a home in Boise for $560,000. After three years, you miss the “bigness” of Southern California, the milder weather, and your mother in-law and want to move back to Long Beach.
Can you?
Your home in Boise is valued at $580,000, but because you purchased with mostly cash you will net approximately $350,000 from the sale.
A home in your old neighborhood is selling for $1,000,000. With the $350,000 down payment your mortgage of $650,000 will have a payment of $4000.
When you sold your prior home in Long Beach your property taxes, due to Proposition 13 were $4500 per year; taxes on the new home will be close to $13,000 per year.
Can you afford to purchase the home you sold three years ago? Depending on other debt and circumstances, you will likely need close to $180,000 a year in income to qualify.
What if you kept your prior home in Long Beach and rented it?
You likely would have had less money for a down payment on your new home in Boise, therefor a higher monthly payment. Because the rental income on your Long Beach home would very likely be much higher than your mortgage and property taxes, the additional net income would likely cover the difference in your mortgage payment in Boise if you put a large down payment into the home from the sale of your Long Beach property and the higher payment due to the lower down payment.
Moving back, you would retain your current mortgage payment and your property tax basis, though your annual payment would be somewhat higher.
If you sold your home in Long Beach and then move back you will pay approximately $67,000 per year for your mortgage and property taxes.
If you had retained your Long Beach home, you move back in with an annual cost for your mortgage and property taxes of $25,000. A savings of $42,000 per year.
Note The California State Franchise Tax Board is very aggressive pursuing income earners who leave the state for taxes—especially if you move and retain what was your primary residence. If you do this keep very clear records of utility payments, bank accounts, bills, ensure you file a Schedule E for the rental of your California home, and most importantly keep your tax preparer informed on everything.
Speaking of tax preparers, capital gains regulations state that if you live in a home in two of the prior five years and sell the property you can claim the $500,000 exemption for married couples ($250,000 for single filers) against capital gains.
If you really like Boise and wish to stay, you have a just under a three year window to sell your Long Beach property and receive the capital gains exclusion. You lived in the property from 2007 when you purchase the home until July 2022 when you moved to Idaho and established a new primary residence. If you sell the property before July 2025, you will receive the capital gains exclusion. If you sell after that the exemption is gone and your capital gains taxes are considerably higher.
If you want to do the math on relocating to another state please give me a call to run the numbers and what-ifs for you to do so.
Have a question? Ask me!
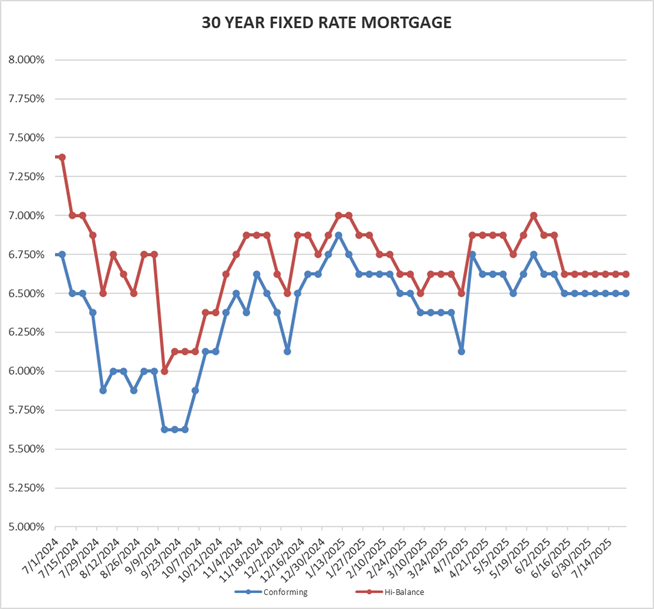
Rates for Friday July 25, 2025: Not a lot of major economic news impacting rates this week. The biggest market news was political as the Trump Administration confirmed 15% tariffs on Japanese imports, and scuttlebutt has the same rate may also apply to European and other trading partners. Rates maintain a very steady course week to week.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 6.50% Flat
30 year high-balance conforming 6.625% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I realize that at times (often?) my writing on economics, markets, what impacts what and why, can get a bit confusing. Frank and Ernest provided clarity on between the economy and interest rates in today’s funny papers.