

What is the deal with the “we’ll pay cash for your home” ads?
Question of the week: What is the deal with the “we’ll pay cash for your home” ads?
Answer: Last week we answered the question, “should we sell our home ourselves” for homeowners thinking of saving money by not using a real estate agent to list their property. This week, we look at the “pay cash for your home” companies.
For some homeowners, taking an all-cash offer immediately instead of putting your home on the market may make sense. There is no marketing time, not costs, and no working your schedule around potential buyers wanting to see your home and open houses.
The most important aspect of the cash-for-your-home transactions is that you will not receive market value for your home. It varies depending on location, condition, and the company you are working with, but likely the offer will be 65% or lower of the market value of your home.
Typically, the we-pay-cash companies are interested in distressed properties, those that need significant work to put them in prime market condition. Some are focused on homeowners who are behind in their mortgages and facing foreclosure.
Taking the poor condition property. Your parents have passed away and have lived in their home for fifty years and the last time they did any improvements to the home was when they purchased the home when you were in middle school. As they aged, they slowed down on maintenance on the property.
You and your two siblings, who live in other states, are the heirs to a home that needs upgrades to kitchen, baths, flooring, new windows, roof, plumbing and electrical. The landscaping is the eye-sore on the block.
Similar style homes in the neighborhood are selling for about $850,000. In very good to excellent condition with kitchens, baths and homes at the least updated to the 21st century.
Looking to maximize the value of the property, you have gotten bids from contractors and the bids range $150,000 to $200,000 and seven to eight months to completion.
A cash-for-your home offer in its current condition may be in the $500,000 to $550,000 range and closing in a week.
Do you and your siblings want to provide the funds for the necessary repairs and upgrades to get the home on the market, and then hope the market price stays the same or increases by the time the home is market ready for $850,000? Or do you want to take the cash today?
Breaking down the math. You spend $175,000 to get the home ready, during the seven months and put your home on the market. After a few weeks you get an offer for $850,000. The rule of thumb for Southern California costs for homeowners to sell their property, using an agent, is about 8% of the sales price, in this case $68,000.
Subtracting the construction costs and sales cost from the sales price, you net proceeds are approximately $607,000.
Or about from $57,000 to $107,000 more than if you had taken the cash offer seven months prior. That is a lot of money. But what if…you had to borrow the money for the remodel using a HELOC with the rate at the prime rate, currently 8.25%, that would add approximately $10,000 to your costs…you had to pay insurance and real estate taxes for construction period, another $2000…home prices did not hold during your construction period and you end up selling for $825,000…now your net is approximately $20,000 to $87,000 depending on the original offer.
In this instance the family may decide to take the cash offer and avoid the time delay and the market and cost of construction increasing risk buy fixing the home themselves.
Similar math can be done for those in foreclosure, or otherwise needing a fast sale, penciling out the costs of waiting for closing, costs of a traditional sale using an agent, and other carrying costs for waiting for closing versus the cash offer on the table.
Since March 2020 when the Covid Market spiked home prices, we have seen all cash offers from buyers who are not real estate companies, increase tremendously, up to almost 50% of offers made and accepted in many markets. These offers are typically on very clean homes ready for occupancy and have been near, at, or above list price.
For homes that are in less then pristine conditions, or have other factors such as mortgages in default, taking a cash offer below current market price for a top of the market ready home, may be a good decision.
Have a question? Ask me!
Maybe finished? As expected the Federal reserve raised its benchmark Federal Funds interest rate by 0.25% (one-quarter of one percent). It is the tenth rate increase since it started its Quantitative Tightening (QT) policy in March 2022, taking the Fed Funds rate from 0-0.25% range to 5-5.25% range. During this time the prime rate (what is the basis for Home Equity Lines of Credit and other consumer rates) from 3.25% to 8.25%.
Mortgage rates reaction should be up but, in comments after the announcement of the rate increase, Fed Chair Jerome Powell indicated that the Fed is ready to take a pause on future rate increases, and future increases will be more “data dependent.” Mortgage markets, and other fixed rate markets such as Treasury bills and bonds, reacted positively to the rate-pause comments, resulting in a drop in rates midweek.
That data dependent data did not help the sentiment of the rate markets after Powell’s comments, as the Labor Department’s monthly jobs report for April that was released today showed a very tight labor market is still in effect in the United States, putting more pressure on continued inflation staying higher than the Fed would like. Smashing expectations (180,000 new jobs), the economy added 253,000 new jobs last month, lowering the unemployment rate from 3.5% in March to 3.4% in April. Wages, which increased 0.3% in March, were up 0.5% in April. Everything in this report was “data dependent” information that may have the Fed pause the pause in interest rates and have another increase in rates sooner than later. Mortgage and bond markets did not respond positively today.
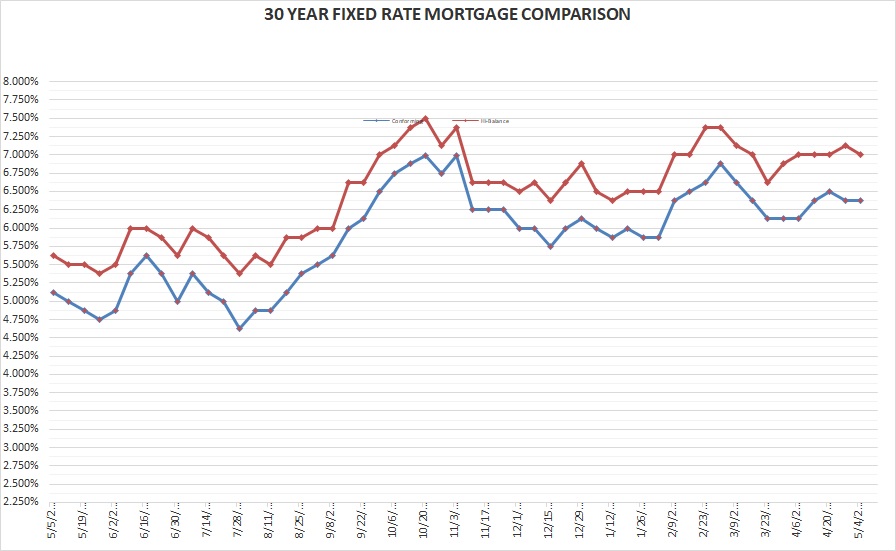
Rates for Friday May 5, 2023 The negative reaction today to the jobs report was equal to the positive reaction earlier in the week to the Federal Reserve news, as a result conforming rate is the same as last Friday,
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Flat
30-year high-balance conforming 7.00% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Past client and long time WR&MU reader Carol is a little miffed at yours truly. She sent a text yesterday that included of picture of her in the rain and puddles on her patio from the rain. Her miffness (not in Webster’s) was due to my WR&MU on April 21st when in this section of the WR&MU I asked if the Southern California Spring, with cold/cool weather and rain was over and we were heading into pre-summer with warm, sunny days. She infers that my asking the question begged the answer from the Universe that we in fact were not through with the cool, wet weather. Maybe Carol’s message with jinx my jinx and….I won’t write it.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


