

Should we get an adjustable rate mortgage?
Question of the week: Should we get an adjustable rate mortgage?
Answer: Astute readers of the WR&MU will be thinking, “didn’t we just have this question not too long ago?” and they will be right.
In October 2023 we asked the same question, and the answer was “maybe.”
The answer this week is, “probably not.”
In October the rates on a mortgage that is fixed for the first 5-years of the mortgage were lower than the rates no a 30-year fixed rate mortgage.
Today, the opposite is true as rates are in what is know as an “inverted yield curve;” which means rates are higher on shorter term investments (therefore mortgages) than longer term mortgages.
Ordinarily, with 30-year mortgage rates expected to drop creating a target rich refinance market for the mortgage industry, and a payment saving boon for homeowners, adjustable-rate mortgages (ARMs) are a very viable option. As discussed last October, if there is a very high probability the 30-year mortgage rate will be lower in the future than the current ARM rate, getting the lower rate today to lower it further in the future makes sense.
However, this is not the case when the ARM rates in some cases exceed the 30-year rate by up to one-percent, or more.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Hey guys, how does the summer look for you? This seems to be the question the Fed will be asking at its next meeting when debating lowering its benchmark interest rate after economic data from February released this week.
September revisited. Both the Consumer Price Index and retail sales showed their biggest month-to-month increases since September. Gasoline prices rose in February impacting both indexes. That said the 0.4% increase in the CPI was matched with the “core” CPI (gas and food stripped out of data), also increasing 0.4%. Year over year CPI increased from 3.1% to 3.2%, while core CPI dipped from 3.9% to 3.8%. Whichever part of the index one looks at, they are a long ways from the Fed’s 2% target, and more importantly not declining with any rapidity.
Consumers are keeping cash registers ringing, as retail sales were up .6% from January, whose retail sales were adjusted up from initial reports. Sales were boosted by the strong labor market and tax refunds working their way into household accounts.
Rates for Friday March 15, 2024: Several of the policy makers at the Fed want solid evidence that inflation is slowing towards the 2% target before lowering rates. Economic data the past few months show there is scant, to no, evidence slowing is imminent. Feeling rates are as sticky has inflation, markets pushed rates a bit higher this week, and the upward pressure is increasing.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
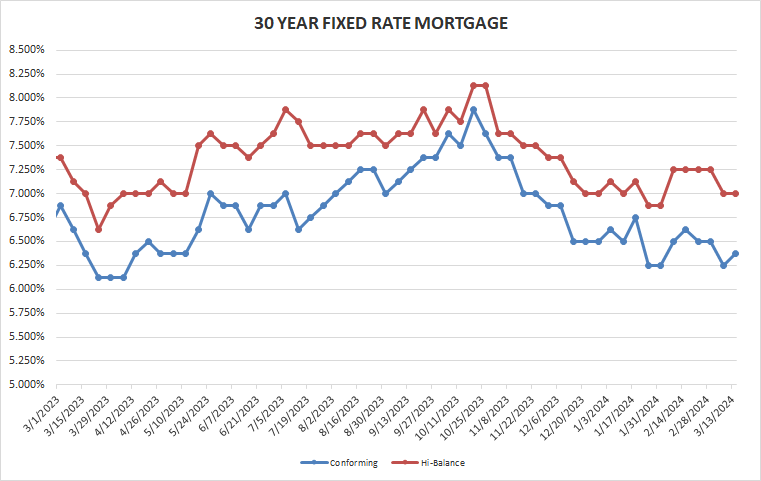
30-year conforming 6.375% Up 0.125%
30-year high-balance conforming 7.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Sunday brunch and lunch out on the town should be popular this weekend with St. Patrick’s Day. The weather locally should be nice for those who want to enjoy a nice meal the crawl, I mean stroll, around areas with more than a few establishments.
Corn the beef, boil the cabbage, chill the Guinness, and raise a pint in cheers to friends and family here and gone.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


