

When is the best time to lock in our mortgage rate?
Question of the week: When is the best time to lock in our mortgage rate?
Answer: As soon as you can, especially in a turbulent interest-rate market.
To lock in a mortgage rate for a client we need a transaction type, property address and type, loan amount, property value, credit score and time frame (how long until we close).
From these factors we can generate rate and price options for you to select for your purchase or refinance transaction. For most purchases clients are more inclined to pay points to buy down the interest rate; for most refinances clients are more inclined to go with higher rates and low to no-point options.
Some clients are tempted to wait to lock in for a few reasons. One, they feel rates can drop and save them some money. Two, the shorter period the rate is locked in the lower the cost for the same interest rate.
Taking example two, rates are priced in 15-day increments. We can lock in a rate for 15, 30, 45, or 60 days (there are also 90-day rate locks available but that discussion is for another time). With each 15-day increment, the price for the same interest rate is 0.125 points higher.
For example, if you are looking at a 3% mortgage for $500,000, the price we receive from our mortgage partners would be $625 higher for each 15-day period. A 60-day lock is 0.375 points, or $1,875, more costly than a 15-day lock.
When getting rate quotes from lenders it is important to know how long the lender will be locking in the rate for that quote. Over the years I have had many conversations with clients asking about rates who have responded, “I just spoke to Someother Lender who said the cost for the same rate is $1500 cheaper.” When asked how long the rate would be locked, the answer is usually, “they didn’t say.”
Unsurprisingly the quote was for 15-days and I was quoting 45-days to match their purchase transaction closing time frame.
Back to the question and answer, why is it better to lock in your interest rate as soon as you can?
It is the nature of interest rates to go up as if on a rocket and come does like a feather. Too often homebuyers and owners trying to “time” the market miss out because by the time they realize rates are going up, they have gone up. By trying to save an eighth of a percent (0.125%) in interest rate and save $35 per month on their mortgage, they mistime the market and the rate has climbed by 0.25%, costing them $70 per month, and possible higher points as well.
For many months I have been Chicken Little, claiming “rates should be rising, rates should be rising.” The markets and numbers appear to be fulfilling my expectations. Lock your rate when you can.
Twenty million people. That was how many fewer people are receiving unemployment benefits last week that one year ago. Data on unemployment claims and benefits presented positive news for the labor markets yesterday, with new claims being under 300,000 for the first time since March 14, 2020—the week the pandemic closed the economy.
The Fed has indicated it will keep rates low based on the health of our labor market. The data today, and over the past few months, indicates a healthier labor force. As a result, the news yesterday pushed mortgage rates higher.
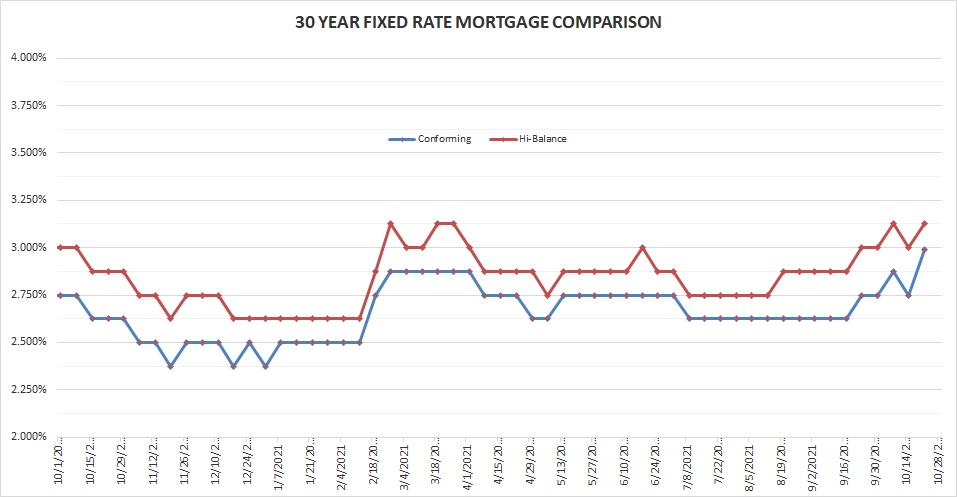
Rates for Friday October 22, 2021: Markets had been putting upward pressure on rates since last Friday, the news yesterday pushed them higher. We see the 30-year conforming rate at its highest mark since June 5th of last year. Some of the upward pressure has been technical, investors reacting to data sets and points, but significant pressure is the result of anticipation of the Fed slowing its purchase of mortgages and U.S. Treasury debt—which should result in rates moving up.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 2.99% Up 0.24%
30 year high-balance conforming 3.125% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Greetings from Boston. Leslie and I have been on the daughter tour this week as we flew into New York City on Monday and spent some time with our youngest, then took the train to Boston where we will be spending time with our oldest, returning home Sunday evening.
We perfectly timed our visit to greet what I grew up knowing as Indian Summer, a period of warm, dry weather in autumn to give one last reminder of how nice that can be before winter cold, winds and snow arrive.
As we took the train north, every half hour it appeared as if more and more of the leaves were turning from green to orange, yellow, red…a lovely ride that I encourage you to take if you have the chance as the track runs along the coast much of the way.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


