

Are you licensed?
Question of the week: Are you licensed?
Answer: Yes.
On bottom of all my email communications you will see licensing information for myself and United American Mortgage Corporation, with whom I am affiliated and have my licenses registered.
Residential lenders and loan originators in California have to be licensed by either the California Department of Real Estate or California Department of Business Oversight.
As such, one of the licenses listed for UAMCO and myself is for the California Department of Real Estate. I have been licensed with the DRE since 1987 when I started in the mortgage industry, upgrading to a broker’s license with the DRE in 1988.
The DRE requires a “designated officer” for every real estate company in the state, and mortgage companies operating under DRE licensing. Any individual working as a real estate agent, or mortgage originator “hangs” his/her license under that of the designated officer. The purpose of this is to have an individual who is personally responsible for the actions, behaviors and communications of those whose licenses are registered with the broker/company. This eliminates a corporate veil of liability that can protect individuals from corporate or employee malfeasance, which with some exceptions, results in stricter oversight than not having someone with personal responsibility.
At UAMCO, our designated officer is its founder Al Hensling who began in the industry around the same time I did. You can tell how long someone has been licensed by the DRE by their number. Al and I’s licenses start with 009…which indicates in the 1980’s; licenses being issued this year start with 023…so about 1.4 million real estate licenses have been issued in California since we received ours.
That is one of the licenses listed on my record. The other is NMLS, or National Mortgage Licensing System.
In 2008 the Secure and Fair Enforcement for Mortgage Licensing Act (the S.A.F.E. Act) was passed. This Act required mortgage loan originators (MLOs) and the companies they worked for to be registered nationally. As well, it required states to pass legislation requiring MLOs to be licensed according to national standards. All state agencies that licensed MLOs had to participate in the Nationwide Mortgage Licensing System (NMLS).
As with DRE licensing, both companies and individuals must also be licensed by the Nationwide Mortgage Licensing System.
By 2011 all individuals participating in originating mortgages with consumers had to be registered with the NMLS. Most MLOs were required to pass an exam to be registered (exempt from the exam were those working for insured depository institutions regulated by one of the alphabet banking regulators (OCC, OTS, FDIC, NCUA for example).
When the S.A.F.E. Act passed requiring an exam for entry into the mortgage business I was mostly happy—only mostly because of the carve out from the exam for those working for major banks and other institutions.
I was happy because the NMLS exam was significantly harder than the exam required by the Department of Real Estate to obtain a salesperson or broker license. I was happy because a lot of individuals who should not have been in the mortgage industry opted out of the exam and registration. I was happy because no longer could a bad actor in the mortgage industry move from jurisdiction to jurisdiction when they had a license suspended or revoked.
It is my desire to see something similar be put in place for real estate agents and brokers so those responsible for the listing and selling of families’ primary assets also have a more rigorous process for obtaining licensing, are nationally registered and have stricter consequences for malfeasant behavior and actions.
Note that for both the DRE and NMLS, continuing education is required to maintain a license.
The DRE requires renewal every four years, which requires 45 hours of courses; there are five required 3-hour courses: ethics, agency, fair housing, trust fund handling and risk management.
The NMLS renewal is annually and requires eight hours of continuing education. Ethics is always one of the areas of coverage, as well as California specific rules and regulations, other topics vary from year to year so over time many areas of lending and real estate are covered.
If you are interested in seeing if someone is appropriately licensed, have any disciplinary actions on their records or other information, the NMLS has a consumer access website where licensees can be looked up by name or license. The site to lookup licenses with the Department of Real Estate for agents and mortgage originators can be found here.
The bulk of the WR&MU was written yesterday, Thursday, since today I have my all-day continuing education class for my annual NMLS renewal. Oh, yes. It is every bit as exciting as you are imagining…
Have a question? Ask me!
The big news, while not news as everyone was expecting it, was the announcement that the Federal Reserve lowered its benchmark interest rate. What was unexpected, and roiled markets a bit, was in the rate announcement, Fed Chair Jerome Powell stated that the decision to lower the rate was not unanimous and there was quite a bit of discussion. Heading into the meeting, the consensus from Fed watchers and investors was that another rate cut in December was pretty much assumed. Powell’s “Far from it,” comment raised eyebrows, as he said, a “growing chorus” of voters on the open market committee (makes decision of rates and balance sheets) who wonder if more cuts are warranted.
With no economic date coming forward for the month the federal government has been shut down, the Fed is operating on supposition and pre-shut down trends. This uncertainty as to what is happening in the economy—higher inflation, slower inflation, strong job market, increasing layoffs—has many Fed officials wanting to pump the brakes on rate moves until they have a clearer, actually a clear, understanding of what direction our economy is headed.
One action announced by the Fed that may impact mortgage rates is the Fed will no longer be rolling over funds received from their holdings of Mortgage-Backed Securities* (MBS) that payoff back into buying more MBS.
*Mortgage-Backed Securities are bundles of mortgages, think tens of millions per bundle, sold by Fannie Mae and Freddie Mac after they purchase mortgages from lenders around the country. MBS sales give Fannie and Freddie money to buy mortgages from lenders who use proceeds from their sale of mortgages to lend to borrowers with new mortgages, starting the cycle again.
In September, we went into detail explaining how the Fed uses the purchase of MBS, and U.S. Treasuries, to put downward pressure on rates. For the past several years, as those holdings of mortgages and Treasuries paid off, the Fed would use the proceeds to buy more mortgages with mortgage payoffs and more Treasuries for Treasury payoffs.
The Fed will begin taking the proceeds from MBS that pay off, either through loan terms ending, sale of homes with mortgages, or refinancing of existing mortgages, and purchase short term Treasury bills.
This shift in purchasing from more MBS to Treasuries will reduce the demand, or soaking up of supply, from MBS. Reduced demand typically results in lower prices. For bonds, and Mortgage-Backed Securities, lower prices mean higher rates.
Depending on whether investors step up to purchase MBS to the extent that absorbs the Fed’s absence from the market, and new mortgages being funded and sold, will determine if the Fed’s action pushes rates higher.
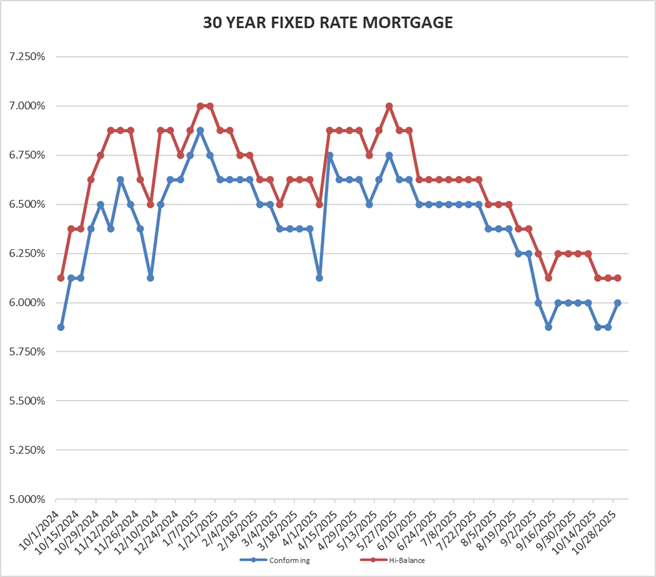
Rates for Friday October 31, 2025: The comments in the Fed rate release resulted in a bump in the 30-year fixed rate from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 6.00% Up 0.125%
30 year high-balance conforming 6.125% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The Dodgers need to buck history to win the World Series. To do so they must win tonight and tomorrow in Toronto; many broadcasters have said the Rogers Centre, home of the Blue Jays, has been the loudest of any stadium than can remember during this year’s playoffs.
The history buck the Dodgers need? No team that has swept the playoff series before the World Series has beaten an opponent in the Series that won a seven game playoff to get into the Series.
One of my joys in life is esoteric sports statistics.
Leave that porch light on and fill the trick-or-treat sacks for the little ones tonight!


