

Are rates going down?
Question of the week: Are going down?
Answer: Yes, but…
When?
Not tomorrow.
Consistent readers of the WR&MU know that the Federal Reserve raised its bench mark interest rate (the federal funds rate) starting in March 2022 as inflation was starting to climb rapidly. The stated objective was to increase rates, slow the economy, likely push up unemployment, until inflation was down to 2%–the historic “acceptable” inflation rate that the Fed feels supports moderate economic growth and stable job growth.
Last year the Fed said it was predicting it would likely begin to lower the Fed funds rate in 2024, possibly as many as six times.
For the Fed to lower rates, it needs to feel that inflation is under control and tracking lower, labor markets are at worst neutral with wages in line with inflation, and the economy growing very slowly, or contracting.
Economic data thus far in 2024 has not been supportive of lower rates, to the contrary some feel the Fed may need to start increasing rates again.
Wednesday the Bureau of Labor Statistics released the Consumer Price Index for March—a key indicator of inflation. The report showed that prices grew 0.4% in March from February; it is the third month in a row that CPI has grown at a high rate. Prices were up 3.5% from March of 2023, the year-over-year price increase in February was 3.2%.
The “core” inflation rate is considered to be a bit more dependable overall gauge of prices as it strips out energy and food prices which are volatile from month-to-month, and is given more weight by the Fed when gauging inflation. The core rate also increased 0.4% for the month, however the annual rate soared to 3.8%.
The report, on top of last week’s jobs report showing a very strong labor market, puts a significant amount of doubt into markets as to whether the Fed will cut rates in the near future. As well, the data has many feeling the not only with the Fed not cut rates this year, but may increase them to cool off the economy and lower inflation.
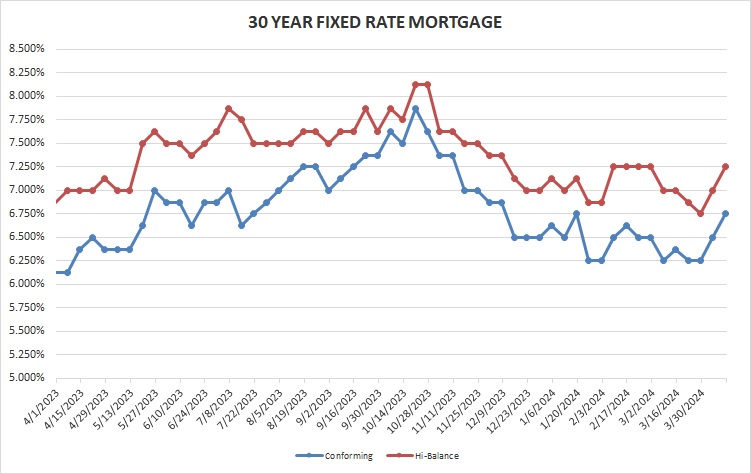
As you might expect, mortgage rates have spiked for the second week in a row.
Back to our question of the week, are rates going down? Yes, at some point they will. As to when, not any time soon absent an external event.
Defining “rates going down,” for me this is a consistent period of time with rates going lower in measured tempo, such as we saw from February to early March, and continuing for more than four to five weeks before leveling off and then starting to drop again.
I do not see this happening before mid- to late summer, at the soonest.
To the contrary, I foresee rates increasing before they start to drop again.
For those who are rating for rates to get below 6% before buying my crystal ball says you may not be buying your new home until 2025.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Inflation numbers translated to personal finances and how it looks…
For the past three years we have seen data that inflation was increasing 1%, 0.5%, etc per month; 5%, 7.8%, 3.5% per year. What does this mean to consumers? As the 3.8% increase in prices this March from 2023 is on top of the 5.1% increase in 2023 from 2022 and so on.
For a better understanding, since 2021 prices have increased about 17%. The $100 pair of shoes in March 2021 cost $117 in March 2024. You may think $17 isn’t that much. That is on one item, spread it across everything you buy.
On the other side of your finances is the income to pay for the $117 pair of shoes. To keep up with inflation, if you earned $10,000 in March 2021, your pay needs to be $11,700 per month in March 2024—an increase of 17%. If you pay keeping up with inflation?
Rates for Friday April 12, 2024: The result of the commentary above is that rates increased 0.25% (one-quarter of one percent) for the second week in a row. Rates are at their highest rate since mid-January.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.70% Up 0.25%
30-year high-balance conforming 7.25% Up 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Like millions of golf fans across the country, likely around the world, technology has enabled me to have The Masters golf tournament in the corner of one of my screens while I work.
I will admit to some evil thinking when I watch professional golfers. When they completely mess up a hole, perhaps dunking a few balls in the water on a par 3 and taking an eight, I have a mini celebration as it means for that particular player and hole, I play golf like a professional!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


