

What was the result of the housing related ballot propositions?
Question of the week: What was the result of the housing related ballot propositions?
Answer: In September I wrote about propositions on the California ballot that were housing related and my positions on them. For those not following closely, here are the results. So far; as of 9:30 this morning there are 1,429,504 “estimated total ballots remaining”.
Per California law, the state has until December 13th to certify all results. So, the results below could theoretically change in the next four weeks.
Proposition 5 would change the constitutional requirement of a two-thirds voter approval to only fifty-five percent approval needed to pass local bonds and taxes for affordable housing and infrastructure. I was against the measure, as were 55.5% of Californians. The current results will hold even if every one of the remaining ballots votes in favor of Prop 5.
Proposition 33 would repeal the Costa-Hawkins Rental Housing Act of 1995, thereby eliminating limits to rent control ordinances for cities and counties. I was against the proposition and so were 60.5% of voters. Like Prop 5, the current results are beyond the reach of the remaining ballots to change the result.
One other proposition that I did not include on my list of housing impacted measures was Proposition 32 which would increase the minimum wage in the state. If passed Prop 32 would have impact on housing costs and HOA dues as it would increase the costs of home construction and maintenance. Current results show the Proposition being defeated with 51.1% voting against. The difference as of this morning is almost 300,000 votes, so there is still a chance this proposition may pass, if 60.5% of the remaining ballots are in favor of Prop 32. Probability is against this happening, but there is also the probability that it may.
Schedule an appointment to discuss your options if you are considering purchasing a new home or property or refinancing an existing one and want to know the mortgage options available to you.
Have a question? Ask me!
Positive for economy is negative for rates. That is a general economic principle, one that is on display this week. October’s Consumer Price Index data matched September’s showing a 0.2% increase, with a 0.3% gain in the “core” data (energy and food removed). It was the fourth straight month the full index increased that amount, and the third straight month the core index as increased 0.3%. Year over year CPI is up 2.6%, up from last month’s reading of 2.4%, and the core index remains at 3.3% year over year. The year over year index increased for the first time in seven months. The primary factor in keeping inflation in its current range is housing. Housing costs were 65% of the price increase in the data, up 4.9% from last October. Higher costs are slowing for renters and home buyers, from 5.4% rate 6-months ago and 6.7% last year, however slower increases are not lower costs, just less high. Not positive for mortgage rates.
Consumers are still ringing cash registers at a steady pace. Retail sales in October were a strong 0.4% in October, and September’s sales were twice what was previously reported. Retail sales are one-third of consumer spending, and a strong signal as to economic strength and consumer sentiment. Consumers feel confident in their current financial position, job security, and future as evidence by a 1.6% increase in new auto sales (if uncertain of your future you likely will not enter into an auto loan contract). Restaurant sales are another indicator of how secure families feel in their financial stability as dining out is a discretionary expense that is quickly eliminated from many family budgets when times are tough, sales increased 0.7% last month. Also not positive for inflation rates.
Besides economic data showing sticky inflation data not moving to the Federal Reserve’s 2% inflation target, and retail sales portending a very strong 4th quarter for consumer spending and GDP, rates were influenced by Fed Chair Jerome Powell, and other members of the Fed’s Board of Governors, making statements indicating the Fed may slow the pace of its rate cuts. Signals to investors and markets to maybe not price lower rates into their investment strategies.
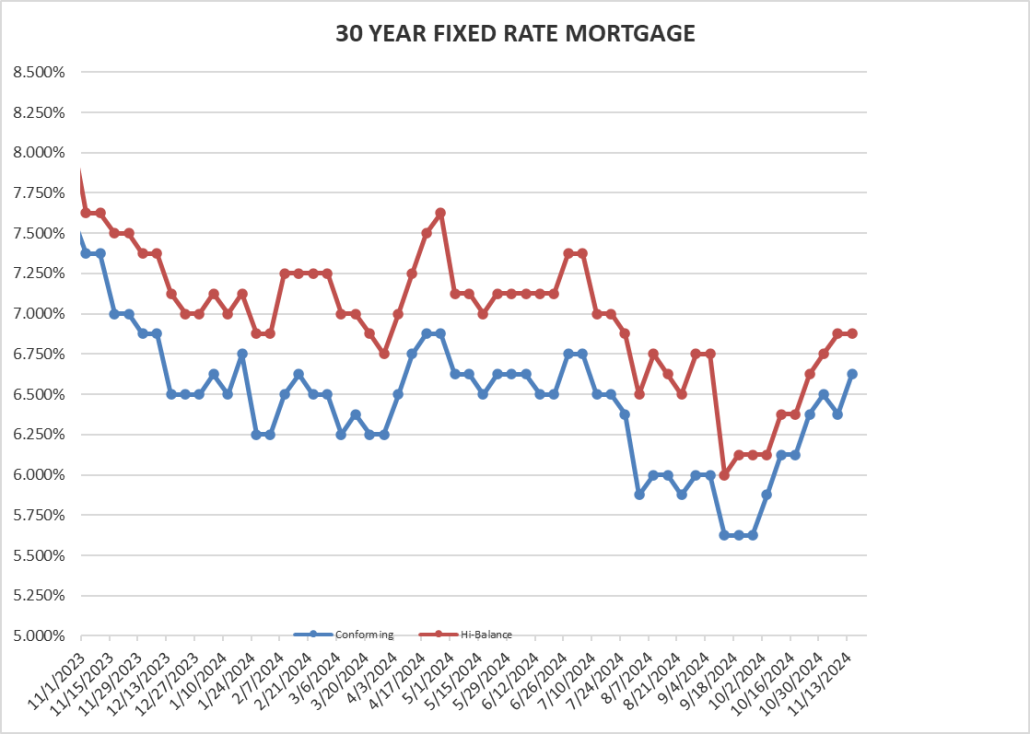
Rates for Friday November 15, 2024: After rates dropping for the first time since mid-September, rates continued their upward movement this week, with the conforming rate at its highest since my birthday in early July (reminder for your calendar for next year…).
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.625% Up 0.25%
30-year high-balance conforming 6.875% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Tuesday afternoon was a great mental health day for me. For the first time in just over a year (375 days to be more precise), I put a peg in the ground and hit a golf ball on a golf course. Since having both knees replaced, I have hit balls on the driving range, but Tuesday was the first time playing a round, well half a round as we teed off late and darkness pushed us off the course. What a pleasure to find my ball in the rough, hit it out of the sand onto the green, miss a 15-foot putt by mere inches, repair a ball mark after a well struck 9-iron on the green.
For golfers reading, the challenge moving forward is knowing my distances on different clubs, and getting used to having my drives being less as far as before when they were less as far are before.
My results far exceeded my expectations, and I can see the day drawing nearer when I will be able to walk 18-holes with my push cart looking for my ball. The wait was worth it as both knees are a lot better than they were before the surgeries.


