


Why are we going through my application information again?
Question of the week: Why are we going through my application information again?
Answer: Because of government bureaucracy and its need to act.
For over twenty years the residential mortgage industry has used the same mortgage application with very little changes. The Universal Residential Loan Application (URL), or for those in the biz the 1003 (ten-oh-three), has been the standard from which all software systems have been based. It contains four pages of data and a blank page 5 on which we can type in information for underwriters, such as explanations for credit inquiries or lates, misinformation regarding prior addresses, explanations for gaps in employment, or the purpose of the refinance if equity is being pulled out.
For many reasons that make sense to those who do no work in the industry, the Federal Housing Finance Agency has decided that what has worked for many years is not good enough and redesigned the URLA. The result is an application that is nine or more pages for an individual borrower and fifteen or more pages for married borrowers.
The new application has 94 new data points, the total number of fields has increased by 236, or 130%, and in no way changes how the decisions are made for obtaining loan approvals.
Very long-time readers of the WR&MU may remember when the then new Consumer Finance Protection Bureau scrapped the Good Faith Estimate the industry had been using for years and issued a new form, also called the Good Faith Estimate. The old form was one page, listed every charge on the transaction, and the borrower signed the bottom of the page. The new form was three pages, included all the same information but spread out, and did not require a signature from the borrower acknowledging they had read and received the form.
The new URLA is similar in that it is three times as big and requires little acknowledgement from borrowers that the information they are attesting to is correct. As mentioned above, the prior URLA required initials or signatures on every page, the new form requires one initial on the first page and then a signature later in the documents. In between are several pages that those in the industry who wish to operate in nefarious manners can complete with data without the borrowers’ knowledge. Not sure how this is better for the borrower or the industry.
There are two major software companies that the overwhelming majority of lenders use, the one we use, Point by Calyx, I believe is the preferred program for more than have of loan originations from mortgage companies.
Our processing program, that I have used since about 1998, enable me to type in all the information required on the 1003 form, upload the data to our credit report provider, then using the data on the application and from the credit report, upload the data to Fannie Mae and Freddie Mac for loan approvals.
As well, using a standardize Fannie Mae file so we can upload all the loan and credit information to the lenders we work with to register and lock in rates.
This system has some bugs once in while when there are upgrades and slight changes, but overall has worked seamlessly for decades.
The announcement and release of the new URLA was made some time ago and all the software designers for processing software companies, Fannie and Freddie, lenders, have had time to code for the new form. Despite this, the new role out this week has been fraught with error messages, data that does not transfer from the software to printed pages, and inability to get proper responses from Fannie Mae or easy uploads to many lenders. As with all new role outs, software companies can make as many beta tests as they wish before a program is put into widespread use, when real world application of the programs show problems.
Back to our question, why are we redoing many applications? Because we have 94 more questions to ask and about 130 more fields to complete from the old application, information we have not received from our clients with the prior application form.
Many of the questions being asked have to do with demographic information that borrowers may not be comfortable answering, others have to do with more detail about the nature of employment or sources of income. Why this information is required in 2021 when hundreds of millions of homeowners were well served by the prior application is can only be answered by some people sitting at desks in Washington, who are no doubt now wondering what project they can take on next to better “protect and serve the consumer.”
The new URLA has many in our industry thinking of President Reagan’s infamous statement, “The nine most terrifying words in the English language are, ‘I’m from the Government, and I’m here to help.’”
Have a question? Ask me!
Jobs data for February backs up much of my commentary in last week’s WR&MU answering the question, “Why are rates spiking?” Quick synopsis for those who missed it and don’t want to read it, too much money pouring into the economy from Washington when it is not as needed as it was several months ago. Today the Labor Department announced the economy added 379,000 jobs in February, with the bulk being jobs in the leisure and hospitality industries; areas of the economy very susceptible to consumers discretionary spending. The consensus estimates for new jobs added to the economy was 210,000, well below the actual number. The news is mortgage rate unfriendly as it supports the belief that the economy is growing at a more rapid pace than expected and higher prices and inflation are sure to higher than expected as well.
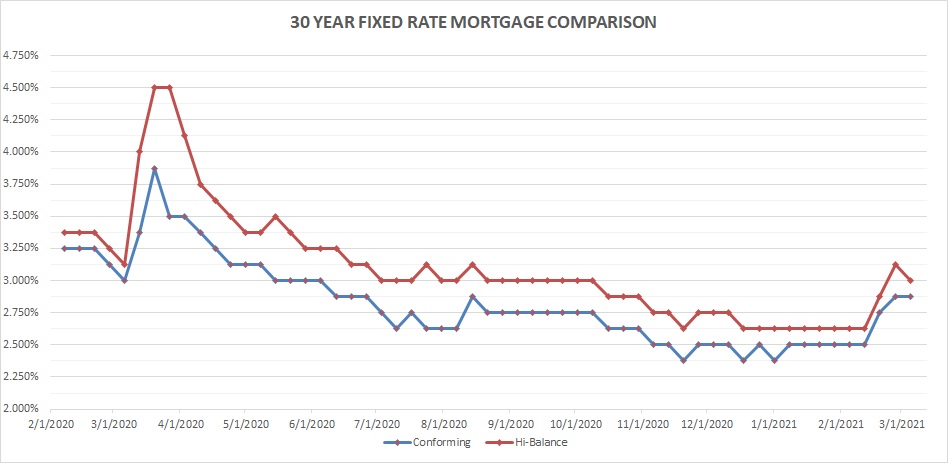
Rates for Friday March 5, 2021: Markets have been see-sawing this week as investors show their concern for higher rates. Day-to-day Mortgage Backed Securities (MBS) saw large increases and decreases in prices daily. Despite the positive jobs news today, rates today have rebounded slightly from yesterday and conforming rates are flat from last Friday and high-balance rates have slipped back a little bit. Our market is very volatile and the long-term expectation is for higher rates. Keep in mind, while rates are moving up, they are still at incredibly low, historic, levels.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 2.875% Flat
30 year high-balance conforming 3.00% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Do you know someone who is between the ages of 21 and 35 in the greater Long Beach area that would like to interact with others to build personal and business relationships, join together to work on community projects, mostly focused on education and youth services, and have a good time while doing so?
Many of you know that I am very involved with the Rotary Club of Long Beach. Rotary is an international organization with 1.2 million members around the world. Our club in Long Beach, with 275 members, provides over $350,000 in scholarships to students at Long Beach City College and Cal State Long Beach, have distributed almost 300,000 books to local elementary schools, and have programs that support area youth from pre-K through college.
Our club is starting a Rotaract club. While affiliated with the Rotary Club of Long Beach, the Long Beach Rotaract Club will be independent, with its own treasury and projects run by the members. It is an excellent opportunity for younger adults to become involved in a service club that benefits them and their community.
On Thursday March 18th at 6:00 we will be having a meeting (on Zoom) to introduce Rotaract to those who are interested in learning about the new club and how to join. It is a great opportunity to not only become involved, but being an early members an opportunity to participate in leadership and shaping the club. Rotaract members get many of the benefits Rotarians do from the “regular” clubs, with reduced dues and the opportunity to be with others in their generation.
If you know of any young adults who might be interested please contact me and I will forward names and contact information to our club’s Executive Director so they can get the meeting information and link.
Rotary has greatly enhanced my life, I have met some incredible people I would not have met otherwise, feel proud to be part of a group that has been very responsible for the near eradication of polio around the world, provides resources for bringing clean water to villages around the globe, and supports literacy and education in our community and others worldwide. I want to share this opportunity with others, please reach out to me if you know someone who may be interested—or if you are interested in learning more about the Rotary Club of Long Beach with an interest to become a member!
Again, Thursday March 18th at 6:00 for young adults between 21-35 who are interested in joining the new Rotaract Club we are starting.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


