

Will the federal government shutdown impact the timing of my loan approval or closing?
Question of the week: Will the federal government shutdown impact the timing of my loan approval or closing?
Answer: It’s like I jumped into my DeLorean DMC-12 and dialed up 2018 instead of 1955 with this question.
You likely recall that the last federal government shutdown occurred for 35 days, from December 22, 2018 to January 25, 2019.
Short, and ambiguous, answer to the question: For the majority of mortgage applicants, probably not. For some, probably.
Depending on what type of mortgage, or what services are required to close, you may experience delays during the shutdown.
If you are in a rural area and obtaining a USDA, or perhaps waiting for FHA to approve a condominium complex in which you are purchasing or refinancing one of the units, you will likely experience delays waiting for approval from federal agencies.
For borrowers with properties in areas that required flood insurance, which is available only through the National Flood Insurance Program (NFIP), there will likely be delays if the NFIP cannot issue or renew policies.
At the beginning of the 2018-19 shutdown the NFIP lost authority with the budget impasse, FEMA announced it would not renew or issue new policies. After extreme pressure from Congress, insurance industry, and real estate industry, FEMA switched positions and announced NFIP would continue issuing and renewing flood insurance policies. They were able to do this as Congress had passed a short-term reauthorization for NFIP through May 2019, ergo it had authority to issue policies.
Unfortunately for those who will need federal flood insurance to close mortgages, the is no authorization for NFIP that extended beyond September 30th. If your loan requires flood insurance, absent some action by FEMA or Congress, your closing will likely be delayed until some action is taken.
One requirement for many mortgages is verification of your income by a review of your tax transcripts as filed with the IRS, especially if you are self-employed. For this process, we use IRS Form 4506-T.
During a government shutdown the requests for a copy of your returns are not processed. Having experienced such delays in the past, in recent years lenders have eased the burden by allowing some work arounds to the Form 4506-T requirement, typically a copy of the cancelled check or other proof you paid taxes owed on the tax returns provided, or a copy of a bank statement showing the deposit of your refund that matches the refund on your tax returns provided.
Government insured loans, such as VA or FHA, are not impacted by the shutdown as the processing and underwriting is performed by private companies and not government agencies. While Fannie Mae and Freddie Mac are quasi-government agencies they are operated as private companies and are unaffected by the shutdown.
The primary area of impact during government shutdowns, once flood insurance is authorized, are inquiries for loan issues in which a response is required from either VA or FHA. It is very rare that a situation arises in which a lender will require a response from either of the agencies in order to approve a loan, but they do arise from time to time and any such cases arising during the shutdown will likely face delays until someone is available to reply.
In a broader view, the impact of the shutdown on mortgages is the impact it may have on the economy and subsequent impact on interest rates.
Fundamentally, if there is an impact on rates it would be for rates to decline. A very prolonged shutdown could result in negative economic impact and regular readers of the WR&MU know that poor economic performance usually leads to lower interest rates.
Have a question? Ask me!
Not much to report, with no reports. The shutdown has shutdown government agencies that provide economic reports that are used by investors, agencies, banks, the Federal Reserve, to make decisions. Today, the first Friday of the month, is when the Bureau of Labor Statistics would be releasing it Monthly Employment Situation Report for September. Depending on the number of new jobs added to the economy, rates could move up or down, the Fed may decide to move its benchmark rate, or not. With no report everyone is left guessing, or waiting. If the shutdown continues into the month there will be no data on CPI, GDP, personal income and spending, or any economic activity tracked by the government.
Historically, the response to a shutdown is lower rates as investors pull money from riskier investments, like stocks, and undergo a “flight to safety,” investing in fixed rate assets like Treasury bonds, and mortgages.
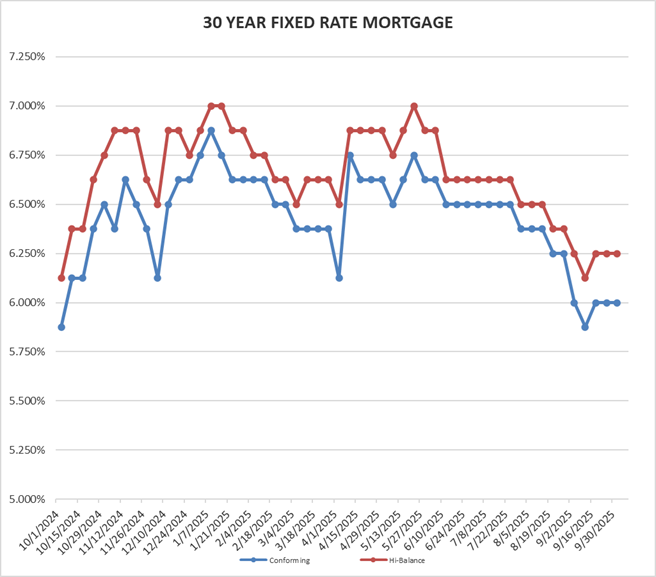
Rates for Friday October 3, 2025: We are flat again from Friday to Friday as investors try to read tea leaves in a cup of coffee.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 6.00% Flat
30 year high-balance conforming 6.25% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Likely no WR&MU next Friday as will be leaving for a trip to East Coast bookended with seeing daughters in New York and Baltimore.
In the meantime, I leave you with this, Go Phillies!


