

Our roof is leaking; can we sue the seller?
Question of the Week: Our roof is leaking; can we sue the seller?
Answer: Probably not.
This question came up as when I got up on Monday morning and was headed to kitchen for my morning routine of coffee and reading, I heard a “plop…plop…plop” coming from the family room. “Uh-oh” I thought, because I knew we have a leak in the roof, which is flat (a whole other WR&MU perhaps) that has had some issues in the past. I got out the towel and bowl and we put in the call to our roofer.
Long-time readers of the WR&MU know that almost every winter our question of the week involves why home buyers should go out and look at potential homes when it is raining, or shortly thereafter.
For those who don’t want to click, the reason is so you can see any issues that rain, and water, may be causing for the property. Including a leaking roof. Because in Southern California we can go months and months and months between days of rain, think February to December in some years, home buyers do not have many opportunities to see what rain and water accumulation does to the house and property.
Because of this, if you purchase a home in late summer, it rains in January and you have a roof leak, you might look for some financial relief to help pay for the cost to repair the roof and any damage.
Some may think, “the seller should be liable because they did not tell us about the leak.”
California law requires that almost every seller of a home must provide the buyer with a Transfer Disclosure Statement (form here). Page two of the disclosure requires the seller to disclose “aware of any significant defects/malfunctions” in any of several structural components, include roof(s).
“Aware” is the key word.
If you have a leak in your roof in a reasonable period of time after you purchase your home, is it also reasonable that the seller was “aware” the roof had a defect that would result in a leak?
Were there water stains in the ceiling when you first looked at the home? Did you inquire about the water stains and were told the roof had leaked and then repaired? Is the leak in the same location?
Perhaps that opens up to having seller participate in repairing the roof and any leaks, more likely if the seller did not actually have the roof repaired. If there was repair, did you get a copy of any guarantee from the roofer on the repair for future leaks? Is the guarantee transferable to a new owner?
Given the amount of time between rains in our region, proving a seller was aware of a defective roof that results in a leak(s) is very hard to prove.
I gave the question of the week to my friend and long-time real estate agent Mollie. In her reply she indicated if the seller had no issues and discloses as such, “you get what you paid for.”
So goes on, “there is nothing to say the roof, or any other system, is expected to be new and infallible.”
The important time for mechanical or system issue discovery is after you enter a contract with the seller and exercising your option to have a professional do a thorough inspection of the home. If the roof, or other system like plumbing or electrical, is called out by inspector as old, near end of life, etc, then hire a professional roofer, plumber or electrician to inspect the system and provide feedback on expected lifetime and cost of correction if necessary.
Many buyers obtain a home warranty policy as part of the closing, these policies cover partial/complete costs of repair or replacement for many systems in the home, including appliances, depending on the policy. Some of these policies also cover roof leaks. If you have a home warranty policy, check to see if your leak is covered.
Taking covering costs a step further, I asked another friend, Vali, who is an agent with a major insurance company and has written thousands of policies in her career, if roof leaks are covered under standard homeowner’s policies.
Her response was maybe. She states that a leaking roof on its own is a maintenance issue, and maintenance is not covered in homeowner’s policies. However, if there were “heavy rains and wind driven rain damage to the roof during a storm” that causes a leak, the policy would cover replacing the damaged part of the roof and any interior damage that resulted.
Regarding water damage, she also noted that damage caused by a sudden flow of water from within the home, say a burst pipe, is likely covered for repair of damage. Note, a damage to a slow flow of water would not be covered as, again, homeowner’s policies do not cover maintenance.
If you are unsure if damage to your home by some event is covered by your insurance or not call your agent to discuss the incident and possible coverages, costs and your deductible.
California is known as a litigious state, a roof leak is likely not a reason to fulfill the stereotype.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Rate should be climbing. Historically robust economic growth, strong consumer spending, higher wages, put strong upward pressure on interest rates. We are in a weird time in history as the economy grew at the fastest rate over two quarters since 2014, consumers are spending more and more money each money, and wages are outpacing inflation, and rates are steady*.
The data. Gross Domestic Production grew 3.3% in the 4th quarter of 2023, following 3rd quarter growth of 4.9%. Consumer spending rose 0.7% in December and wages were up 0.3%. The PCE inflation index preferred by the Federal Reserve was up 0.2% in December and up 2.9% from 2022, the lowest year-over-year increase in three years.
The data, historically, would have the Fed looking to push off any rate decreases in 2024 to see if the economy will slow, consumers will slow spending and wages stagnate. However, with the strong economic data, inflation is slowing—the antithesis of economic modeling.
*The asterisk We are adding some new lenders to our portfolio and as a result have available a few sources with better programs. As such, in today’s rate quote we see a dramatic drop in the 30-year fixed rate with the new opportunities. The drop is an anomaly to the overall rate market but indicative of the turmoil in the industry and its lenders.
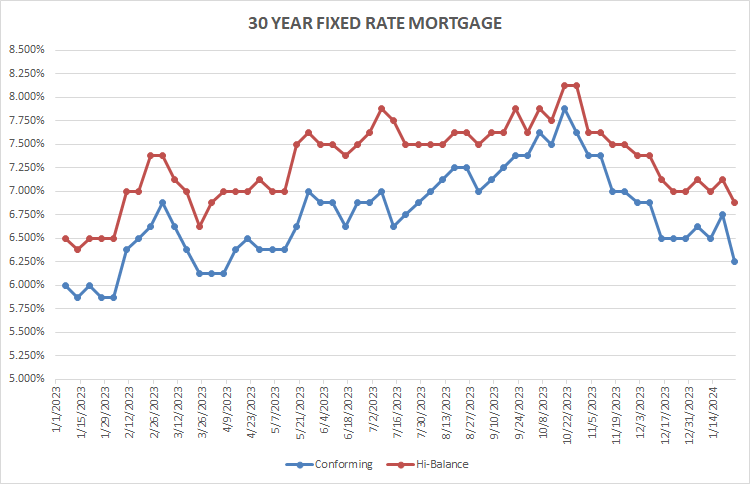
Rates for Friday January 26, 2024: As stated above, we see a drop in rates from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.25% Down 0.50%
30-year high-balance conforming 6.875% Down 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I always enjoy the rain, but as mentioned above, less so this past week with our roof leak. I have never like flat roofs, but we love our home and about one-third of our home has a flat roof due to addition made in the early ‘70’s. The cost of our love is every few years we have a small leak in some part of the roof that needs patching. A permanent fix involve what Leslie and I call “lottery money;” essentially adding a second story to the area of the home with the flat roof.
Having lottery money requires purchasing tickets, which I rarely do as I listen to my older brother who has always said the lotter is a tax for people bad at math.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


