

What was wrong with last week’s Weekly Rate & Market Update?
Question of the week: What was wrong in last week’s Weekly Rate & Market Update?
Answer: A gross understatement of the additional fees that will be charged on certain loan products by Fannie Mae and Freddie Mac (GSE’s).
A quick recap for those who did not read (gasp!) last week’s WR&MU, “Is the Federal government raising rates for mortgages?”:
The Federal Housing Finance Agency, under which the GSE’s operate, announced earlier in the month the addition of LLPAs (Loan Level Pricing Adjustments) to certain loan products; LLPAs are costs added to the cost of selling loans to the GSE’s.
An example of an LLPA is .500% (one-half of one point) to the base price of a loan for a mortgage that has a credit score between 720-739 for a loan-to-value (LTV) between 80.01% and 95%. For a $500,000 mortgage this equates to $2500. A lender funding such a loan and selling to one of the GSE’s will not take the hit, but passes it along in the price of the loan to the applicant. Therefore, for an applicant for which this applies, their closing costs have increased by $2500, or they can select a higher interest rate to eliminate the increase in cash to close, perhaps 0.125% higher in rate. (See this WR&MU from 2021 “What are points and do I have to pay them?)
For this client the choice is to pay $2500 more in closing costs or have a higher rate and pay $30-35 more per month for the mortgage.
Last week I made a major error and reported not the cost of the new LLPAs that are going into effect, but rather the change in rate locks for lenders as the date the LLPAs go into effect.
The new fees announced by the FHFA go into effect for all mortgages purchased by the GSE’s on or after April 1, 2022. Because it takes time from the time an applicant’s loan is funded by a lender before it is sold to one of the GSE’s, and that most applications have their rate locked before the loan is submitted to the lender, lenders are making the wise decision to slowly add the new LLPA fees to their rate lock sheets. This ramp up on the rates sheets will begin in the coming weeks.
The new LLPA fees apply to Second Home (SHL) and High-Balance loans (HBL), but not all HBL will be affected. High-balance loans for single family residences are those loan amounts from $647,201 to $970,800.
First, the carve out for those applicants whose mortgages will be exempt from the fee increases. Per the announcement from Fannie Mae, “…
to further support our efforts with affordable housing financing, we will no longer charge a high-balance LLPA for loans to first-time homebuyers with income less than or equal to 100% of area median income.”
Here are the new fees that will be charged, note the percentage amount listed is percentage of the loan amount as a fee (1% of $100,000 is $1,000 in fee), LTV range is loan-to-value, the percentage of the value of the property that is the loan amount (80% LTV of $100,000 home is $80,000, for HBL purposes, 80% of $1,000,000 home is $800,000), which means for a purchase the 100% – the LTV is the amount of the down payment (80% LTV calls for 20% down payment, or equity for a refinance).
From Fannie Mae’s Lender Letter January 5, 2022:
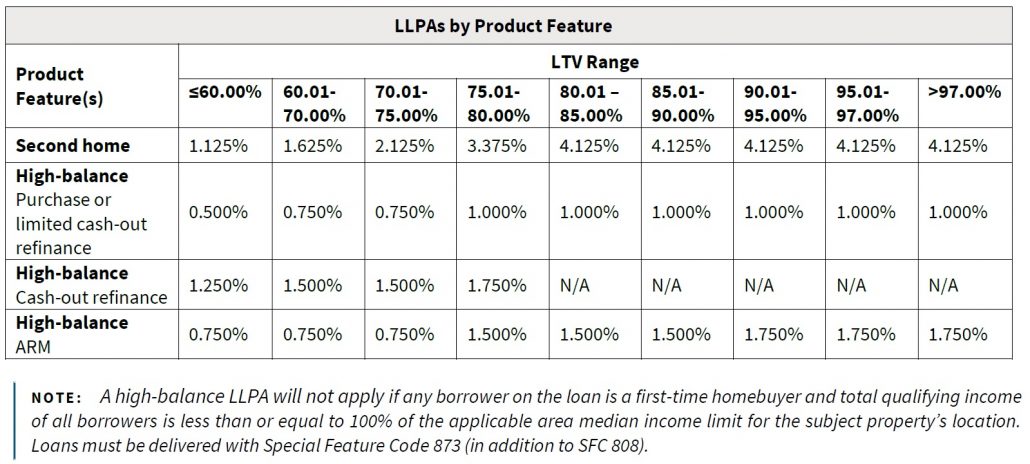
It is important to note that the fees added for SHL are for all conforming loan amounts, not just high-balance loan amounts.
Second home guidelines for underwriting are very similar to those for primary residences, as such it has been possible to purchase a second home with low down payments, or refinance with high LTV.
To put the chart into dollars:
Scenario A: You are purchasing a second home in Palm Desert for $500,000 and putting 20% down, you are financing $400,000. In addition to other closing costs, including points for the loan, there is a 3.375% of the loan amount fee added to the cost of the transaction, this is equivalent to $13,500. If you want to eliminate the cost of the fee by taking a higher interest rate, the rate will be approximately 4.25%, as opposed to before the LLPA announcement, a rate of approximately 3.5%. This higher rate is a difference of just over $170 per month.
Scenario B: You are purchasing a new home for $900,000 with 10% down and a loan of $810,000. On top of the loan points and closing costs, there is an additional 1% of the loan amount in fee due to the new LLPA, this is $8100 in funds at closing. If you wish to take a higher interest rate to avoid the high loan cost the rate would be 4.00% instead of 3.75%, a difference of about $115 per month.
Scenario C: You are refinancing your home and pulling cashout, perhaps to purchase your second home in Palm Desert, with a loan of $800,000. Your home appraises for $1,100,000; your loan is 73% LTV. In addition to the costs of the refinance, and assuming that like most transactions of this type the loan is a zero-point loan, the additional cost with the LLPA is 1.75% of the loan amount, $14,000. Because of the maximum rates available from lenders, no rates sheets currently have a rate to absorb both a no point mortgage and increasing the rate to cover the LLPA cost*.
*Last week I wrote that many, most, jumbo mortgage programs will fund loans as low as one-dollar more than the conforming loan limit of $647,200, in other words covering the HBL mortgage range. Moving forward, almost all cashout refinances for HBL amounts will be put through jumbo mortgage programs. As well, depending on pricing, so will most HBL refinances and purchases.
This, shifting mortgages away from the GSEs for second homes and high-balances, is the purpose of the LLPAs. The FHFA leadership sees the primary purpose of the GSEs is to enable homeownership for most Americans, not to enable and facilitate mortgages and homeownership for high earning, high net worth Americans. Second homes and properties that require HBL for financing do not fall within this purpose.
The long-term impact of the LLPAs will be slight on transactions in the high-balance sector of the mortgage industry, the jumbo and non-conventional markets will have very reasonably price mortgage products to mitigate the LLPAs. The long-term impact of the LLPAs will likely be somewhat significant in real estate markets with a high percentage of second home owners as the fees apply to all properties designated as second homes regardless of the loan amount.
The possible workaround for second home transactions up to $647,000 that are not eligible for most jumbo financing is to price the transaction as a second home and also as an investment property* and see which rate and cost is lower. Today the price would be slightly lower purchasing a second home using non-owner occupied/investor financing with a conventional loan than under the new pricing due to the SHL LLPA.
*If following this scenario and to ensure full integrity on the mortgage application no rent should be listed on the application since your stated intention with the property is not to use as a second home but as investment. As this scenario finds its way into use by borrowers, I am not the only lender who will look at this scenario, it would not be unexpected for another announcement from FHFA adding LLPAs to non-owner-occupied transactions. Which then opens up the can of worms of the FHFA undercutting the opportunity for affordable housing as landlords purchasing or refinancing one-to-four-unit investment properties will need to charge higher rents to cover the added costs due to FHFA regulations.
In the bigger picture, this is another step by FHFA towards separating the GSEs from the Agency and having them become government chartered private entities as they were before the Great Recession and the resulting Dodd-Frank Act.
Have a question? Ask me!
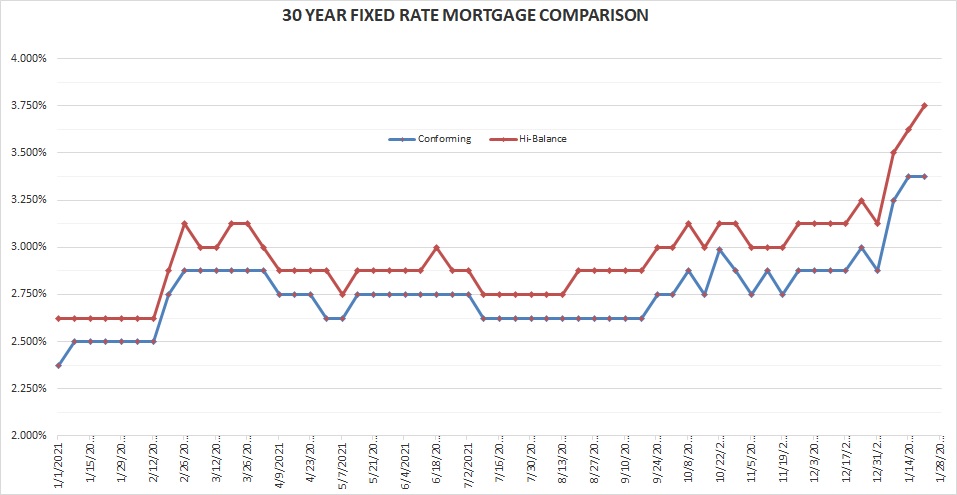
Rates for Friday January 21, 2022: Not a lot of economic news this week impacting mortgage rates. Investors held firm on bonds and mortgages as they have sold off in equities as they continue to react to the Federal Reserve announcement of raising rates sooner and more often, inflation and slowing consumer activity. The conforming rate takes a pause in its climb, the high-balance rate continues it increase, mostly due to the LLPAs discussed above getting nearer.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 3.375% Flat
30 year high-balance conforming 3.75% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Perhaps the best weekend for NFL fans is this weekend with two games on Saturday and Sunday, and all four games look to be very good matchups. Local fans are pulling for the Rams to knock Tom Brady out of the playoffs and a chance to return to the Super Bowl. As young as he is, 35, Rams coach Sean McVay is tied with the legendary John Robinson with most playoffs for a Rams coach with four. McVay has led the team to playoffs in four of his five years as head coach. When I heard this statistic it surprised me that in the long history of the Rams four playoff wins is the most that any coaches have had.
Meanwhile, baseballs fans, like me, are concerned that the owners’ lockout will lead to delayed, or cancelled spring training, and increase the chances the regular season will be impacted if a deal is not worked out soon. For some of us, while we like football it is merely a diversion until the baseball begins.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


