Did I miss it; did I miss the bottom for rates?
Question of the week: Did I miss it; did I miss the rates bottom?
Answer: Maybe.
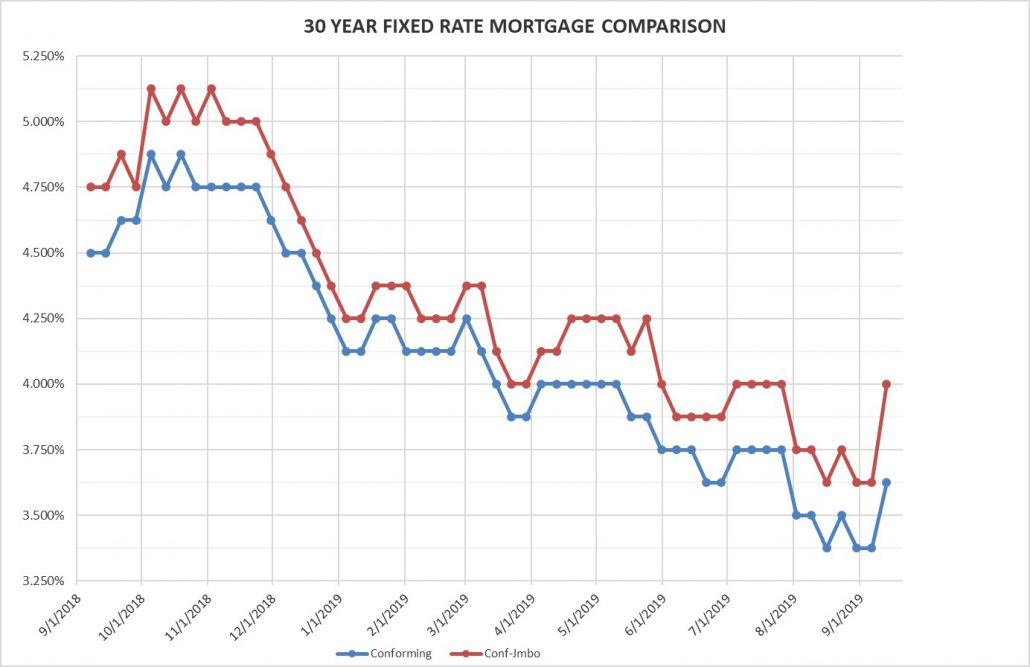
As you will see below rates this week went up the most in one week since the week ending October 5, 2018. When rates climbed at the end of last September they ended up peaking for about a month before we had a long slide down (down every Friday for five of six weeks).
Rate increases this sudden and this high are rare but they do happen. Why? Usually rates jump up on very positive economic news, political news, or a geopolitical event. This week the trigger for the rate jump appears to be the nice-nice talk between China and the United States on tariffs and trade agreements. This made investors positive about American businesses and removal of a drag on the economy and they left the safety of bonds and mortgages and bought equities, i.e. stocks in corporations.
Further pushing rates higher was today’s news that August was a very strong month for consumer spending as retail sales climbed 0.4% with a very large 1.8% increase in vehicle purchases. Consumer spending is 65-70% of our economy and if the cash registers continue to ring at a growing pace the economy will grow as well.
Also in the reports today was that hourly earnings are up 3.2% year over year, well above inflation which provides support for continued consumer spending.
All this good news in negative for lower rates for several reasons, primarily they show an economy that would be further away from the recession many pundits and media outlets have been used to fill the airwaves, interwebs and newsprint. Secondly, the potential of the trade war with China cooling down adds more support to pushing out any possible recession even further.
Currently the mortgage markets have priced in a rate cut of 0.25% by the Federal Reserve when it Open Market Committee meets, what is uncertain is whether there will be more rate cuts later this year. The economic and political news is making further cuts somewhat more unlikely—which investors have also been reacting to as some have been making decisions based on at least one further cut after next week.
If, for some reason the Fed does not cut its benchmark rate next week be prepared for another spike in rates.
So, did you miss the bottom? For the short term it appears that it is likely you did. For the medium term the answer is unknown as the current spike could be a sell-off to protect profits, in which case they will slowly move back to bonds when they feel equity markets are peaking, or near peaking.
All that said, even if you missed the bottom rates are really, really good. The current rates are where they were in July, which were near multi-year lows. If you have been considering making a purchase or refinance for the bottom of the market, you may want to consider doing so from the perspective of rates bouncing off what may have been the bottom.
Have a question? Ask me!
Typically this section of the WR&MU covers what is happening in the economy that impacts rates, today that was the first section!
Rates for Friday September 1, 2019: We will see over the next week or two if the spike in rates is a blip or a trend. I suggest not floating your rate and locking when you are able to avoid further rate loss should rates bump up more.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.625% Up 0.25%
30 year high-balance conforming 4.00% Up 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Thank you to everyone who sent happy anniversary issues to us last week. We had a great time scheduling nothing to do every day and knocking that important item off our to-do lists!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog