What is Escrow?
Question of the week: What is escrow?
Answer: We have a lot of first time buyers entering the real estate market, which means a lot of people unfamiliar with the terminology and different services in the industry. This question was asked to me this week by a young couple purchasing their first home. They have heard, “when you open escrow, when you close escrow,” but what is this “escrow” they will be opening and closing?
Dictionary.com defines escrow as “a contract, deed, bond, or other written agreement deposited with a third person, by whom it is to be delivered to the grantee or promisee on the fulfillment of some condition.”
By this definition escrow is a third person with whom a contract is deposited. For a contract to be valid it needs two parties, so part of the contract must be that both parties agree who will be the escrow, the holder of their contract.
In real estate, escrow is a third party that buyer and seller, or in the case of a refinance the borrower and the lender, use to transact funds from one party to the next; escrow is also referred to as the settlement agent. Given instructions agreed to by both parties, the escrow holder agrees to accept funds from the buyer, and the buyer’s lender if necessary, and then after paying costs for other services involved in the transaction, deliver the funds to the seller once all promises are fulfilled in exchange for a grant deed from the seller that is delivered to the buyer.
Escrow is neutral and has no agency contract with the buyer or seller, its agency is with the transaction. A simpler way to look at this is that the Smiths are selling their home to the Joneses. The Smiths are represented by Mary as their real estate agent and the Joneses are represented by Joe as their real estate agent. Once an agreement to price and terms is made an escrow account is opened with Sally at the escrow company, at that point Sally is the agent of the transaction representing the agreement the Smiths and the Joneses made.
If the Joneses wish to make a change to the agreement, say have $3000 credited to them to off-set some repair costs discovered during their home inspection, they notify Sally at the escrow company. Sally cannot just change the terms of the transaction, she first must get consent from the Smiths for the credit. Once both parties agree to any changes then Sally can amend the transaction.
Escrow plays a vital role in real estate transactions. Large sums of money flow through escrow companies on a daily basis for purchase and refinance transactions. Escrow is not only charged with making sure the initial instructions are followed but also that neither party is able to change the transaction without the consent of the other. At closing, escrow is responsible for disbursing funds to all the parties and services involved in the transaction, refunding overages to buyers or borrowers, pay fees to termite, title, home warranty, lender and themselves, payoff any liens currently on the property such as the seller’s mortgage or tax obligation and transmit the net proceeds to the seller. After the closing escrow provides a very detailed accounting of all funds received and disbursed to all parties.
Escrow companies and officers in California can be independent of any other affiliation or may be part of a title company or owned and operated by a real estate brokerage. If the escrow company for a purchase transaction is owned by the real estate broker representing the buyer or seller this must be disclosed to all parties.
Agents and lenders cannot require that a particular escrow company be used on any transaction; buyers and sellers have the opportunity to request a specific company if they choose, though it is customary in our marketplace the seller, or the seller’s agent, is given the choice of this service.
A good escrow officer and company is like a good umpire in a baseball game, you don’t always know how good they are until you get a bad one; thankfully the latter are very few and far between these days.
For the first-time buyers, all buyers, opening escrow is great news as it means your offer to purchase your new home was accepted. Closing escrow is even greater news as it means you now own your new home!
Have a question? Ask me!
No worries here. The Consumer Price Index for July showed that prices for consumers rose 0.3% for all goods and services and also for the “core” rate (gas and food are stripped out). For the past twelve months, the CPI is up 1.8%, which could be labelled a very benign inflation number. If price growth continues to decline there will be more support for the Fed to lower rates, however the last several CPI releases have shown a pretty steady rate of price growth just below 2%. The news is mortgage rate neutral.
What me worry? Says the American economy after the Commerce Department released retail sales data for July. July saw the largest one month increase in retail sales in four months at 0.7% above June’s sales. Taking out car and gasoline sales for the month and sales increased 0.9% for the month, with on-line sales jumping a staggering 2.8% from June—likely boosted (shoved up?) by Amazon’s Prime Day and its competitors also pushing their own deals available. Evidently the trade dispute with China is not preventing consumers from buying products, nor is it increasing the prices paid for those products. Overall the news should be negative for lower interest rates as consumer spending is 65-70% of our economy and strong retail sales should portend economic growth and higher rates.
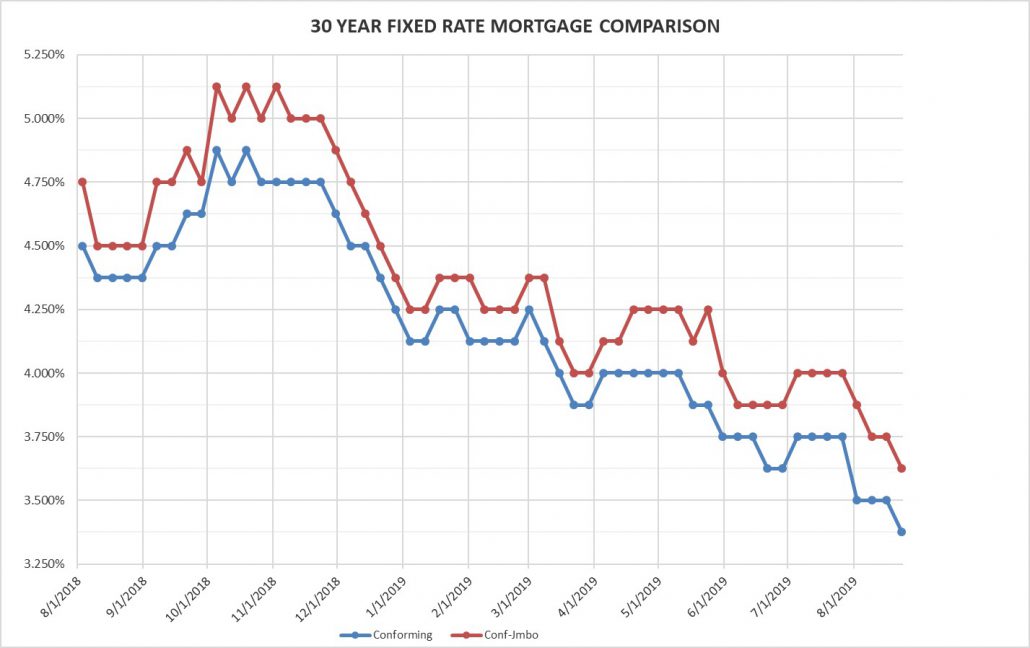
Rates for Friday August 16, 2019: Look at the pretty charts! Chart makers who track stocks and bonds had a fun week as they created what looked like silhouettes of mountain ranges with peaks and valleys. As I write this the Dow is down about 0.875% for the week and the S&P is down 3.67% since Monday’s open. In between we say a large peak on Tuesday and a deep valley on Thursday. All the while the rate on the 10-year Treasury dropped into mid-week before bouncing a bit today. Why all the activity? Concerns about a recession and European economies caused investors to sell of their equity holdings and purchase bonds and fixed rate investments—engaging in flight to safety (as discussed in the July 26th WR&MU). As discussed above, the concerns appear to be unfounded, however the result of the recession concerns is a dip in rates this week from last Friday, and the conforming rate at its lowest since the week ending December 9, 2016. Can they go lower?
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.375% Down 0.125%
30 year high-balance conforming 3.625% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Long time readers of the WR&MU know that this is the space I use to comment on personal events in me and my family’s life—for some I know this is the only part you read! (As an aside, my dad was very old school and could not understand why I always wrote this final segment—when I informed him it was probably the most read section, “Oh, then you should probably keep it.” Good advice.) This week these section is for parents of new adults.
Do you have a son or daughter who recently turned 18, or any children you still provide for over 18? Then please read on. Last year when our oldest daughter, then 18, flew off to Boston for college, before she left I had her sign two copies of a HIPAA Release Form (link below). Because she is an adult, no medical provider can provide either my wife or I any medical information about her. Should she have an accident or emergency and we are contacted that an event has occurred, federal law prohibits the medical provider from releasing any details.
With she and us each having signed copies of the HIPAA release form that we can provide the medical provider authorizing them to communicate with Leslie and I, they will be able to provide us with details of her condition, etc. We also have an electronic copy that we can quickly send to a healthcare facility across the country to expedite the information collection.
If you have any children 18 or older I encourage you to have them complete the form linked below and provide you with an original or copy. As well, if they are in college and/or living with roommates, encourage them to inform their roommate(s) of the form and where it is located (and to have them complete one for their parents). Privacy laws are very important to protect us, the HIPAA laws however can be detrimental for parents who need information and be able to be pro-active in their adult children’s healthcare.
Here is a link to the HIPPA Release Form we use. I hope none of us ever need to use it.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog