Where are you?
Question of the week: Where are you?
Answer: On I-94 West leaving Milwaukee and heading to Steamboat Lake, Minnesota (near Walker, near Bimidji).
Leslie has command of the rental Hyundai Tuscon at 7:45 local time while I spend a few minutes getting out the big economic news this week and rate shift.
Have a question? Ask me!
As expected, the Federal Reserve cut its benchmark rate by 0.25% on Wednesday—that move was already priced into the markets. After the announcement Fed Chair Jerome Powell held a press conference and his answers to some of the questions set the markets into a tizzy. The general expectation has been that the Fed would lower rates up to three-quarters of one percent this year (0.75%). At his news conference Powell indicated that Wednesday’s rate move could be a one-and-done, made to put some confidence into the economy. Sensing no more cheap money to borrow to buy, investors dumped their stock holdings and purchased bonds (see last week’s WR&MU for brief overview of relationship between stocks and bonds). This sent stocks prices and bond and mortgage rates tumbling. It should be noted this is the first time since the financial crisis of 2008 that the Fed has increased rates, the second longest period in history—the longest being from 1942 to 1954.
But wait, there’s more! In reaction to the markets collapse in 2008 the Fed began a policy known as “quantitative easing” during which it purchased U.S. Treasury bonds and Mortgage Backed Securities (MBS) to soak up supply and keep rates low. Last year the Fed announced a policy of “quantitative tightening.” Under this policy the Fed would start to sell its holdings of U.S. Treasury debt and mortgages. The impact of this policy is to tighten interest rates by lowering the prices on fixed rate assets, which as we learned last week pushes rates up. Originally the policy was to stay in effect for two more months, but the Fed cut the cycle by two months.
In other news…Economic data this week was counter to the Fed’s position of an economy that needs outside stimulus with lower rates. Positive economic news should lead to higher interest rates, ahead of the Fed rate cut we learned that consumer spending (65-70% of our economy) increased 0.3% in June and for the fifth month in a row personal income showed growth, increasing 0.4% for the month and up 3.2% from last year. With the gap between personal income growth and spending growth it is not a surprise that personal savings also increased, to 8.1%. Inflation concerns, a key factor for interest rates, are non-existent as prices increased a scant 0.1% in June and are up only 1.4% from last June; well, well below the Fed’s 2.0% inflation target. The inflation number is the only number that would hint at a rate increase, the other data all suggests an economy that is on track to continue record expansion that began in June 2009.
Lost in all the chatter about the Fed announcement will be today’s report from the Labor Department that the economy added another 164,000 jobs in July. More news that would suggest rates stay steady or face some upward pressure.
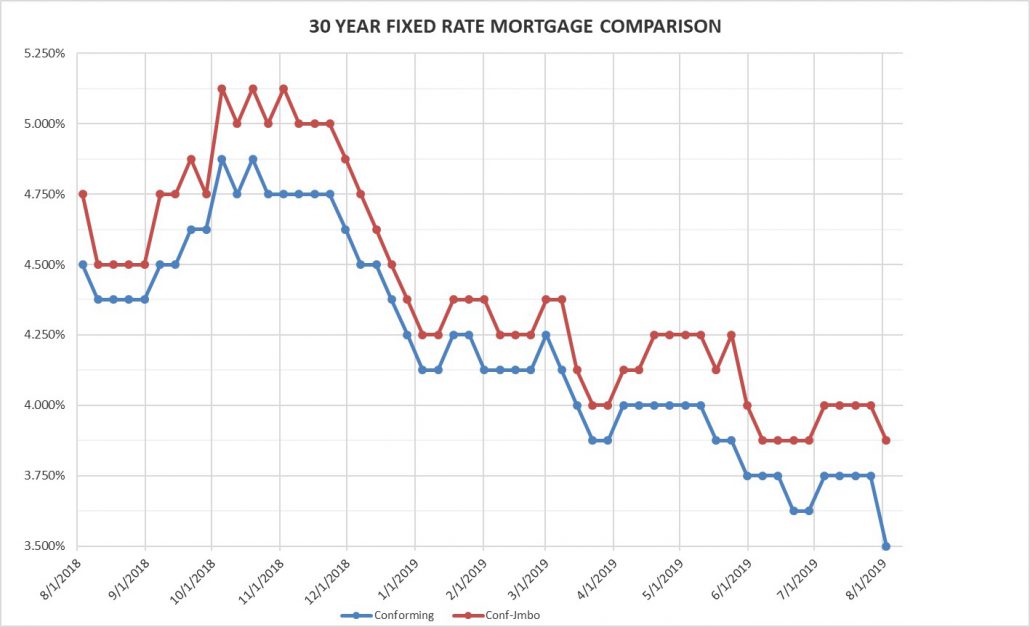
Rates for Friday August 2, 2019: The conforming rate is the lowest it has been since October 2016, hitting 3.5% this week following the Fed move and more importantly Powell’s comments. Will they last? Economic principles say no, and that they should not be this low.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.50% Down 0.25%
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Why Milwaukee? Why not? Leslie and I are having a Planes, Trains and Automobiles summer trip. We flew to Oakland last Saturday evening and the next morning board the California Zephyr train headed for Chicago. The trip was beautiful, though a bit challenging at night as we opted for the small “sleepette” compartment rather than a sleeper. We crossed the Sierras and Rockies during the day and we really enjoyed the ride. Two nights in Chicago which included a fantastic meal with friends one night and “obstructed view” seats the next night to see Hamilton—a huge discount in price for seats near the back of the mezzanine that blocked the upper part of the stage—rarely used and no negative impact on our enjoyment.
In plotting our trip with the ultimate destination being Camp Birchwood, where one daughter has been since May as a counselor and the other there since early July as a camper, we saw Milwaukee was not out of the way for our automobile leg of the trip. Since neither of us had ever been we decided to make a stop. We are glad we did! A nice lunch river side, a great walk through the lake side part of the city to a fun and tasty Irish pub, then a walk back to our hotel had us wishing we scheduled a bit more time in the city.
The next two nights a Camp Birchwood, which is owned and run by a man who was my counselor at the camp when I was young, and was started by his father who was my dad’s counselor when he was a kid. We fly home from Minneapolis on Monday with our girls to complete the trip.
Signing off from I-94 a bit southeast of Madison.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog