

Have you reviewed your…?
Question of the week: Have you reviewed your…?
Answer: In last week’s Weekly Rate & Market Update we asked “Do you have a will and a trust? The early returns are that it was timely as some replied to me that they had made appointments this week with attorneys to either review their current plans or to create a new one. I am hoping many more have done so and just not let me know.
Following up on the estate planning and review, a reminder to have other important items and documents reviewed.
Life Insurance Do you have enough coverage? Many families had life insurance policies for both spouses, others just for the spouse who is the sole, or primary, wage earner. Typically policies are purchased when purchasing a first home, or not long after marriage. Also typically, the policies are rarely reviewed or adapted to increase coverage as children are born, bigger and more expensive houses are purchased and wages increase. Review your coverage and assess what the needs would be should one, or both, get hit by the proverbial bus—will there be sufficient funds to ensure your family can retain the home, cover future education needs and other necessary living expenses.
Home Insurance Are you over or under covered? Most insurance companies are pretty good at adjusting coverages as costs of replacement increase over the years. Some are a bit too aggressive and others are not as adept at increasing coverages. Review your policy with your agent to determine if you have the proper coverage for your home, possessions and liability.
Auto Insurance While you are reviewing your homeowner’s coverage you should review the auto insurance as well. Do you have a child or two in college? Do they use a car? If not have them removed from your policy while they are at school and add them back when they return for vacations and breaks. Is the replacement coverage too much or not enough? Cars lose value pretty quickly and it is easy to over insure their value, at the same time if you have a lease or auto loan the coverage may not enable you to payoff the amount due should the car be totaled.
Credit Cards Do you have several credit accounts that are open but have no balance and you do not use them very often, or ever? I am an advocate for having one card with a fairly decent credit limit that is not used and available for emergencies. That said, I am not an advocate for having several different open accounts that are either rarely or never used, especially for department stores or oil companies. An open account that is rarely used is an opportunity for someone to hack the card and use it without your being aware for some time. Yes, the issuing company will likely reimburse you should this happen, but it is a painful process and the result will be that card being closed out—why not close it before this potentially happens?
Retirement If you have a 401(k) are you having enough withheld from your salary? Have you had raises in your pay but have not increased the amount you are saving for retirement? Likely you have a set percentage of your pay deducted every pay period for your retirement, which means as you get paid more you have more in dollars going into your account—but can you afford another one or two percent to be withheld if you are not yet maxed out on the amount you can put away? The same goes for those who are self-employed or make IRA contributions because your employer does not have a retirement program. Your retirement is getting more expensive every year because of inflation, money put away today—tax free—will be needed in your future so put away as much as you can.
Spending Habits Summer is a hard time to evaluate where you spend money as you are taking vacations, spending time with your kids and family are the beach, amusement park and likely going out to dinner more frequently. That said, thinking about the “normal” routine for when school is back in and what your spending habits are that could be changed to save money, such as to increase your retirement contributions, makes changing habits and routines easier when the summer schedule ends. Are you a buy a cup of coffee on the way to work person? Spend the summer making coffee at home and enjoying it in your kitchen before you leave or putting in a travel cup to drink in the car. You will save money, a lot since the $4.00 cup at the coffeeshop costs about thirty cents to make at home, and time since you will not have to pull into the drive-thru or stand in line at the coffee shop which may or may not be directly on your route. Coffee, lunch, dinners at home, a pair of shoes you like but don’t need or a new putter or driver that will look good in your golf bag but you will still likely shoot in the mid-90’s without spending the hundreds for the club.
Exercise Less than twenty percent of adult Americans get sufficient exercise. Can you set a routine in the summer for daily exercise that will carry over to the rest of the year? Are you a morning person? If so can you practice now to get the routine and habit of getting in your exercise before the kids usually get up for school? Are you an evening night person? If so can you find a routine that may have dinner be a bit later for the family but you are able to get in your exercise? A regular exercise routine will not only make you feel better today, and tomorrow, but will like cut down on future health issues, saving you money in expenses and potential loss of income.
These are just a few areas to think about making changes or reviews as you sit on the beach or by the pool on vacation watching your kids play. Set a plan in your mind and then execute the steps, most of them very easy, to implement your plan. You may find that all is in order, you have proper insurance coverage, your family spending habits are somewhat frugal without taking the fun out of life and you are in good health—if this is the case well done and you will find yourself at ease that you are on the right course. If you do feel you need to make some tweaks here and there, getting them accomplished will make you feel better and silence the voice in your subconscious that may have you at unease or feeling some guilt over “I know I should but…”
Off my soap-box.
Have a question? Ask me!
Consistently good. That would be my description of retail sales the past several months. June was the third month in a row retails sales grew 0.4% from the prior month. If gasoline sales are stripped out of the data the increase in sales is a very large 0.7%, but consumers benefited from lower gas prices in June which lowered their impact on total retail sales. Department stores continue to see declining sales as internet sales continue to increase about equal to the brick and mortar losses. Also, up for the month were sales at restaurants, home furnishings and clothing stores. Last week I expressed my opinion that the Fed should not lower rates this month, or in the next few months. The retail sales data for June supports my position. Higher retail sales should be negative for rates as consumer spending is 65-70% of economic activity, higher sales should lead to higher economic activity and growth which historically leads to higher rates.
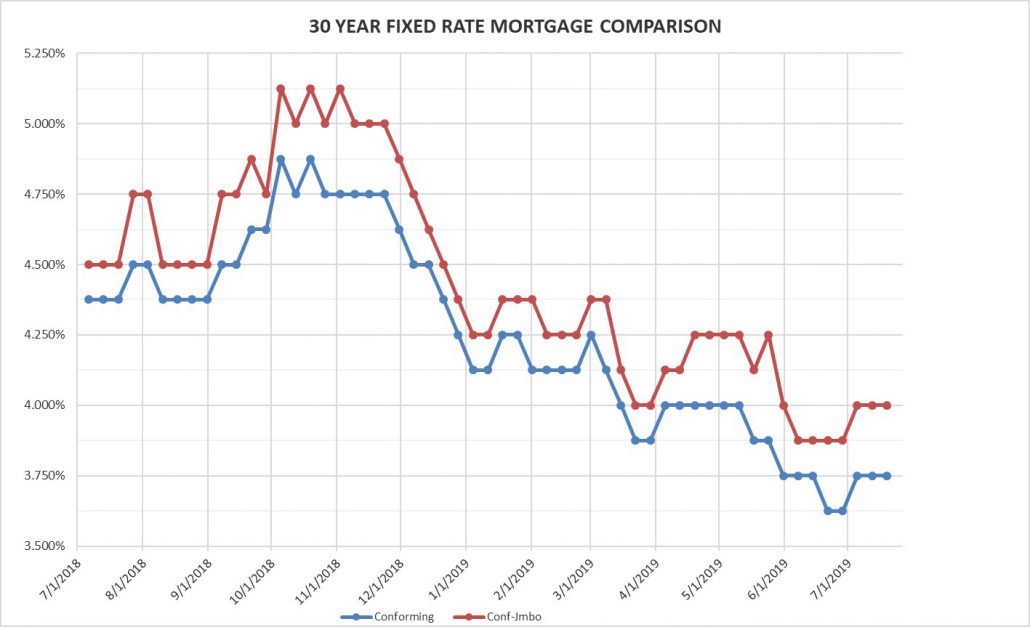
Rates for Friday July 19, 2019: With the Fed likely to decrease rates next week it is a good time to lock in rates if you can. In the past when the Fed decreased rates there was a spike in mortgage, and other, rates as investors think, they have decreased rates and may not need to again so we are at the bottom, so rates should rise later—causing them to invest in a way that leads to higher rates. Keep in mind, mortgage rates are not directly tied to the Fed’s interest rate, but are determined by investors anticipating future economic, monetary and political events. Rates are great, take advantage of them!
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.75% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Last week I outed myself as a nerd for musicals (one of my all time favorite movies is “Singing in the Rain” for example) and it is from this nerdness that I will pass along a movie review this week. Last weekend Leslie and I saw “Rocketman,” which if you are not aware is about Elton John. We had both read several reviews of the film and many were not exactly positive, especially those that tried to equate the movie to last summer’s “Bohemian Rhapsody” about Queen’s Freddie Mercury. The two films should not be compared as they are completely different formats and styles. “Rhapsody” was a biopic of Mercury with many scenes of the members of Queen, the actors, performing their music. “Rocketman” is much more of a musical, with Elton John’s songs being sung in the middle of a scene by various members of the cast. The movie is a bit dark, tells the story very well, is well acted and written. I encourage you to see it.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


