

What are your thoughts on using auto-pay for our mortgage payments?
Question of the week: What are your thoughts on using auto-pay for our mortgage payments?
Answer: I am 100% in favor of using auto-pay for making your mortgage payment.
That said….you know I have more to say!
First and foremost, the reason I like automatic payments is you do not need to remember to make your payment. That sounds a bit basic, however family vacations, travel abroad, an emergency that consumers your attention, an illness, are just some of the reasons I have heard over the years from homeowners who have a mortgage late on their credit report. Something happened to make it difficult mail a check, or to remember to mail the check, for their mortgage payment. Using auto-pay eliminates ensures your mortgage payment will be made in any scenario, apart from you not having enough money in your account for the payment.
There are two ways you can have your mortgage payment automatically paid every month, you can push the payment or have the payment pulled. I strongly encourage the former: push your payment.
What is the difference?
Almost every mortgage lender has a website that enables you to make payments on-line, or to set-up an automatic payment schedule (I say “almost” because some small lenders, usually private or non-conforming loan servicers). You sign on, enter your bank account information and either make single payments or establish a schedule so the mortgage servicing company pulls the payment out of your account on the same day every month that you have established.
The other option for having your mortgage payments being made automatically is using the bill pay feature with your bank. Set up your mortgage servicing company information on your bank’s website. Fill in the amount you want to pay, i.e. your mortgage payment, and the day of the month you want the payment pushed from you bank account to your mortgage servicer.
Why do I prefer automatic mortgage payments pushed from your account instead of pulled from your account by the mortgage company?
The primary reason is it puts you in total control. Above I mentioned several reasons that have resulted in homeowners not having their mortgage payment made on time. While many lenders have easy to navigate websites for making payments and establishing automatic payments. Some are not so easy to navigate, and/or the sites are challenging to navigate to be able to shut off their automatically pulling a mortgage payment from your account.
Have you ever had to have your bank account closed and open a new account because of fraud or theft? I have and it is a pain. Another pain is if you have payments that are automatically pulled from your account, the creditor initiates a payment when it is due, your account is closed and/or frozen because of the fraud/theft. Your creditor charges you for insufficient funds as they cannot receive your payment.
When we have clients that are refinancing or selling a current home and buying a new one, I tell them and then remind them, cancel your automatic payment. Those who push their payments have an easy task, logging into their bank’s website and cancelling the payment. For some lenders the process of cancelling is also easy, for others not as much.
When you do set up your automatic payment double and triple check the amount being paid, the lender address and account number are all correct. If your mortgage payment is $2035.14 and you mistakenly input $2031.54, your payment will be short and subject to late charges.
If you do not take my advice (how dare you!) and set up auto-pay with your mortgage lender, double and triple check that you have input your bank account routing and account number correctly. As well, some of the set ups are confusing in the set-up ask how much extra you wish to pay, I have had some people read that as how much you wish to pay. They input the amount of their normal payment and later learned that they paid extra the amount of their payment.
After the first payment was to be pulled by your lender please log onto to your bank account to ensure the payment was made and in the right amount.
If you wish to set up a new automatic mortgage payment because you would like a new mortgage, either to purchase your new home or to refinance an existing mortgage, please call me!
Have a question? Ask me!
Trade, and more trade, news this week that should put upward pressure on rates. On Wednesday President Trump and China signed phase one of a multi-phase trade deal. Nine months after Trump’s initial $50 billion in tariffs of some goods from China starting a trade war, the two biggest economies in the world took the first big step to ending the war and enabling more trade between them. The next day, Thursday, the Senate passed the U.S.-Mexico-Canada Agreement (USMCA) which will replace the North American Free Trade Agreement enacted in 1994. The USMCA will, should, level the field for trade between the three countries, notably strengthening labor standards in Mexico to, from the U.S. perspective, bring back jobs that went south with due to NAFTA. The bond and mortgage markets reaction to the trade deals was upward pressure on rates.
Trade pacts were part of the news this week, the other part was economic data giving us an idea of how the economy is doing; and there was quite a bit of data. Of high importance to mortgage rates was the news that the Consumer Price Index was up 0.2% for the month of December and up 2.3% for 2019. The 2.3% increase was the highest increase in CPI since 2011 when prices rose 3% for the year. Last week we saw that wages were up 2.8% in 2019; now that we have the CPI data we know that wages rose at a greater rate than inflation. The news is not positive for lower rates as higher prices lead to higher rates. Two-percent is the Fed’s target inflation rate, however even though CPI exceeded that number in 2019 prior comments from the Fed are that they intend to let rates be in 2020.
But wait! There’s more! Retailers finished the year well with sales up 0.3% in December. Every group in the retailers index increased except auto dealers and department stores. Brick and mortar department stores continue to see their sales erode and were down 0.8% in December from November; with Thanksgiving being late in the month this year, taking pre-Christmas buying away from November and pushing into December, the decline is very bad news. Taking out auto sales retail sales grew at a very robust 0.7% for the month. For the year retails sales were up 5.8% from 2018. The news is mortgage market unfriendly as it shows momentum for the economy into 2020 and a stronger economy should lead to higher rates.
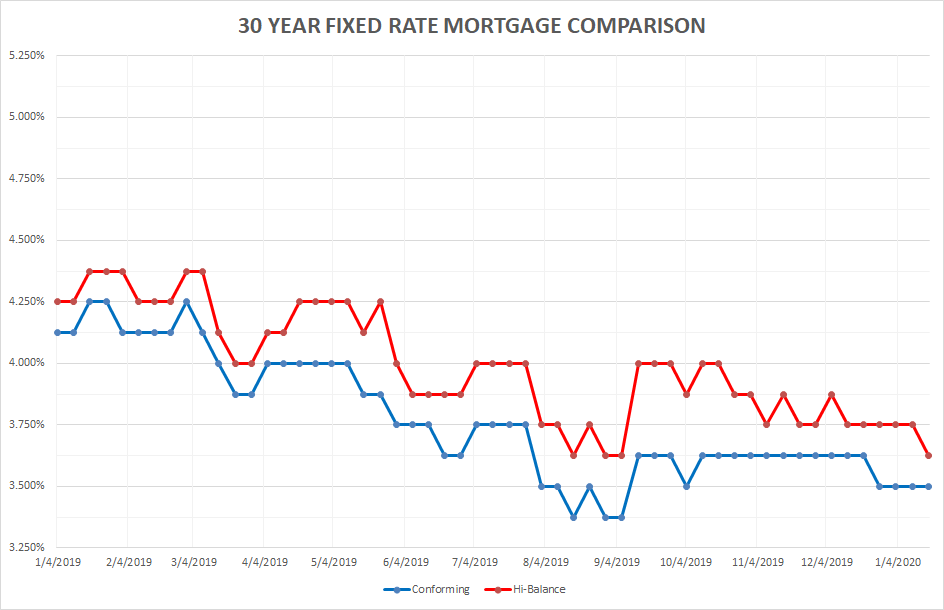
Rates for Friday January 17, 2020: Despite the news and events that should have pushed rates up this week, we see the conforming rate is flat from last Friday and some lenders have dropped their high-balance conforming rate from a week ago.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.50% Flat
30 year high-balance conforming 3.625% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Our not-official-but-it-really-is National Pastime is winding down as we have only three football games left in the season. Sunday will determine who will play in the Super Bowl, with a chance that the teams will be the same as they were in the first Super Bowl, played in January 1967 between the NFL champion Green Bay Packers and the AFL Kansas City Chiefs. The official attendance was just under 62,000 at the Los Angeles Coliseum, but that amount has been disputed as too high, by a lot. The game was broadcast on CBS and NBC, as those networks has separate contracts with the NFL and AFL respectively. The game was the start of the merger between the two leagues, which was announce six months earlier and concluded in the 1970 season when the teams’ schedules and leagues merged.
There was hope in September that the two Southern California teams could possibly face each other in the Super Bowl, but alas neither team made the playoffs. Neither did my team, the Eagles. Which leaves me only a monetary interest in the games this weekend as the only team I have left from the five I drafted in a pool I have been in for over 25 years is San Francisco.
My consolation prize is that my favorite player growing up, Harold Carmichael of the Eagles, was elected to the Hall of Fame this week. Hopefully the Niners will win two more games and provide additional consolation in the form of funds transferred from my friends to me!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


