


Why shouldn’t I save 15%?
Question of the week: Why shouldn’t I save 15%?
Answer: Because it may cost you 20%.
It’s that time of year. As much as many of us wish it would wait a few more weeks, retailers will not wait and are all set up for the holiday shoppers and sales. One of the more traditional “sales” retailers use is the discount they will give you at checkout if you sign up for a credit account.
Have you ever checked out at Macy’s during the Christmas shopping season with the perfect sweater for your significant other and not been asked, “Would you like to get 15% (or 10% or 20%) off everything you purchase today? All you need to do is apply for a Macy’s card, it will only take a few minutes…”
I cannot blame the department stores for the marketing strategy, their business is to move product and make profits. Their biggest profit margin is not the mark up on Coach purses or Levi’s, but on the interest they can charge to their clients with their credit cards, in some states like California up to 20% or more.
Over the years many studies have been done on credit usage by consumers at Christmas time. One constant in the studies has been how long it takes the average consumer to payoff the debt incurred through holiday shopping. While the intentions are always good, to payoff the Christmas debt by the Super Bowl, or Valentine’s Day, or….the reality is most people carry the debt into late April or early May.
Once the department store card(s) is paid off many people do not use the card again, unless they are enticed back to the store by an offer of another discount if the card is used. It is not that uncommon for us to see credit reports with three, four, five different credit accounts on a report from different retailers, all with zero balance and available credit. This is good, having zero balance on credit accounts. What is not always good is having accounts with no balances that are rarely if ever used as they present an opportunity for fraud.
The more accounts you have open the more opportunity for someone to access and account for their own use. Department store credit accounts are some of the most breached historically due to the access available to a wide range of personnel through the checkout registers and the lack of use by many creditors who may not be aware of any charges until well after they have been made.
My advice for your holiday shopping and using credit is to have an account that provides a benefit, points for airlines, hotels or able to credit back to your account to pay down the balance. Confine your credit use to a limited number of accounts, preferably one, to more easily keep track of your use and monitor activity. Turn down the instant discounts with a higher percentage fee on a new account and instead obtain longer term benefits from a credit account with a lower interest rate.
Using one credit account for all your holiday shopping will also enable you to pay the holiday debt off faster. Instead of shotgunning payments across several bank and department store cards you can focus your payments on the one account and reduce the balance faster.
Finally, a significant amount of holiday debt is racked up with last-minute purchases, or “gag” purchases. The latter bring mirth and joy to the donor and recipient, but most often goes from under the tree to a closet for a few years and then to the Goodwill—with perhaps a few detours through the years as a re-gift at a white elephant exchange.
One more tip, this is for those of you who know golfers. Do not buy someone you know a sleeve or box of golf balls unless you buy the brand s/he uses. Most golfers are pretty particular about the brand of ball they like and while your gift is well-intentioned there is a good chance your gift will be donated to someone else.
Okay, one more—some of us like whiskey, and decent brands are always welcome and they are often shared with the gifter and others throughout the year! 😉
Have a question? Ask me!
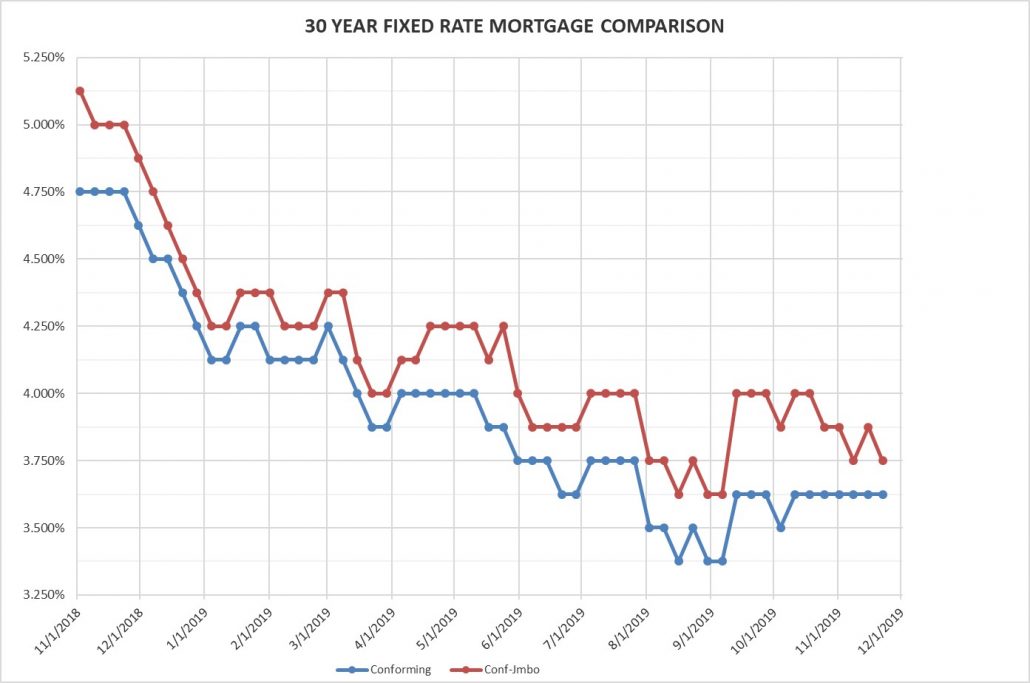
Rates for Friday November 22, 2019: Nothing major in the economic news this week that had an impact on rates. We continue with a stable rate environment, with the high-balance conforming rate drifting down again this week after its drift up week.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.625% Flat
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The Weekly Rate & Market Update is coming to you live from San Jose Airport as we await our connection to Boise, where we are going to visit sister Sharon and enjoy an early, or pre-, or practice Thanksgiving.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


