

What is mortgage life and/or disability insurance?
Question of the week: What is mortgage life and/or disability insurance?
Over the past few weeks I have had a series on insurance in the Weekly Rate and Market Update, this series covered home warranty, homeowners’, title, and mortgage insurances; the series concludes this week with mortgage life and/or disability insurances. Below, following the answer, is a link to previous questions of the week and answers for the other types of insurances.
Answer: Last week we covered mortgage insurance and noted that it does not cover the borrower, but instead covers the lender. This week we look at mortgage life insurance and mortgage disability insurance.
Once concern many families have when they purchase a home and have a large mortgage is how will the mortgage be paid if the primary income earner dies, or in some families if either income earner dies. Or, what if one of the income earners is unable to work for an extended period of time.
Many insurance companies offer life and disability policies that specifically cover mortgage balances or payments, or in some cases policies that cover both.
Similar to many term life insurance policies, a homeowner may purchase a mortgage life insurance policy that will have a fixed premium and pay off the mortgage should the policy owner pass away. Some of these policies have “riders” that add additional coverage, such as a disability component.
There are many factors that are involved, but essentially if you have a policy that covers mortgage payments should you become disabled there is a certain period of time you need to be disabled during which the insurance company will make your payments. For many of these policies amounts paid for the disability will reduce the amount that will be paid should you die and the mortgage life aspect of the policy is needed.
Some policies have decreasing premiums as the mortgage balance declines as the amount needed to payoff the mortgage declines. Other policies insure the original mortgage balance, which could leave some additional funds available for your spouse to use as s/he sees fit.
One potential drawback to a mortgage life insurance policy for some families is that the mortgage is paid off. How is paying off a mortgage a “drawback?” If it is the only substantial life insurance policy on the deceased, while the home may be paid off there are other living expenses that may not be able to be paid. With all the insurance money in the home, and the primary income earner no longer able to earn money to qualify for a mortgage, it may not be possible for the surviving spouse to access equity if needed for other expenses. With a more traditional life insurance policy the surviving spouse can take their time before deciding to pay off the mortgage, or may use the insurance money to supplement their income to meet monthly expenses and future expenses like college.
Before getting a mortgage life policy, with or without a disability component, it is advisable to research other life insurance options as well to find one that suits your family’s needs. Consider the needs of your family, the amount of coverage needed to cover lost income for a prolonged period of time and balance the needs versus the costs in terms of premium and also ease of underwriting for a policy in so far as medical exams and life-style (such as tobacco use, drug use, alcohol consumption, etc).
Links for prior posts in our insurance series:
Have a question? Ask me!
The streak is over. For the first time in six months, retail sales dropped from the prior month as September’s sales were down 0.3% from August. There is some handwringing over the data, rightfully so since consumer spending is approximately 65-70% of our economy. The retail sales data is based on dollars not units, so a drop in prices for gasoline and vehicles (auto dealers lower prices in the fall to clear their lots for the new models) has an impact on the retail sales data. Stripping energy and auto sales from the model and retail sales were fairly flat for the month. In addition, the large 0.4% gain in sales in August that was reported last month was revised up to 0.6% increase in sales from July, following a 0.7% increase in July. Looking at the three, four, six-month trend, could it be consumer-fatigue that caused a pause in consumer spending? Regardless of the wonky analysis the news is positive for lower rates as it supports potentially lower rates.
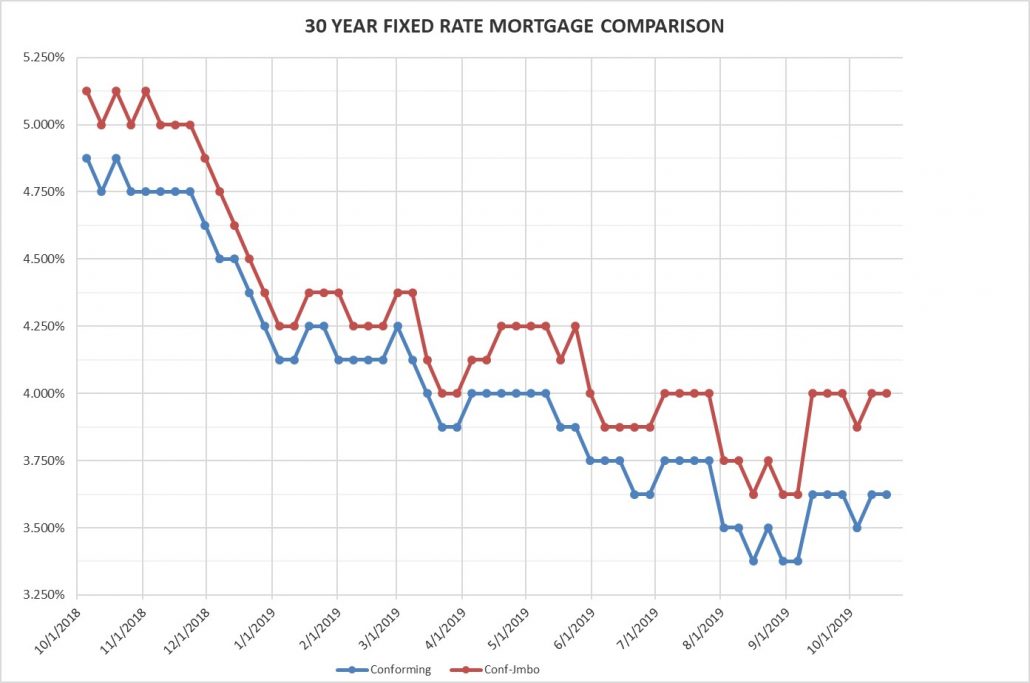
Rates for Friday October 18, 2019: There is plenty of opportunity for rates to break up or down from tangential economic news. The positive steps this week with the Phase 1 trade agreement between the United States and China, a signed deal between Great Britain and the European Union for Brexit are seemingly positive. The Brexit deal stands a good of a chance as not being passed as being passed by Parliament, and there are many more issues, now including Hong Kong issue, clouding continuing phases of agreements between the U.S. and China. Investors the past several months have been moving back and forth in their strategies from purchasing equities to fleeing equities for the safety of long-term fixed investments—like mortgages. No one’s crystal ball is anything but smudged and cloudy, though reading the news reports one would think many are seeing crystal clear into the future. For the average person buying or refinancing a home my advice is to ignore the chatter and lock in your rates as soon as you are able to avoid getting caught in a volatile time. Rates this Friday are flat from last week.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.625% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Long time readers of the WR&MU know that I love this time of year. Autumn, Fall, post-summer, means cooler weather, prettier late afternoon skies, color in our foliage, and all four major sports in action. Baseball provides us with the playoffs and, we hope, pitch-by-pitch tension as teams head to and through the World Series. Football is hitting its stride and the best and worst are becoming more apparent. Hockey and Basketball are beginning new seasons providing hope for many teams’ fans that this is the year!
I hope you have an enjoyable fall, and, depending what teams you root for, enjoyable outcomes for your favorite teams.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


