

When should we sell our home?
Question of the week: When should we sell our home?
Answer: This is a question many families are asking, regardless of their stage in life. The answer has become more complicated because of the prolonged historically low interest rates during the Covid era.
Those rates fueled a tremendous spike in home prices due to the low rates increasing purchasing power by 20-25% from pre-Covid interest rates. If already a homeowner, monthly mortgage payments declined significantly, in some cases as much as 50%, by refinancing.
Here we are six years after the on-set of the pandemic. The median home price has increased from $588,000 in May 2020 to $915,000 in April, 2026, a 56% increase in value.
The vast majority of those who purchased or refinanced during the pandemic have mortgage rates of 3% or less.
Using 3% as the rate, purchasing the median priced home in the state with 20% resulted in a monthly mortgage payment of $1985 per month. Fast forward to present day, with a mortgage rate of 6.375%, the monthly payment for purchasing the median home in the state is $4565 per month, a 130% increase.
When should we sell?
Why are you thinking of selling?
If you purchased your first home in the pandemic, you may need more room as your family has outgrown the 2-bedroom, 1-bath home. Your home has a tremendous amount of equity, but the prices of homes that fit your family’s needs have increased at the same rate. Selling your home will provide a substantial down payment, but still leave a large mortgage with a high interest rate.
Your family needs more room, you won’t need less room until your children leave for college or jobs, or relationships—so it will be a while that everyone is sharing the bathroom during the morning rush hour.
Waiting for prices to come down, if they come down, and if they come down will it make a big difference in your buying-selling calculus?
My advice in this instance is to get an idea of the price for the right-size home in areas you may want to live. Then we do the math, which is pretty simple. What is the estimated amount of the proceeds from the sale of your home for down payment on the new home, calculate the monthly payment for the new mortgage, taxes and insurance.
Based on your income and other debt obligations, can you qualify to purchase at this price? If not, what is the top price range, and where might those homes be?
Your monthly payment will go up considerably, that said, how much has your income increased since you purchased your home? How much longer will you be working and will you likely have higher income moving forward? What is the percentage of your income is the new payment—what was that percentage when you purchased your current home. So while the payment will go up a lot in actual payment, how much might it go up in “relative payment,” relative to your income.
If you need to compromise on location, is that compromise worth the increase in the size of the home for your family.
If the answers are yes, now seems to be a good time to sell your home and move into a home that has more space for everyone.
What if you have owned your home for twenty plus years. It is a large home that your family grew into, and out of as you are now empty nesters. You do not need as much space, want to down-size.
Having lived in your home for a long period of time, you have a low mortgage balance, and a lot of equity. This puts a wrinkle in your decision to sell, which we covered earlier in the year, capital gains. Depending on the appreciation of your home, and a few other factors, your net proceeds from the sale of your current home may be greatly reduced to pay Uncles Sam and Gavin.
However, because you are down-sizing, you will likely be purchasing a new home at a much lower price than the selling price of your new home. Is the difference great enough that you may not need a mortgage, or a mortgage so low the payment change may not be noticeable even with the higher mortgage rate?
Keep in mind, if you are over 55 you will be able to transfer your property tax base to your new home. If you purchase your new home for less than the sales price of your current home, your tax base stays the same; if you purchase for a higher amount, the difference between your sales price and purchase price is added to your new tax base.
For instance, if your current tax base is $350,000 and you sell for $1,000,000—if your new home costs $850,000, your tax base is $350,000; if your new home costs $1,100,000, your new tax base is $400,000.
As with the younger family, do the math. Where would you buy, what is the price, when the dust settles what is your payment and is it affordable? What is the tax liability for capital gains to the IRS, a flat amount, and the State of California, taxed as ordinary income.
When the calculus is complete, does it support your desire to down size to a smaller home with less maintenance, upkeep and other reasons you are considering such a move.
When is a good time sell?
In 2022, when rates and inflation jumped quickly and significantly, the WR&MU covered timing the market and is now a good time to buy a home.
The answer to our question of the week regarding selling your home, is not much different than when to buy a home—does the financial calculus enable you to meet your housing needs and desires?
If the answer is yes, do not try to chase prices and rates down, because in the long run, you can’t time exactly and there is a price for waiting.
Click below to schedule a time to go through your calculus as to give you the information you and your family need to answer our question of the week.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
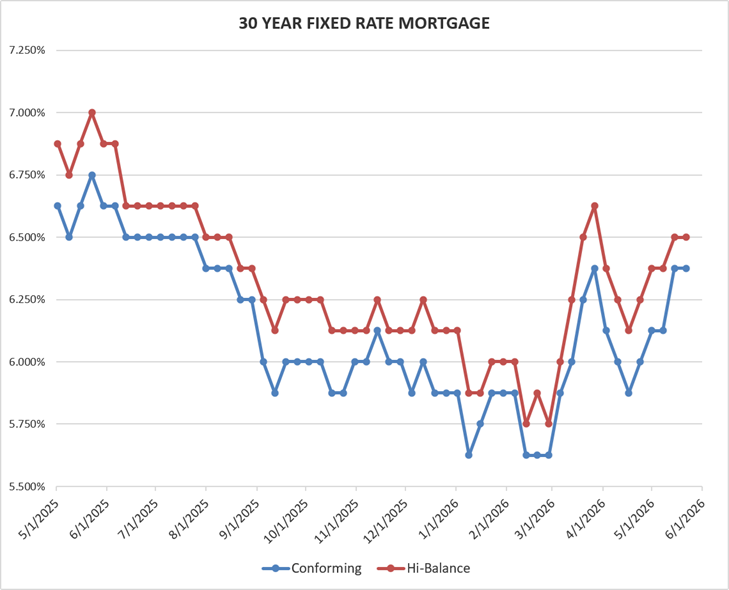
Rates for Friday May 22, 2026: Not a lot of rate changing economic news this week. Of note, however, is news that more members of the Federal Reserve who vote on whether to change their benchmark interest rate are forecasting a rate increase later in the year if inflation remains sticky, or increases further. There was some reaction, up, in the rate markets, but by today rates have settled back to be flat from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Flat
30-year high-balance conforming 6.50% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
As we enjoy our barbecues, travel, relaxation of our three-day weekend, take time to be thankful for those who have given their lives to defend the freedoms and liberty we enjoy.
We are not a perfect country, but we are more less perfect than any other, and I am grateful to be a part of this great nation.
Dennis


