

Can we get a reverse mortgage 2nd?
Question of the week: Can we get a Reverse Mortgage 2nd?
Answer: Yes, if eligible**.
We have had conversations with some homeowners who are age qualified (one signer/occupant 62 years old or older) interest in the financial benefit a reverse mortgage can have, but do not want to payoff their current mortgage with an interest rate well below current rates.
An option for them is to get a reverse 2nd mortgage.
Two weeks ago in the WR&MU, we explained how reverse mortgages work and their benefits.
A reverse 2nd works in the same manner, with an additional factor in determining the loan amount—your current mortgage. Depending on your age, the value of the property, the current interest rate, and the balance on your current mortgage.
These factors are put into an equation to determine how much equity you currently have in your property, and how much of a reverse 2nd you can obtain.
Example: A couple has a home valued at $1.2 million, with an existing mortgage of $378,000, based on the age of the youngest spouse and the current interest rate for a reverse 2nd (9.5%), they are eligible for a $250,000 second mortgage.
The difference between the reverse 2nd and the reverse mortgage discussed two weeks ago, is that it is not an equity line so all the funds must be obtained at closing—no taking some of the available funds at a time.
Comparing the reverse 2nd to a traditional fixed 2nd mortgage with a 30-year term with a 8.25% rate, the borrowers conserve a lot of cash with a reverse 2nd as opposed to a payment of $1878 per month.
With a traditional 2nd mortgage, the couple will be paying $1900 on their primary mortgage and an additional $1878 on the traditional second. On a fixed income that covers most of their expenses, with the remainder coming from retirement accounts, the couple will need to withdraw an additional $22,500, which is taxable, to cover the payments on their second mortgage.
Using the reverse mortgage, they can retain their current cash flow and withdrawals from their accounts to maintain, reducing their tax liability.
Reverse mortgage products are not suitable for everyone who is eligible, however it is very suitable for many seniors living on fixed income and retirement funds, if they have them. They can retain their homes and possibly, probably in many cases, improve their long-term financial security.
**Glaring omission in prior WR&MU I failed to include the paragraph that the income required to qualify for a reverse mortgage is incredibly low. Depending on region of the country, number of people being supported, size of the home, taxes and insurance, most seniors qualify on their social security income. Whereas with traditional mortgages the total housing payment of mortgage, taxes, insurance, HOA fees if applicable, plus payments on other debt, cannot exceed 40% (some exceptions).
For the above example, to obtain the second, with no credit card payments or other loans, they would need about $10,000 per month to qualify for the loan.
For the example of purchasing a home with a traditional mortgage used in the April 11th WR&MU would need around $8000 per month or more depending other debt they may have.
If you, or someone you know, is interested in learning their options for a reverse mortgage, or reverse 2nd, please contact me to run the scenarios available.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Consumer sentiment dropped to its second lowest level since the survey started in 1952. This may be good news for mortgage rates, but is not good news for economic growth. Spooked and uncertain about their economic future due to the uncertainty as to what is, and will, happen with tariffs on imported, and on U.S. exports by other nations, due President Trump’s zig-zag, yes-no, a lot-a little, pronouncements on where tariffs will land for certain nations and certain products, consumers are starting to turtle. Low consumer sentiment should present in lower consumer consumption, impacting retailers, and wholesalers. The biggest concern for economists, investors, and savvy consumers, is stagflation hitting our economy.
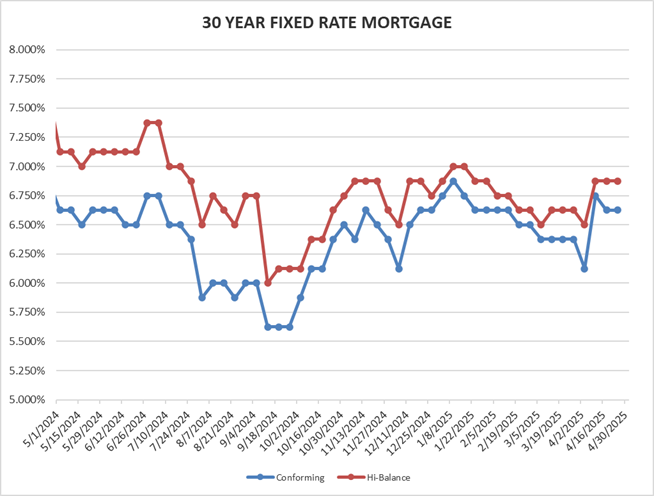
Rates for Friday April 25 2025: After spiking earlier in the week, rates have floated down the last few days, ending the week even with last week.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.625% Flat
30-year high-balance conforming 6.875% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It’s not as quiet. On our daily walk around the neighborhood with Sammy*. Our route depends on what time we started. This is due to the start of the elementary and middle schools that is a few blocks south of our neighborhood and the kids, some with parents some without, funneling into California Avenue.
During the schools’ spring break last week, our walks were quiet, too quiet. We enjoy seeing the kids and families on their morning commute to school. Over the years we have seen kids take the walk to elementary, then middle and finally towards Atlantic to catch the bus to Poly High.
This week the foot traffic to the California Avenue funnel was busy as usual—welcome back to school kids.
*While it is a walk for Leslie and I, it is scrolling canine social media for Sammy as he sniffs out posts and comments from other dogs on trees, fire hydrants, bushes…the trolls in this social media environment are the coyotes who evidently leave some nasty and hurtful messages and comments.


