

Should we use an FHA loan to buy our house?
Question of the week: Should we use an FHA loan to purchase our home?
Answer: Maybe.
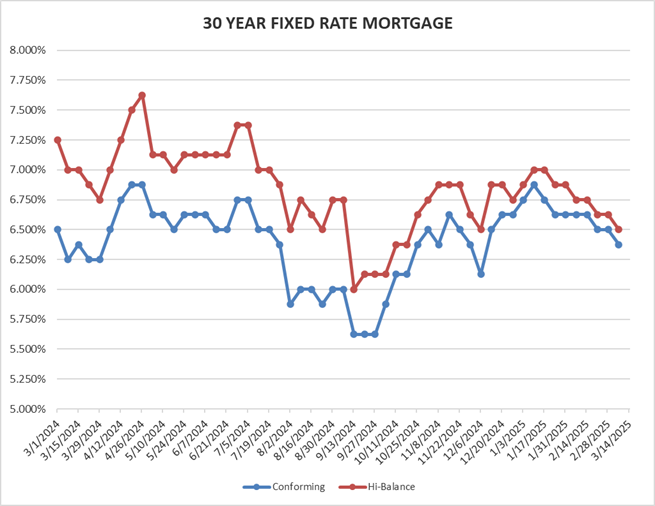
Every Friday we provide a snapshot as to what mortgage rates are doing on a week to week, month to month basis. The parameters use conforming mortgage products for a purchase transaction with 20% down, a 740 FICO at a cost of 1.25 points (1.25% of the purchase price) locked in for 45 days.
For many years the WR&MU included FHA mortgages, but they were removed when the rate differential between FHA and conforming mortgages was very small and the amount of FHA mortgages being applied for and funded in our local market declined significantly.
FHA has a not great reputation in the real estate industry, some of it valid, much of it not. For years FHA was considered a first-time buyer, hard on their luck, only low-down payment, mortgage product, that had more challenging underwriting than conforming mortgages. The latter statement is not true, in some, many, instances, FHA can be more forgiving than conforming underwriting.
For real estate agents there was an added factor that FHA was harsher on property conditions than conventional mortgages, which could lead to delays or challenges in closings. This is true, in general appraisers do a more thorough inspection for FHA appraisals than for conforming loans as they call out property defects, especially what FHA considers health and safety issues. If the following are present, they issues will have to be cleared up before closing; issues such as peeling, chipping, scaling paint, broken or cracked windows, missing switch or electrical plug plates, non-working heating systems, are some of the examples.
A very big historical disadvantage that FHA has had over conventional mortgages is mortgage insurance. For conforming loan amounts that are 80.01% or more loan-to-value (i.e. less than 20% down, or combined down payment and second mortgage at closing less than 20% of the purchase price), the mortgage insurance cost is considerably less than the mortgage insurances required for FHA.
Yes, insurances, plural. Conventional loan mortgage insurance is a percentage of the loan amount paid on a monthly basis until the loan is paid off, or the borrower can provide evidence the loan amount is 78% or less of the home’s value, provided some other factors also met (timely payments), or at the mid-point of the mortgage’s term, i.e. if 30-year loan on the start of the 15th year.
For FHA there are two mortgage insurance premiums, an upfront premium added to the loan amount at closing and a monthly premium. Unlike mortgage insurance for conforming mortgages, FHA monthly mortgage insurance is paid as long as the loan if open.
The upfront mortgage insurance premium is 1.75% of the loan amount, the monthly premium is determined by your loan amount and down payment.
Purchasing a one-million dollar home with 5% down, and a $950,000 mortgage, using a 740 FICO score, the monthly mortgage insurance for a conventional loan is approximately $348 per month. For an FHA loan the monthly premium is approximately $554 per month, as well the upfront mortgage insurance premium of $16,625 will be added to your loan and amortized at the loan’s interest rate for 30-years.
In total the mortgage insurance for FHA adds almost $650 per month to you mortgage payment $348 per month for a conventional loan’s mortgage insurance.
So why would you consider an FHA loan?
Because the interest rate is plus or minus one-percent (1.00%) lower than a conventional mortgage with the same parameters.
Loan Rate PI MI Total
Conforming $950,000 6.50% $6005 $348 $6,353
FHA $966,625 5.50% $5488 $554 $6,042
As you can see, because of the one-percent lower rate on the total loan amount, the total monthly mortgage payment for the FHA loan is over $300 per month lower than the payment for the conventional loan.
If the mortgage insurance on the conforming loan is lifted after the required two-year waiting period to be eligible, the payment absent the mortgage insurance will only be $37 less per month than the FHA mortgage. During that two-year period the FHA borrower will have paid almost $7500 less in total payments on their loan. Put another way, that translates into about $50,000 more in purchasing power.
If you are using a low-down payment for your home purchase, you may want to consider using FHA financing.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Holding steady-ish, for now. Today’s job data for February from the Labor Department showed 151,000 jobs added in the month, halfway between January’s 125,000 new jobs and the Wall Street expectations of 170,000. In part due to more severe winter weather for the month, the unemployment rate inched up to 4.1% from the January’s 4.0%. Wages slumped to a 0.3% increase in February from the 0.5% increase in January; year over year however the 4.0% increase in pay is outpacing inflation.
Not yet impacting the labor markets, are the layoffs of federal workers, most of which have occurred after the Labor Department collected its data. Looking forward forecasts are for a choppy, and slowing number of jobs due to cuts to the federal workforce and spending which will impact other sectors of the economy. As well, with President Trump’s on-again-off-again-delayed-again changes in tariff rates for different nations,there is great uncertainty as to the impact foreign trade will have on our nation’s labor force.
Rates for Friday March 7, 2025: A roller coaster in the mortgage backed securities markets this week, starting high (lower rates), dropping (higher rates) then climbing back today. The result is rates at their lowest in three months.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Down 0.125%
30-year high-balance conforming 6.50% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Time to wake up in the dark again. Just as I was enjoying waking up at dawn I will need to adjust back to a dark house as I make my way to the kitchen for my first cup of coffee and the morning papers. Count me as one of those who wish we would pick a time and stick with it year-round.
Don’t forget to set the clocks back before you go to bed Saturday night or you’ll be late for church, soccer tournament, mimosa’s with your besties….


